
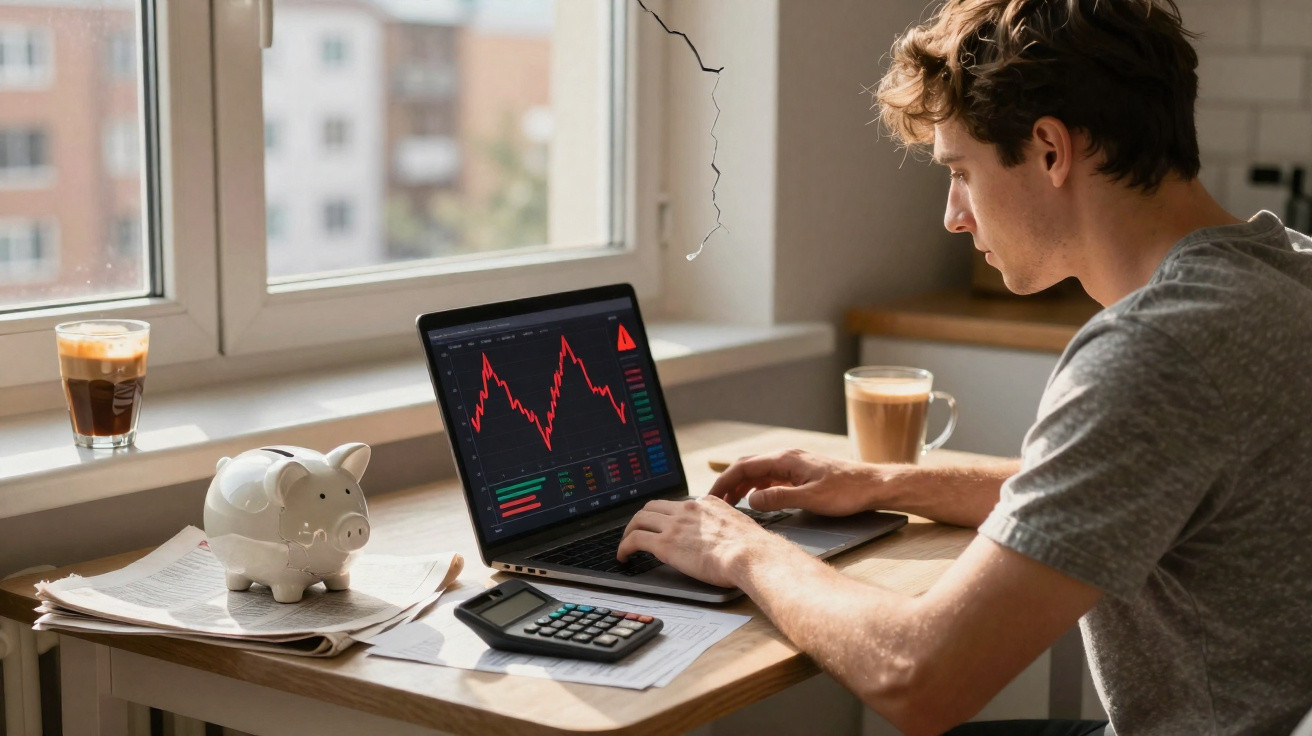
The room felt unnaturally silent for a Monday morning. Monitors first glowed green, before red lines began spreading across them like a crash filmed in slow motion. A trader in his thirties, shirt sleeves pushed up, murmured a term more often heard in war documentaries: “Capitulation.” At a nearby desk, an alert appeared: yet another central banker declaring inflation was “under control”, while food bills rose and rents showed no sign of falling.
Outside, a person waited in line for a €6 latte, scrolling on their phone as their savings app declined in real time.
The atmosphere carried an unsettling blend of denial and fear.
Something enormous is groaning beneath us.
Central banks are losing the script - and everyone feels it
For years, central banks played the role of the steady adults in the room. Interest rates fell, markets climbed and crises were contained - that was the familiar storyline. Then the pandemic arrived, followed by money creation on an unprecedented scale and an inflation surge initially brushed aside as “transitory”, before being reluctantly recognised as persistent, structural and painfully tangible.
Those institutions are now caught between two damaging choices. Push harder against inflation and risk damaging the economy; loosen policy and risk another burst of price rises. The trust they once commanded has given way to doubt, and people are beginning to ask a dangerous question.
What if the pilots no longer have control of the plane?
View the past three years as a slow-burn thriller. During 2020 and 2021, trillions of dollars, euros and yen poured into markets to stop the global economy from seizing up. Shares, crypto and property all seemed to float upwards. Your neighbour could suddenly call themselves a “short-term investor” after doubling their money on a meme coin.
Then inflation reached double figures in parts of Europe. The US experienced its fastest price growth for four decades. Food banks saw greater demand as luxury watch prices surged. Central banks hit the brakes, increasing rates at their quickest pace since the 1980s. Mortgage payments rocketed, sending a quiet but profound shock through the middle class.
This is more than a Bloomberg chart. It is a landlord increasing the rent, a shopper returning the branded pasta to the shelf, or a household abandoning its plan to buy a home.
Away from public view, the arithmetic has become grim. Governments borrowed extensively when money cost almost nothing. With rates now higher, debt servicing is consuming a growing share of public budgets. Meanwhile, economies are slowing as consumers cut spending and firms shelve investment plans.
Markets can see the bind. Cutting rates prematurely could reignite inflation, while keeping them elevated could cause something to break: a major bank, a shadow lender or a government bond market. This is why some analysts speak of a “financial earthquake” rather than a mild correction.
The confidence that kept the entire structure together rested on one assumption.
That someone, somewhere, was still in control.
How a brutal financial crash could unfold - and what people can do
Picture the first shock emerging in the bond market. Yields jump as investors begin worrying quietly about government debt, before abruptly selling assets they previously regarded as the safest in the world. Equity markets shake. A large investment fund finds itself on the wrong side of a trade and must sell anything it can, at whatever price buyers will offer.
Credit contracts. Businesses dependent on cheap borrowing find they cannot refinance their debts. Redundancies start quietly, then arrive in waves. Television presenters discuss “volatility”, but your friend who works in tech tells you they have lost their job. At the same time, your supermarket receipt continues to lengthen.
That is what specialists mean by a systemic shock: it does not strike a single industry alone, but confidence itself.
Most of us know the feeling: your banking app starts to resemble a horror film and you work out how long you could cope if the worst happened. In 2008, people watched their pension savings halve within months. In 2022, millions saw their crypto holdings disappear after several punishing weeks.
During the UK’s mini-bond crisis, pension funds came close to collapsing behind the scenes and were rescued only by an emergency Bank of England intervention. In the US, several regional banks failed within days in 2023 after social-media-driven withdrawals. This was not theoretical for those standing outside shut branches or spending hours waiting on hold to call centres.
Some experts fear that the next crash could be both swifter and more severe, because everything is now more interconnected.
The explanation is not mystical but mechanical. Years of exceptionally low interest rates drove money towards riskier areas of the market: junk bonds, leveraged loans, speculative technology companies and opaque “alternative” funds. At low rates, those risks seemed smart; once rates rose, they began to resemble a fuse.
Inflation forms the other half of the trap. When prices increase, central banks seek to cool demand by lifting rates. Yet if inflation stems from disrupted supply chains, geopolitics or energy shocks, higher rates hurt households and businesses without truly addressing the underlying cause. Households are squeezed from both directions: higher prices and more expensive borrowing.
That’s the moment when faith in the system can flip from “this will pass” to “this might break.”
Protecting yourself when the experts whisper ‘earthquake’
Once the jargon is removed, one straightforward principle stands out: make yourself less fragile. This does not require selling everything in a panic or hiding cash under the mattress. It means calmly asking, “If my income dropped for three months, what breaks first?” and then planning backwards from the answer.
Some people begin by creating a modest, unexciting cash reserve - several months of expenses in a simple savings account, even if its interest rate is unimpressive. Others review their debts and tackle the riskiest portion first, such as high-interest credit cards, variable-rate loans and speculative margin accounts.
The purpose is not to make money from a crash. It is to remain standing while others fall.
Bubbles and crashes have a cruel psychological effect. When prices are rising sharply, holding cash can make you feel foolish. When prices collapse, you can feel frozen, believing that selling would “lock in the loss.” You then alternate between checking apps and pretending nothing is happening. To be honest, nobody really does this every single day.
The key emotional error is to handle a long-term life plan as if it were a weekend in a casino. People pursue the hottest asset, then sell at the worst possible time because everyone around them is panicking. A steadier strategy is dull and profoundly unglamorous: diversified, gradual and intentionally unspectacular.
You do not have to identify either the peak or the bottom. You need to avoid being compelled to sell at the worst moment.
“Crashes don’t destroy wealth evenly,” one veteran fund manager told me. “They punish the most leveraged, the most complacent, and the most overconfident. The rest get bruised but survive. The system resets, but people don’t forget how it felt.”
- Check your exposure: Record where your money really is - banks, apps, funds, crypto and pensions. A muddled picture is dangerous during a crisis.
- Cut clear risks: high-interest debt, platforms that seem “too good to be true”, and concentrated positions in one share or token.
- Build buffers, not bravado: Small, steady actions - additional savings, diversified funds and perhaps a second income - are better than dramatic last-minute decisions.
- Know your pain point: Set in advance the level of loss you can bear before taking action, so that fear does not dictate every click.
- Stay curious, not hysterical: Follow a handful of credible sources and disregard all-caps apocalypse threads that merely raise your cortisol.
A future built on shaken ground
If experts are correct and a brutal crash is genuinely approaching, it will not be only a financial event. It will also be an event of trust. People already sense that prices no longer reflect their wages, that central banks use language disconnected from daily life, and that markets swing wildly while their own room for error has narrowed to nothing.
A severe shock could deepen that divide. Younger generations may finally abandon the belief that the old formula - study, work, save, retire - still works. Politicians may be tempted to blame shadowy figures or “speculators”, while quietly depending on those very markets to finance public budgets. Some will argue for tighter control, while others will demand a reset.
There is, however, another way to read the present moment. When systems become unstable, people rediscover more immediate forms of resilience: family, local networks, practical skills, shared homes and new ways of earning beyond the conventional nine-to-five. This is not a romantic survival fantasy. It is already occurring in cities where rent consumes half a wage packet, and in countries where inflation gradually erodes every salary.
The coming financial earthquake may still be several tremors away. Or it may already be under way, unseen in spreadsheets but apparent in the faces of people studying their receipts at the checkout. The more important question is not “Will the crash come?” but “Who will we be when it does?”
| Key point | Detail | Value for the reader |
|---|---|---|
| Central banks’ shrinking control | Persistent inflation and high debt levels restrict their capacity to lower or raise rates without setting off further crises. | Helps readers see why official reassurance can feel disconnected from their everyday experience. |
| Systemic risk across markets | Years of cheap money drove investors towards leveraged, interconnected positions that may unravel violently. | Explains why the next crash may be faster and deeper than earlier downturns. |
| Personal resilience over prediction | Prioritise reducing debt, diversifying risk and creating buffers rather than attempting to time market peaks. | Offers practical actions readers can take even when they cannot influence the wider system. |
FAQ:
- Question 1 Are experts really predicting the “most brutal crash in modern history,” or is this just clickbait?
Answer 1 Some prominent economists and investors are using very stark language because several risks are colliding at once: persistent inflation, high interest rates, record global debt and stretched asset valuations. Experts do not all agree on how large the next crash might be, but there is widespread concern that the next downturn could be more severe than a normal recession.
- Question 2 What signs should I watch that a financial earthquake is starting?
Answer 2 The earliest warnings often appear in bond markets and credit spreads rather than share indices. Rising government bond yields, bank funding stress, sharp currency moves and sudden central-bank policy reversals can all indicate deeper trouble. In everyday life, growing redundancies, stricter lending standards and increasingly frequent emergency press conferences are warning signs.
- Question 3 Is keeping cash the safest move right now?
Answer 3 Cash can shield you from market volatility and provide flexibility during a crash, but inflation gradually reduces its purchasing power. A balanced approach often combines some cash reserves with diversified, relatively cautious investments, rather than committing entirely to one position - whether “all cash” or “fully invested.”
- Question 4 Could central banks still prevent a catastrophic crash?
Answer 4 They retain powerful tools, including rate cuts, emergency lending, quantitative easing and regulatory intervention. The difficulty is that deploying them aggressively could reignite inflation or inflate fresh bubbles. They may therefore intervene later and more carefully than in earlier crises, which is precisely what concerns some analysts.
- Question 5 What’s one practical step I can take this week to feel less exposed?
Answer 5 Begin by putting your true financial position on one page: income, essential spending, debts and their interest rates, plus the actual locations of your savings and investments. This basic exercise often exposes one or two obvious weaknesses - such as a high-interest loan or a concentrated holding - which you can begin moving in a safer direction immediately.
Comments
No comments yet. Be the first to comment!
Leave a Comment