
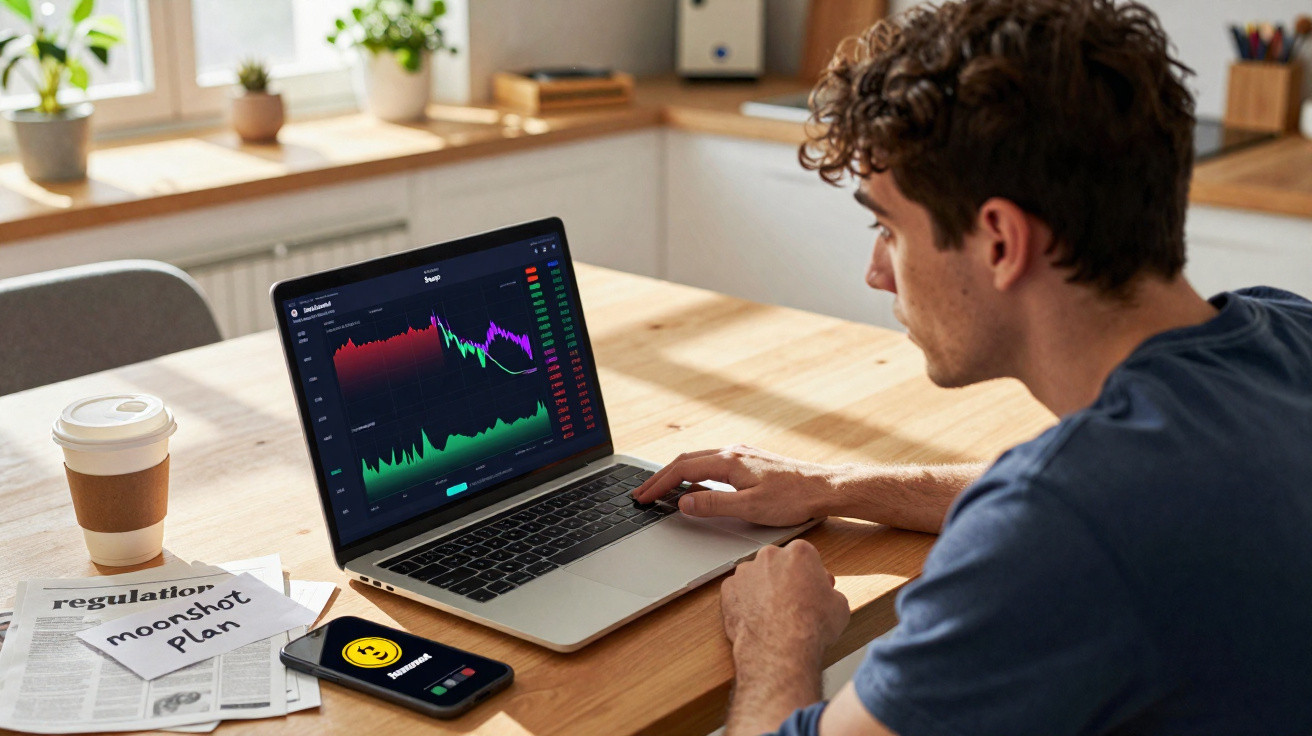
An everyday investor, a dazzling “miracle token”, and one mouse click that temporarily transformed hundreds into millions before the truth struck.
The dramatic surge, followed by the immediate disappearance of those notional profits, did not merely damage one man’s finances. It reignited a bitter debate over who should be held responsible when an implausibly lucrative crypto proposition collapses: the punter pursuing transformative returns, the people behind obscure tokens, or regulators who appear only once the damage is done.
The moment a hobby trader became a “multi-millionaire”
The individual at the heart of the episode was neither a hedge fund executive nor a crypto whale. He was a small-scale retail investor who had been experimenting with volatile digital currencies from his laptop after work. Drawn in by social-media discussion of a new “miracle” token, he exchanged a modest amount of money for a little-known project promoted as the next major opportunity.
Nothing changed for several days. Then its chart shot upwards. The value displayed in his wallet began rising so rapidly that he initially thought the software had malfunctioned. When he refreshed the page once more, the balance showed an amount capable of changing his life. At least on paper, he had enough to leave his job, clear his debts and purchase a house outright.
His holdings ballooned from a few hundred dollars to several million – at least according to the token’s on-screen price.
He later said that his hands trembled as he looked at the figure. The miracle token appeared to have achieved the impossible. He believed he simply needed to click “sell”.
The click that changed everything
This was the point at which the dream encountered the reality of blockchain trading. When he attempted to withdraw his gains, he found major restrictions. The trading pair was shallow, liquidity was scarce, and each effort to sell a substantial share of his holding drove the price down sharply.
More troublingly, on-chain data soon indicated that the price spike had almost no real depth. Huge returns were being displayed on the basis of very small transactions. The token’s market value had been grossly overstated by the way its liquidity pool was structured. His wallet suggested millions, but the actual funds available to buyers and sellers were tiny.
As soon as he eventually clicked to sell part of his tokens, the outcome was severe. The price crashed, cutting down his paper wealth within seconds. The figure that had made him rich on screen disappeared almost as quickly as it had emerged.
The one click that was supposed to lock in a fortune instead revealed that the fortune had never truly existed.
He was left with a reduced profit, then hardly any profit whatsoever, alongside a profound feeling of betrayal.
Was it a bug, a feature, or a setup?
Once his account circulated through crypto forums and mainstream media, blame was swiftly assigned. Some traders said the project had been an obvious trap from the outset, based on a smart-contract structure that enabled price manipulation despite minimal genuine liquidity.
The token’s promoters rejected that characterisation. They maintained that the code was public, the dangers of illiquid markets were apparent, and nobody had been promised they could cash out at headline prices. Crypto, they reminded observers, is a buyer-beware environment.
The design of the token’s trading pool proved crucial. With automated market makers, prices shift according to the proportion of assets held in the pool. Where liquidity is exceptionally low, even modest purchases can send prices soaring, creating the appearance of extraordinary wealth for early holders. However, when those holders seek to sell, the same calculation drives prices down.
The ingredients behind the blow-up
- A tiny liquidity pool that enabled dramatic price movements
- Social-media hype that attracted retail speculators at a late stage
- Complicated tokenomics that few investors properly understood
- No obvious way for large holders to exit without collapsing the price
On the face of it, the token seemed to be an overnight triumph. Beneath that appearance, it was a precarious system in which almost no one could realise the theoretical gains at scale.
Greed, responsibility and the harsh physics of markets
The investor became a focal point for opposing views. His supporters regarded him as the victim of predatory design and polished promotion. His critics presented another interpretation: he was a gambler pursuing implausible returns while disregarding basic warnings on liquidity and slippage.
The story cut straight to a thorny question: at what point does ambition become greed, and does greed cancel sympathy?
In markets, greed seldom appears to be greed at the time. Instead, it takes the form of “one more win”, “just a little bit more”, “I’ll sell when it doubles again”. Sensible restraint weakens when the figures on a screen move so far beyond someone’s previous experience of life that they no longer seem real.
The investor delayed at precisely the wrong moment. Rather than selling in stages as the balance increased, he kept watching and refreshing the page in anticipation of still higher prices. When he seriously tried to leave the position, the exit was already half closed.
Where were the regulators?
The incident also intensified the argument around regulation. Critics of crypto’s lightly controlled environment argued that episodes like this demonstrate why stricter rules are overdue. They highlighted conduct that would not be accepted in conventional finance: tokens with virtually no disclosure, liquidity pools managed by anonymous teams, and aggressive advertising targeted at inexperienced investors.
Regulators have begun taking notice, although their progress remains slow. One difficulty is the cross-border character of decentralised tokens. A project can be launched from anywhere, trade on decentralised exchanges and attract users worldwide before an authority becomes aware of it.
| Traditional finance | Typical crypto token launch |
|---|---|
| Heavily regulated exchanges and prospectuses | Anonymous teams, informal “whitepapers” |
| Liquidity and market-making monitored | Liquidity pools created by project or users, often tiny |
| Investor protections and complaints routes | Limited recourse; smart contract is the final arbiter |
For many officials, the “miracle” token case serves as a warning: retail investors can lose everything in seconds through mechanisms they scarcely understand, long before a legal case can be assembled.
Lessons for small investors chasing big gains
Professionals who examined the episode point to a well-known checklist. None of it is exciting. Yet all of it is commonly overlooked once greed and FOMO take hold.
- Check liquidity as well as price. A token with a small pool can display fantasy valuations.
- Try small withdrawals first. If you cannot cash out a few hundred, you will not cash out millions.
- Examine smart-contract audits where they exist, and approach unaudited code cautiously.
- Take profits in stages rather than waiting for a perfect peak that never comes.
A further practical measure is to understand slippage. Slippage is the gap between the price anticipated and the price received when a trade is completed. In shallow markets, large orders can shift prices dramatically, reducing an apparent fortune to a fraction of its headline value the instant you click “confirm”.
What this means for future “miracle” tokens
New meme coins and miracle tokens will continue to emerge. Some will truly benefit early adopters, while many will become cautionary stories. For regulators, every collapse increases pressure to establish a clearer framework without choking innovation. For investors, each collapse provides a harsh lesson that they neither sought nor can afford to ignore.
One helpful mental exercise is to consider the exit before entering a trade. If a token you purchased displayed £1 million on screen tomorrow, who would really be available to buy it from you at that price? How quickly could you sell your position without damaging the market? If those questions cannot be answered, the displayed figure may be nearer to fantasy than a bank balance.
Crypto risk rarely vanishes; it simply takes a different form. At times, it resembles volatility. At others, it looks like a hack. In this “miracle” token case, it posed as a once-in-a-lifetime chance, exposing its true price only when selling began and one investor’s dream disappeared with a single click.
Comments
No comments yet. Be the first to comment!
Leave a Comment