
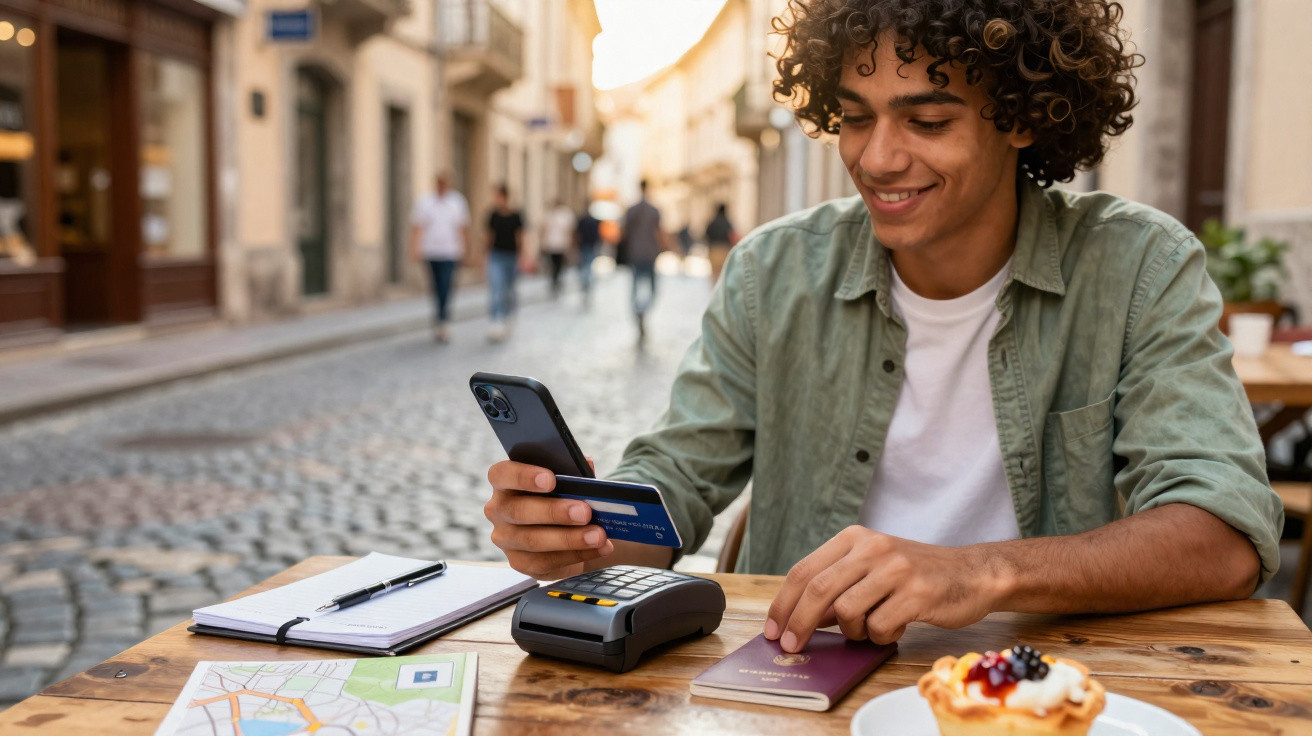
I slipped away from a work conference for ten peaceful minutes, bought a pastel de nata as wide as a saucer, and confidently tapped my UK travel credit card. The terminal chirped, hesitated, then displayed DECLINED as though I had attempted to purchase a yacht. The queue behind me shuffled, somebody coughed, and the barista gave me the kindly expression normally saved for bewildered visitors. I had cash, yet using it felt like presenting a paper ticket at a contactless barrier.
The incident played on my mind for the rest of the day. Why had my card stopped working overseas when I had explicitly told my bank I was travelling? I later discovered the reason - along with a straightforward solution I now rely on. It all begins with one small flashing notification.
The pastry that bruised my pride
A declined card abroad creates its own peculiar silence. The terminal gives a faint, regretful beep and everyone lifts their eyes from their phones. Portuguese sunlight poured through the glass, scooters buzzed outside, and I suddenly felt intensely British and very red-faced. I inserted the chip once more. The machine gave me the same blank refusal, while the barista offered the same courteous shake of the head.
Two alerts then appeared on my phone, each urgent in its own way. My bank wanted me to verify a suspicious payment, while my roaming provider informed me that my data allowance had run out. It was a perfect storm. I could not tap “Yes, that was me” because the app repeatedly timed out, in the uncomfortable manner of an app that seems embarrassed on your behalf. I paid for the pastry with cash and left eating quickly, as if haste might erase the humiliation.
My ears were burning when the cashier said, “Again?”
What your bank sees behind the beep
Once back at the hotel, the app revealed what the café terminal had not: my card was not faulty, my account profile had not been blocked, and I had plenty of available limit. The transaction had been marked as unusual because of my normal spending pattern and current location. The bank needed an in-app confirmation through Strong Customer Authentication, the unglamorous but important EU/UK requirement designed to prevent fraud - and which can occasionally prevent cake instead. With roaming at something like 2G speed and the Wi-Fi password scribbled on a napkin, I could not confirm it quickly enough.
There is another, less obvious complication. During busy periods, or until close of business, some smaller retailers operate terminals “offline”. You tap your card, the terminal appears to accept it, and the proper authorisation is processed later. If your bank has not recently recorded European spending from you, or if your card blocks magstripe fallback, you can run into the limits of the system. It is not personal, although it certainly feels that way.
International usage notifications: the quiet hero
This is the solution I wish I had found earlier. I enabled every international usage notification available through my bank. I did not only activate spending alerts that arrive afterwards; I also enabled real-time payment approval requests and confirmation alerts for card use abroad. The following day, I returned to the same café and ordered the same thing. Then came a minor miracle: my phone vibrated, a push alert asked “Is this you in Lisbon?”, and I pressed a large green “Yes”. Tap. Latte. Calm.
Notifications may sound insignificant until they are needed to rescue a moment that is slipping away. Ten seconds and two bars of mobile signal can separate a declined card from an effortless payment. Being able to see and approve a request in that brief window is more than convenient: it preserves your dignity. Rather than waiting for a machine to pass judgement, you are part of the process.
Push notifications are more than a useful extra; they are your pass to buy coffee without stress.
Approve rather than apologise
Most UK banks now provide some version of travel-friendly alerts. Challenger banks such as Monzo and Starling send immediate spending notifications as standard, while major high-street banks are increasingly offering “approve in app” prompts when a transaction appears unusual. Some banks no longer ask customers to submit a travel notice because their systems automatically monitor overseas activity. What matters is being able to approve a payment without delay, rather than whether the bank believes you are in Spain or Sunderland.
When a terminal tells you to insert your card rather than tap it, follow the instruction. If it requests a signature, there is no need to panic: certain European systems still use signatures when online checks are unreliable. The essential thing is to have a functioning connection between your phone and your banking app, so that the approval arrives before it expires. Everything else is simply choreography.
Preparing your card for overseas use
A short session in your banking app can spare you a week of sweaty palms. I enabled “international usage alerts”, “approve transactions” prompts and, most importantly, “new merchant” notifications. Where my bank permitted it, I added a travel note, despite many banks now saying it is unnecessary. I also created daily spending alerts, so I would spot it if a cloned card attempted to buy a motorbike at 3am.
I reviewed my card controls too. Certain banks allow you to turn magstripe use on or off, choose contactless limits, or lock online transactions unless they are required. While travelling, I leave online payments locked and only enable them when I need to pay for a train ticket online or top up an eSIM. It turns your phone into a remote control for your wallet, which is surprisingly reassuring.
Arrange roaming and an alternative payment-approval method before you leave the UK.
Five-minute settings to switch on
Enable push notifications for every payment, so that you can see exactly what the terminal sees. Turn on “approve in app” or “challenge” requests if your bank provides them. Add a local telephone number or email address as a backup, since some confirmations still arrive by SMS and not every roaming plan is generous. If biometric approval is available, configure it: little is faster than a face scan while a waiter waits patiently.
If your bank still lets you add a travel notice, do so, as it may ease the first day of your trip. If it does not, there is no problem. Check in the app that overseas card use is allowed and that any “location-based security” setting is enabled for your phone. That helps your bank recognise that your mobile has travelled to Lisbon along with your card.
The SCA problem: app confirmation without a signal
Here is the part the glossy travel brochures omit: SCA exists to protect us, but it can also leave you stranded in a doorway holding a bag of mandarins. Approvals expire. Hotel Wi-Fi portals can sign you out halfway through payment. Underground stations swallow your signal precisely when your bank asks “Was this you?” If your sole approval method depends on your UK SIM and you have disabled data to save money, you have created a distinctly British predicament.
My answer was a low-cost eSIM with a small amount of data, enough to keep messages coming through. It meant the bank’s push notification could reach me in a lift or inside a taxi tunnel. When there was no coverage at all, I asked the barista or cashier to process the transaction using chip and PIN rather than contactless. That often sends the payment through a different route and can sometimes avoid the challenge. It is not graceful, but it can work.
There is one further protection worth taking: note down your bank’s overseas telephone number and save it both in your notes app and in an email to yourself. If every digital process fails, you can call and request a manual unfreeze. It takes longer, but it is preferable to standing at a till practising an apology in two languages.
Hotels, car hire and offline terminals that challenge cards
Hotel and car-hire desks bring their own particular pressure. They do not merely take payment; they pre-authorise a substantial deposit, often by running your card through a terminal that seems older than the receptionist. Some terminals operate offline and transmit the approval later, which can be troublesome for banks that are particularly alert to fraud. If your app cannot authorise a pre-authorisation immediately, the clerk is left with a non-committal machine and may reach for the photocopier.
Before checking in, I now open my banking app and leave it running. I tell the clerk that a pre-authorisation will appear and that I will approve an app notification. It conveys confidence and gives you a few valuable seconds. If the pre-authorisation still does not go through, I ask them to use another route - some systems can process it online - or I use another card that is less eager to trigger approval checks.
Petrol stations can cause comparable confusion. Many use unattended terminals overnight, and your card may receive either a small test charge or a large temporary hold. Alerts are useful here as well: you can see the hold immediately, understand the amount, and contact the bank if it seems suspicious. Information is what turns panic into patience.
Small rules that can rescue the day
There is one essential rule: whenever a terminal asks “Pay in pounds or euros?”, always select the local currency. Choosing pounds means accepting dynamic currency conversion - a polite term for letting the retailer set the exchange rate instead of your card network. I have seen mark-ups that would embarrass a hedge fund. Your notifications will still show the charge, but selecting the wrong option means the cost has already been incurred.
Contactless limits differ between countries. In certain places, you may need to insert your card for even a modest purchase if you have tapped several times that day. Do not resist the routine. Insert the card, enter your PIN, approve the push request if necessary, and continue with your day. If your card uses an offline PIN and the terminal is offline, you will appreciate having practised entering it without doubting yourself.
Do not allow a terminal to pressure you into paying in pounds while abroad.
The human side: fewer worries, more wandering
We have all experienced a moment when a small piece of plastic appears to dictate the mood of an entire day. The purpose of a holiday - including a work trip - is to feel slightly freer, to allow a city to lead you rather than the reverse. For me, notifications did more than solve payment problems; they took the sharpness out of travelling. I knew that if anything unusual happened, I would know before the receipt emerged. That is a subtle kind of freedom.
In reality, nobody does this every day. We do not run pre-flight checks on our banking apps or practise payment mishaps in front of the mirror. Yet the five minutes I spent enabling international alerts did more for my travel peace of mind than any packing cube or power adapter. It will not prevent every problem, but it can prevent the ones that hurt most.
The small checklist I now follow
Before flying, I confirm that roaming is active and open my banking app. If international alerts have reset since my last trip, I enable them again, then check that “approve in app” is permitted on that device. If the bank provides a travel note option, I add one as an extra precaution; if not, I simply carry on. I then purchase a basic eSIM, so approvals do not become trapped in limbo while I am on a tram.
I take a second card from a different bank, preferably one with a different temperament - if one card is cautious, the other may be more relaxed. One stays in my wallet, while the other goes in the hotel safe or another pocket. When I know I will be checking into a hotel, I open the app five minutes before reaching the reception desk, because timing is important. Nobody needs to see you lose signal beneath a chandelier.
The first time a waiter smiles while your phone buzzes and your card goes through smoothly, you will feel the tension lift from your shoulders. That finally happened to me in the same café two days later. The pastel was sweeter, and the terminal’s beep was almost welcoming. And yes, I paid in euros, because I had learnt my lesson. I still remember that first declined payment, not with irritation but with gratitude for the small alert that transformed the feeling of a city street.
Comments
No comments yet. Be the first to comment!
Leave a Comment