
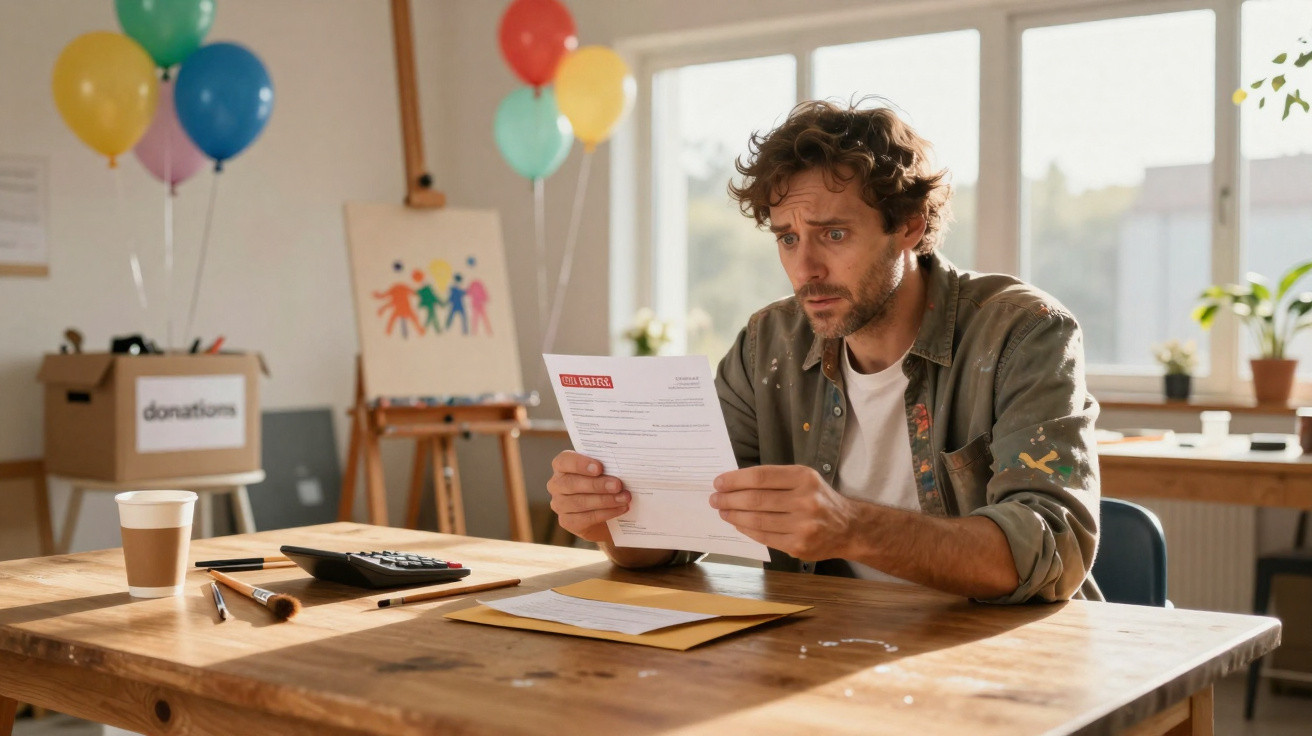
The invitation seemed innocent enough: a handwritten message from next door, a charity leaflet, and the lure of home-baked cakes with acoustic Ed Sheeran covers.
It was meant to be a low-key Sunday fundraiser in an artist’s studio, with fairy lights looped around easels and children weaving between canvases. There were no ticket sales, no paid drinks and no obvious “business” involved. It was simply a kind gesture, a borrowed venue and the gentle buzz of people doing something that felt… worthwhile.
Several months later, that same painter was sitting at his kitchen table, looking at a brown envelope from HMRC. Inside was a five-figure demand. The cause? The friendly charity evening held in his studio had been treated as taxable business income. The kitchen suddenly seemed to close in around him. The scent of turpentine made matters no better.
A court-hearing date appeared in one corner of the letter. One sentence, in particular, would not leave his mind.
They considered it part of his professional activity.
When a good deed appears to be business to the taxman
The case concerns a London painter, recognised for his understated landscapes and an equally unobtrusive life. He rents a small studio in a converted brick warehouse, where the windows shake in their frames and the kettle always takes too long to boil. One day, his upstairs neighbour, who helps run a small local charity, calls by. The charity needs somewhere to hold an evening fundraiser because its usual hall is unavailable. Could it use his studio on this one occasion?
Without hesitation, he agrees. There is no formal agreement and no rent to pay, only a text message: “Of course, happy to help.”
About 60 people fill the studio on the evening itself. Some put banknotes in collection jars, while others use QR codes to donate straight to the charity. Standing awkwardly in one corner with a plastic cup of lukewarm white wine, the painter watches unfamiliar faces admire his unfinished canvases. He receives no payment. His name is not on the poster, and he makes no appearance on stage. He heads home tired but quietly pleased with himself. One person did ask for his Instagram, however.
The charity later submits its annual report. Event photographs clearly show the artist’s studio, while a blog post refers to “a generous local artist who opened his professional space free of charge”. Software picks up the address, and the tax authority connects the information. From its perspective, this is no longer merely a room containing paintings. It is a business asset used in a way that raises the painter’s professional profile. At that point, the narrative changes.
Months afterwards, the tax demand arrives. Its explanation is starkly impersonal. Because he allowed his registered studio to be used for an event connected with his artistic identity, the painter is deemed to have received a “non-monetary benefit” related to his professional activity. This includes networking opportunities, brand exposure and possible future commissions. In tax terminology, that is “economic value”. The authority argues that economic value amounts to taxable income-even though no money reached his hands that evening. The calculated “benefit in kind” is based on what the charity would have paid to hire the venue at market rate.
The painter disputes the demand in court, maintaining that he did a personal favour rather than making a commercial choice. The judge hears the case, reviews the emails and looks at photographs of fairy lights draped over tripods. The ruling follows: the studio is a professional asset, the event improved his business profile and the benefit has an assessable value. The tax bill remains in place. A single generous evening is recast as part of his trade.
How to stop generosity becoming taxable “income”
Tax specialists say the painter’s error started well before the first guest entered the studio. Where a home, spare room or workshop is registered for business use, any external activity involving that space may invite scrutiny. The clearest way to reduce the exposure is surprisingly straightforward: make a firm distinction between your personal self and your professional identity on paper. In practice, this means recording when a space is being used for business and when it is entirely private.
For a charity event, this could mean preparing a brief note confirming that the space is being lent personally, outside the scope of your trade, with no promotional or commercial connection. That may sound overly formal for an act intended to be generous. Nevertheless, that one page may provide the narrow dividing line between a “friendly favour” and the “taxable use of a professional asset”.
The next important step is to minimise the event’s connection to your work identity. Do not put up prominent logo displays, leave piles of business cards at the entrance or introduce yourself as “the artist” or “the designer”. The more the occasion resembles a showcase, the easier it is for a tax inspector to argue that it created a professional advantage. As one tax adviser put it, if the very same event could take place in a village hall with nothing changing, you are in a safer position. The studio should serve as scenery, rather than as a marketing device.
It is also sensible to retain unambiguous evidence that you received neither payment nor rent. This may include emails from the charity confirming “no fee”, a zero-value invoice if you wish to be especially precise, and a short file note explaining why the space was lent. Such administration can feel excessive for a cake sale accompanied by a guitar. But if software somewhere decides that your kind act bears a strong resemblance to business, those few written lines may become extremely important.
There is a less comfortable point behind this case. Contemporary tax systems find blurred boundaries difficult: a studio doubling as a sitting room, events that are both social and professional, or a favour that also generates free publicity. Courts often return to one simple question: would this event have been held in that space if you were not operating a business there? If the truthful answer is no, the position may be risky. That does not mean you must always refuse. It means agreeing with a full understanding of the implications.
From a human perspective, it seems severe. The painter charged no rent, sought no commissions and did not even attach price labels to his work. However, the law pays limited attention to good intentions. It responds to structures: a registered business address, patterns of use and visible branding. As a result, one quiet Sunday evening turns into a test case, and creatives everywhere begin wondering what might be hidden within their own generous gestures.
Practical steps for artists, freelancers and generous neighbours
The strongest protective measure is to define the purpose of your spaces. Where a studio is registered as a business premises, keep a straightforward record of when and why it is used for other purposes. If a neighbour requests the venue for a charity event, reply in writing from your personal email account rather than your business address. Describe it as a private gesture: “I’m happy to lend my space as a friend, not as part of my work.” Include a sentence stating that there is no fee, sponsorship or promotion. It may sound a little formal, but it establishes the framework for the whole arrangement.
Where possible, remove clear signs of business from the room for the evening: face paintings towards the wall, cover logos and take away price lists. This is not about concealing your occupation; it is about ensuring the charity, rather than your commercial activity in the space, remains the focus. Think of it as putting the venue in plain clothes for the night.
Then there is the concern people often keep to themselves: social-media sharing. An Instagram story saying “So proud to host this beautiful event in my studio tonight” directly connects the charity evening to your personal brand. A tax inspector might later cite that as proof of a professional benefit. A more neutral caption-“Neighbourhood fundraiser tonight, had the chance to help with the venue”-creates greater separation. Let us be honest: hardly anyone thinks this way every day, but one screenshot too many can be enough to trigger charges.
If you already use a mixed-purpose space-such as a home office, or a sitting room that also functions as a workshop-consult a tax adviser before you begin lending it out. This need not be an ongoing arrangement. One conversation can be enough to map out the boundaries. Many countries distinguish between occasional, non-commercial lending and regular or advertised events. Understanding exactly where that boundary lies in your circumstances makes it easier to help when your community needs you, without feeling anxious whenever a brown envelope arrives.
“Generosity isn’t tax-free by default,” says one accountant who now uses the painter’s case in client workshops. “The system doesn’t punish kindness on purpose. It just doesn’t recognise it as a separate category. So you have to label your kindness before someone else labels it for you.”
Before giving someone the keys for a fundraiser, consider these practical questions:
- Is my space formally registered, or claimed in any tax return, as business premises?
- Will my name, logo or work feature on event posters, tickets or online promotion?
- Could the event reasonably be held in another neutral venue without losing its purpose?
- Will I receive anything in exchange-contacts, access to a mailing list, social-media promotion or “visibility”?
- Do I have a brief written record describing this as a personal, non-commercial loan of the space?
On an emotional level, the painter’s experience strikes a chord. We have all had those moments when we say “yes” too quickly because refusing seems mean-spirited. The legal system does not take account of that discomfort. Your boundaries can, though. Saying, “I’d love to help, but I need to keep my studio separate from my work on paper-can we list the venue just as ‘local space’?” is not selfish. It is a way of stopping a good deed from causing financial trouble years later.
The narrow divide between kindness and “economic value”
What stays with you after this case is not simply the apparent unfairness of the tax bill. It is the sense that private and professional lives are increasingly overlapping in ways the law has not fully addressed. A studio can now be a showroom, a backdrop for reels, a co-working venue and a community hub. Whenever it is full of people, someone may claim that value is being created. Once value is identified, the tax system begins to take an interest. That is its function, even when it feels insensitive.
The more useful question, then, is not “How do I avoid the taxman?” but “How do I describe my spaces and gestures clearly before someone else describes them for me?”
The painter in this account lost his challenge, and the bill was painful. His fight did have another consequence, though: it prompted conversations in studios, cafés and shared offices about what truly counts as income. People began asking for written agreements where a nod and a smile had once been enough. Some started marking “business events” and “neighbourhood gatherings” separately in their diaries. Others quietly stopped agreeing to every request to use their venue. None of this is particularly romantic, but it can feel like self-protection.
There is no single tidy rule for every circumstance. A yoga instructor lending her home for a charity meditation session, a photographer offering a free community portrait day or a coder opening an office for a school workshop all face situations with their own nuances. Still, the painter’s experience offers a simple test: if the event makes your premises appear more like a business in public, treat it accordingly, even where no payment is made. Either accept this and prepare for the tax risk, or reshape the arrangement so that it genuinely belongs in your private life.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Studio use reclassified | The court found that lending the studio was a professional use that created an economic benefit. | It shows that a simple favour may be viewed as income by the tax authority. |
| Separate private and professional activity | Use written documents, avoid publicity and limit visible “business” signs during the event. | These are practical measures to protect good deeds from being reclassified for tax purposes. |
| Assess the non-monetary “benefit” | Visibility, networking and indirect promotion may be valued as income. | It helps identify when generosity begins to look too much like marketing. |
FAQ
- Can lending my studio or office for free really be taxed as income? Yes. If the space is a business asset and the event is linked to your professional identity or visibility, authorities may treat the “benefit” as taxable, even without direct payment.
- Does this only affect artists and creatives? No. It can affect anyone using a registered business space: freelancers, consultants, therapists, designers and even people claiming a home-office deduction.
- How can I reduce the risk when helping a neighbour or charity? Use written wording that presents the loan as personal, avoid overt promotion of your business and retain records confirming that no money or commercial exchange took place.
- Is social media promotion of the event a problem? It can be. Posts presenting the event as part of your brand or professional activity may later be used to argue that you gained business value from it.
- Should I stop saying yes to charity events in my space? Not necessarily. Consider the structure, wording and boundaries, and seek one-off advice if your space is heavily connected to your business on paper.
Comments
No comments yet. Be the first to comment!
Leave a Comment