
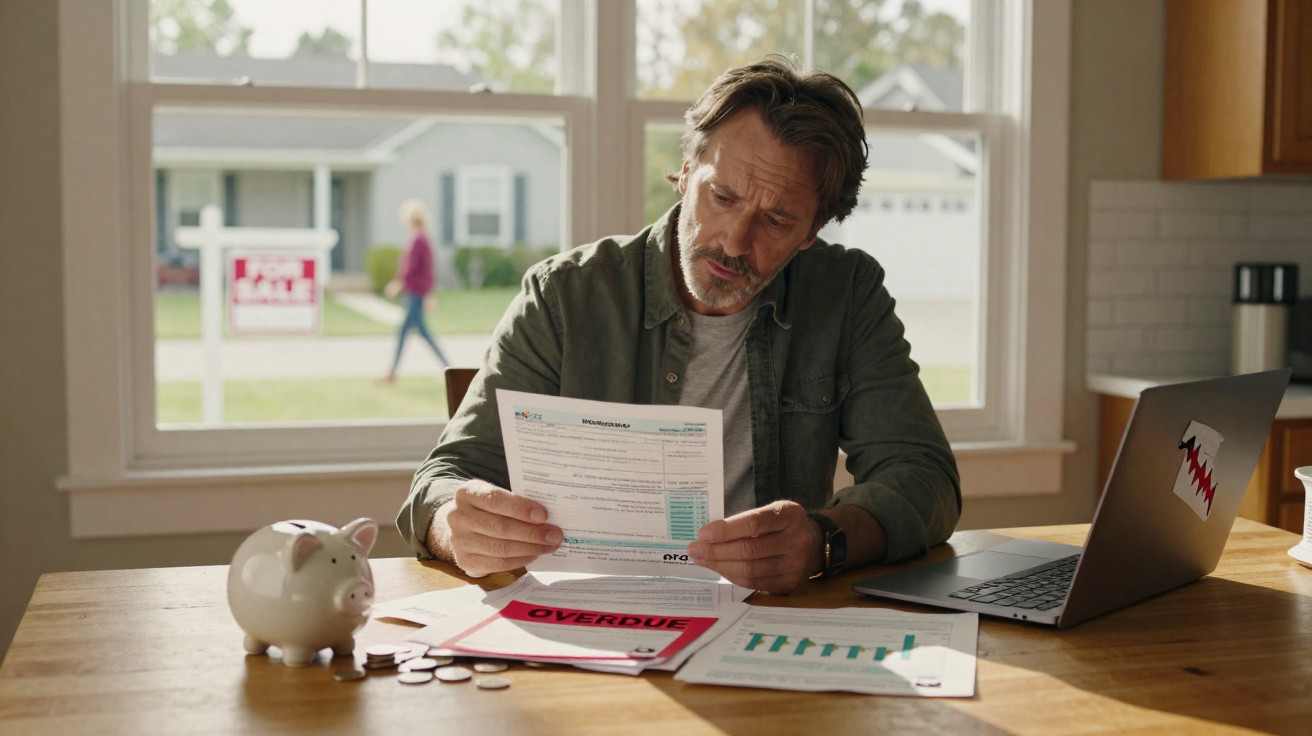
For years, homeowners were assured that they could rest easy while their homes steadily generated wealth in the background.
A rise in forced sales, more expensive borrowing and unwelcome tax shocks is now jolting people awake. The property dream looks far less secure than estate agents’ polished brochures once implied.
The myth that homes only go up
Across the UK, US and other wealthy countries, personal finance has been shaped by one dominant belief for at least two generations: buy a home as soon as possible, push your budget to its limit, and allow rising prices to do the rest.
Parents passed on the message, banks reinforced it, and whole television formats were founded on the idea that the property ladder moves in only one direction.
“Property is always safe” became a kind of unofficial pension plan, especially for people locked out of generous workplace schemes.
This conviction relies on three unspoken assumptions:
- Interest rates remain low or decline over time
- There is always a line of buyers both willing and able to pay more
- Governments continue to favour property ownership with tax reliefs
All three assumptions are now being challenged simultaneously.
Forced sales are back, and they look different this time
Forced sales once brought to mind the 2008 crisis, with US suburbs full of foreclosure notices and deserted new-build developments.
The current version is usually less visible and, in certain cases, more distressing.
When a “manageable” mortgage stops being manageable
When central banks raised interest rates to combat inflation, homeowners whose ultra-low fixed-rate deals expired were abruptly confronted with the consequences.
Their monthly repayments rose by hundreds, and sometimes thousands, of pounds or dollars.
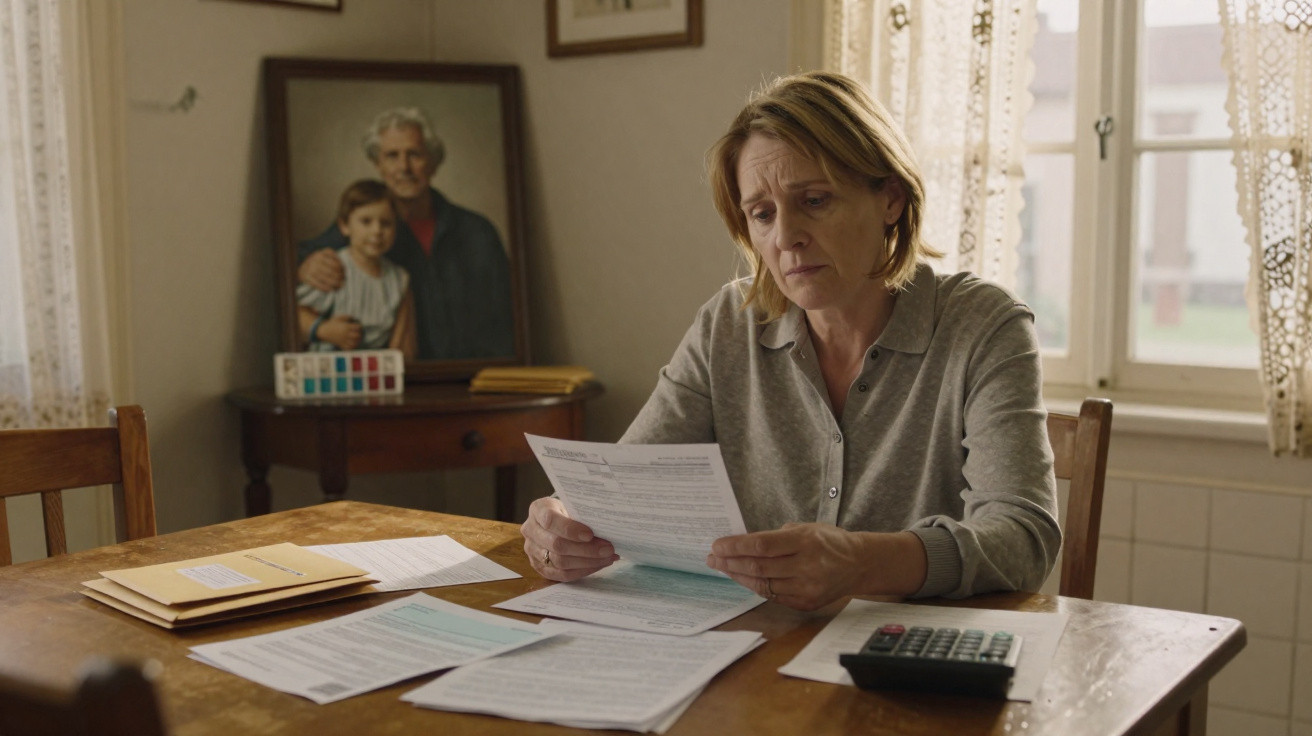
Many owners have not formally defaulted, yet their household finances have buckled.
Estate agents in major cities are reporting an increasing number of “must-sell” listings: homes offered for sale not because their owners want to move up, but because they can no longer sustain the borrowing.
People are discovering that you don’t need a crash in prices to be forced out of your home; you just need a crash in your monthly cash flow.
In some markets, the pattern appears through:
- Unassuming “for sale” signs remaining up for months
- Price reductions that become clear only when bids land far below the asking price
- An increase in discreet sales by landlords disposing of unprofitable rentals
The buyer pool is shrinking just as supply rises
In property, values depend less on what a home is theoretically “worth” than on the number of people who can genuinely afford it on a particular day.
Tighter credit and exhausted savings
During the pandemic, exceptionally low interest rates and stimulus payments drew many first-time buyers into the market.
That confidence has since faded.
Lenders are demanding bigger deposits and applying tougher income assessments, while higher food and energy costs have depleted savings buffers.
Many people keen to purchase remain stuck in rented accommodation or with relatives, observing asking prices like spectators at a match in which they cannot participate.
Meanwhile, listings are increasing as older owners move to smaller homes, second-home owners reconsider their arrangements, and landlords withdraw from sectors affected by tighter regulations.
| Trend | Effect on market |
|---|---|
| Higher interest rates | Reduces how much buyers can borrow |
| Stricter lending standards | Keeps marginal buyers out of the market |
| Ageing owner population | Gradual increase in homes for sale |
| Landlords exiting | More listings, especially in city centres |
When the pool of buyers contracts, even a limited increase in forced or motivated sales can shift negotiating power from sellers to buyers.
The tax bills no one talked about at the open house
Homeowners who anticipated nothing but celebratory moments from rising property values are instead encountering the tax authorities.
Capital gains and “paper” profits
For owners of second homes or rental properties, the price boom carried a painful downside.
Many governments have tightened property tax rules, cut allowances or made costs more difficult to offset.
Some landlords are facing substantial capital gains tax liabilities when selling, even where much of the increase merely followed inflation.
On paper, they are richer; in practice, they are staring at five- or six-figure cheques to the tax authorities.
In areas with strong demand, even families in relatively modest homes may be moved into higher local property tax bands after local valuations rise.
What once seemed a comfortable long-term investment can therefore become a recurring strain on the annual household budget.
Economists, estate agents and landlords blame each other
The dispute about who “killed” the dream of home ownership is becoming louder than any auction room.
Economists: policy and cheap money did the damage
Many academic economists place responsibility with central banks and governments.
Years of exceptionally low rates, alongside housing shortages and planning constraints, drove prices higher.
Tax advantages for home ownership and buy-to-let investment created further demand without a corresponding increase in supply.
From this perspective, property turned into a leveraged wager on future interest rates rather than straightforward shelter.
Estate agents: politicians and NIMBYs locked out a generation
Estate agents and brokers offer another explanation.
They say restrictive planning policy, local resistance to development and slow infrastructure schemes have constrained new supply for decades.
In many cities, existing homes can change hands repeatedly, but constructing new ones remains slow, costly and risky.
Agents maintain that they merely connect buyers with sellers in a market politicians have made artificially constrained.
Landlords: changing rules made renting unworkable
Small landlords, for their part, feel under attack from both directions.
They are dealing with stricter rules, higher borrowing costs, and growing maintenance and insurance expenses.
At the same time, they are blamed for expensive rents and accused of preventing first-time buyers from entering the market.
The result is a growing number of “accidental” landlords selling up, reducing rental supply just as tenants feel most squeezed.
Every group presents a different account, but they share a central point: the old storyline that property always wins no longer matches reality.
Why “property is always safe” became so dangerous
The reassuring phrase obscured genuine risks that many households are now confronting in harsh daylight.
Concentration risk: all eggs in one roof
For the average middle-class household, its home is overwhelmingly its largest asset.
Its financial prospects are therefore bound to one market, in one area, frequently alongside substantial debt.
When local prices stagnate or decline just as an owner has to sell because of divorce, unemployment, illness or retirement, the consequences can be severe.
Liquidity risk: rich on paper, stuck in practice
Property may appear dependable and solid, but selling it takes time.
In a weak market, a house can take months to sell, while serious issues identified in a survey may deter prospective buyers.
That time lag is important when an owner urgently needs money.
The family home can be worth half a million on paper and still fail to pay a single urgent bill when timing goes wrong.
What homeowners and would-be buyers can actually do
No catchphrase can repair an unaffordable housing budget, although several practical checks may limit the harm.
Stress-testing your mortgage
A straightforward starting point is to carry out a personal stress test.
Consider what would happen to your monthly finances if:
- Your interest rate rises by 2–3 percentage points at the next renewal
- One household income vanishes for six months
- Local prices drop by 10–15% at precisely the point you need to sell
If these circumstances appear unmanageable, that is a warning sign rather than a forecast.
It could encourage earlier discussions about downsizing, refinancing or creating an emergency savings reserve.
Knowing the tax angles before you celebrate the gain
Second-home and rental-property owners need to understand how capital gains tax, local charges and changing deductions influence their actual returns.
This means maintaining accurate records of refurbishment costs, loan interest and service charges that could reduce the taxable gain.
Some owners may conclude that, once tax and costs are included, the alleged “goldmine” is simply a complex route to a modest, high-risk return.
Key terms worth unpacking
Negative equity occurs when the outstanding mortgage exceeds the property’s market value.
It can leave owners unable to sell unless they contribute cash themselves.
Loan-to-income ratio compares the amount borrowed with annual earnings.
High ratios increase risk when interest rates increase or employment becomes insecure.
Debt service refers to the proportion of income spent on mortgage repayments, property taxes and insurance.
Financial planners commonly identify a danger point when housing costs rise well beyond one third of take-home pay.
Scenarios that show how fast the story can change
Consider a couple who purchased a flat for £350,000 with a 10% deposit when rates stood at 1.5%.
Their monthly repayment seemed stretched but affordable.
Five years on, their fixed mortgage deal ends and the rate resets to 5%.
Their repayment rises by several hundred pounds each month, at the same time as childcare, food and energy bills increase.
The flat may theoretically be worth £380,000, but the higher outgoings do not make them meaningfully wealthier.
Should one partner lose their job, selling may become their sole realistic choice. They would then join the group of motivated sellers, adding further downward pressure to prices.
The position is much the same for a small landlord.
They bought a rental house expecting rising values and dependable rent increases.
Instead, repair costs, new safety requirements and higher rates absorb most of the rental income.
After tax, profits fall to almost nothing, while much of the substantial sale gain is ultimately redirected to the tax authorities.
The gloss disappears not in a dramatic collapse, but through a gradual squeeze that reveals how precarious the old narrative had always been.

Comments
No comments yet. Be the first to comment!
Leave a Comment