
You notice the smell of scorched toast before the red figures come into view.
For plenty of us, that is the opening scene: an unenthusiastic breakfast, temperamental Wi-Fi, and a market repeatedly proving that it has no interest in your plans. My first years of investing remind me of an unfortunate haircut - excessive confidence and far too little patience. A commentator tells you to buy one thing, a friend messages you about another, and you assemble a portfolio from scraps of gossip like a rumour-filled patchwork quilt. Then I came across the understated logic of Warren Buffett’s approach, and it was like throwing open a window in an airless room. It is neither quick nor showy. Yet it feels profoundly human - like advice from a beloved grandparent who has lived through several hard winters. The challenge is deciding which part deserves your trust first.
When I gave up chasing stock tips
I still remember the graph. It was one of those violent zig-zag lines that resembled a seismograph rather than an actual business. After buying a “hot” share on the strength of three messages and a late-night scroll, I spent the following week checking its price like a teenager refreshing a crush’s Instagram. There is a faint anxious click from the mouse when you constantly reload a quote. Before long, it felt like a metronome counting out poor choices.
Everything changed when I came across the old Buffett saying that drifts through investment forums like a murmur: “Be a business-picker, not a stock-picker.” The wording is simple, but the idea is deceptively deep. Shares are driven by moods; businesses are made up of kitchens, factories, delivery vans and customer routines. Once you quit asking, “Will this go up?” and begin asking, “Does this company actually make money in a way that lasts?”, the mist begins to clear.
Warren Buffett’s principle in plain English: buy the business, not the ticker
At the foundation of Buffett’s thinking is a simple idea: own enduring businesses with sound economics, and buy them at a price that leaves room for life’s unexpected events. He describes this as intrinsic value: the cash a company can generate over time. Not excitement, and not headlines. Cash. Ideally increasing, ideally reliable, and ideally produced without financial contortions or debt that keeps the lights on while robbing the future.
Buy wonderful businesses at fair prices. You could write that principle on a Post-it note and attach it to your monitor. The longer you consider it, the less appealing the chase becomes. When a business compounds value through a moat - a durable advantage that rivals cannot easily replicate - no miracle is required. What you need is time, plus the humility to let compounding take centre stage.
What a moat really looks like
A moat is not marketing jargon; it is a stubborn fact of commercial life. Consider pricing power: customers return even after a modest price rise. Consider habitual consumption, such as grabbing a red can at a petrol station without even looking at the alternatives. Then there are network effects, where a service gains usefulness as more people use it, leaving competitors feeling like deserted towns even when their technology is respectable.
Pricing power you can taste
Coca-Cola can increase the price of a cold bottle on a blistering day in Seville without anyone turning it into a news story. See’s Candies, one of Buffett’s favourites, made chocolate into a ritual. Apple created a garden where people enjoy staying, even if the rent rises slightly each year. None is flawless or unbeatable, but each is sticky. You can recognise that sort of moat in small everyday details - a hand reaching out, a saved payment card on a phone, or a logo occupying a corner of your life like a well-known chair.
Switching costs and the subtle lock-in
Brands are only part of the picture. There is also the hassle of leaving. Picture persuading a bank to remove its software and begin again from scratch. Picture a vast logistics business abandoning its data supplier. When change is painful, inertia becomes a moat. Some of Buffett’s largest successes have come from companies where the default response is “we’ll just renew.” That is not romance. It is a tollbooth.
Numbers that whisper rather than shout
Moats leave evidence in the figures, much as tracks appear in snow. You may find returns on capital remaining quietly strong year after year, profits that do not require an acrobatic explanation, and debt playing a supporting part rather than taking the lead role. You do not need a PhD or a bespoke spreadsheet to see it. Read ten years of numbers slowly and allow the pattern to speak for itself.
Return on capital tells you who is actually good at business. When one company makes £1 for every £10 tied up in the business, while another makes £3 from the same amount, the answer is already communicating with you. Look for managers who handle cash as though it belonged to a cautious neighbour, rather than scattering it in pursuit of fashion. Read their letters. Pay attention to clear language and the unglamorous satisfaction of repairing minor leaks before they sink major ships.
Price still matters: the margin of safety
Buffett is prepared to wait. He does not swing at every pitch. Instead, he lets most balls go by because he is not merely trying to get on base; he is waiting for one he can hit into the stands. That is what a margin of safety provides - protection against wet days, a missed forecast, a rogue chief executive or a storm that was not on the map. You can admire a business and still decide: not at this price.
Patience is not inactivity; it is the discipline to wait until reality reaches your price. Many legendary businesses passed Buffett by. He did not own every spectacular rocket, and he still slept well. Missing out hurts far less than paying too much. Eventually, the market will offer you a fair opportunity, provided you have the nerve to keep your hands in your pockets until then.
Management you would trust with your savings
Before trusting forecasts, Buffett trusts people. He favours owner-operators, or at least executives who speak as if the money were their own rather than Monopoly notes. Honest errors appeal to him more than creative accounting. When a chief executive cannot explain capital allocation without resorting to buzzwords, that tells you something. When they repurchase shares at sensible prices and stop when prices cease to be sensible, that tells you something else.
There is an old Berkshire tale about visiting firms with threadbare carpets but a sparkling culture. That kind of resourceful pride counts. Grand headquarters do not compound; discipline does. Observe what managers do when conditions become uneven - they will either defend the moat or sell the furniture for another quarter of applause.
Circle of competence: the strength of saying “no”
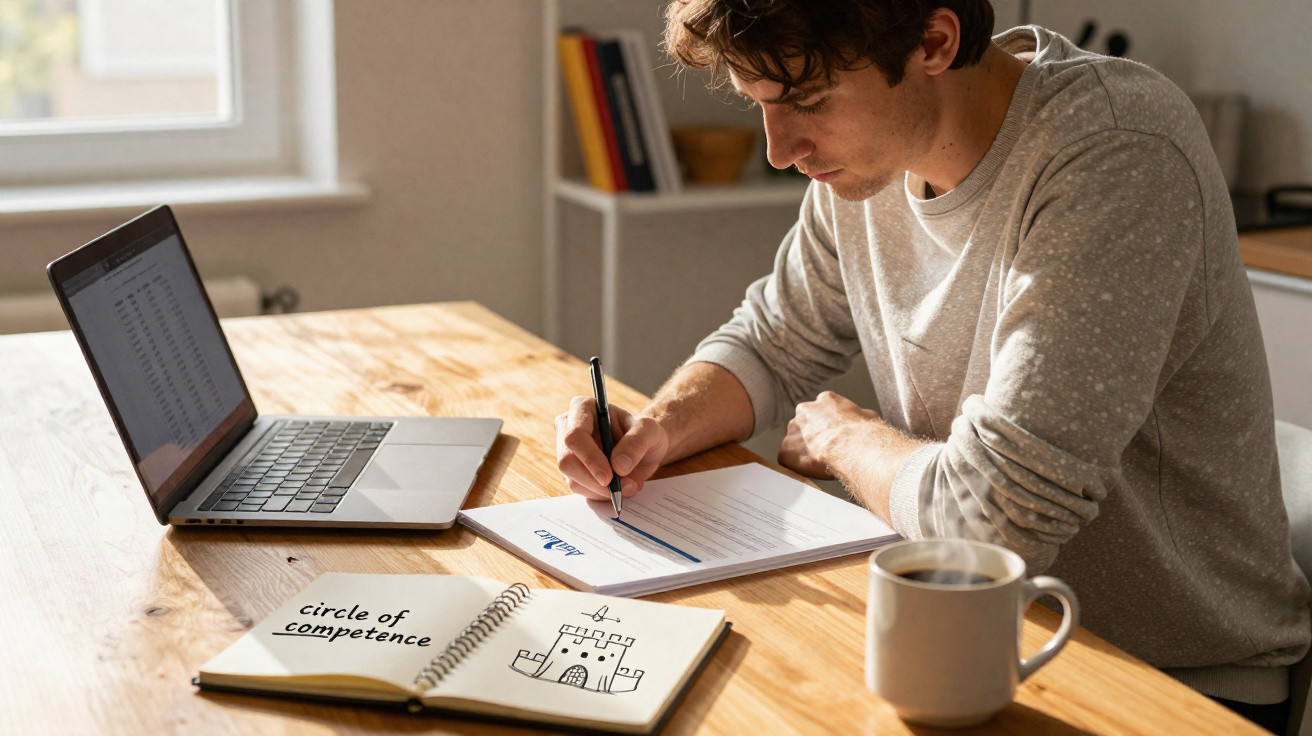
Everyone wants to seem intelligent. The market encourages you to act as though you understand more than you do. Buffett draws a circle around his expertise and remains inside it, even if the best party appears to be next door. We have all experienced a friend enthusing about a biotech that “can’t miss,” while something hopeful flips in the stomach. Then you imagine the laboratory and realise that you are speculating rather than investing.
If you can’t explain how it makes money, you probably shouldn’t own it. That one sentence has saved me more money than any tip ever has. Your circle can expand, and it should. But reading and time enlarge it, not FOMO at 11:47 pm. Saying “pass” is a superpower, even though it never appears on your statement.
A small ritual that changes everything
This is the practice that changed my behaviour. Each week, I choose one company and read its previous year’s report with a pencil rather than a highlighter. It creates a different frame of mind. I then write a single-page note covering what it sells, how it generates cash, where its moat lies, what could destroy it, and what price would make me brave. There is no elaborate model, only straightforward language that I would happily defend over a pint.
Honestly, nobody truly manages this every day. Life becomes noisy. Yet in the weeks when I make time, the market seems slower and more welcoming. The kettle whistles, the mug heats my hands, and the figures no longer yell. Instead, they whisper.
The calm portfolio: fewer trades, stronger conviction
Buffett’s investments can look dull until you calculate the results. He makes concentrated investments in robust franchises, followed by lengthy periods of doing nothing. That inactivity is not carelessness; it is conviction. Trading in and out for a few pence at a time is like uprooting a plant to inspect its roots. You will have soil on your shoes and little else to show for it.
There is a restrained pleasure in seeing a business you understand generate cash, increase its dividend, repurchase undervalued shares and widen its moat brick by brick. You do not need twenty-five exceptional ideas. Six to ten dependable ones can support a lifetime. The noise to listen for is not a bell at the peak; it is the quiet hum of compounding doing its unexciting, beautiful job.
The quiet thrill of compounding
Compounding does not announce itself; it gradually arrives. One year may appear insignificant. Three years resembles progress. Ten years can look like another world. The key is to endure the tedious stretches without abandoning your principles. The longer you hold an investment, the more your return is shaped by the business rather than the market’s voting machine.
Buffett does not pursue fireworks. He tends a wood-burning stove. Add dry logs - genuine profits reinvested intelligently - and the room becomes warm. Pursue the excitement of kerosene and you will singe your eyebrows. Consistent heat carries you through winter. No spreadsheet captures that feeling: the relief of not waking to chaos and the reassurance of a plan that does not demand heroics every Tuesday.
What this means for a UK investor today
Many moats can be found close to home. Diageo sells heritage and habits, rather than merely bottles. RELX controls information channels that professionals cannot readily replace. Experian’s web of data remains embedded because replacing it would be like changing your house number halfway through the post. Unilever may not be glamorous, but watch the trolleys on your next supermarket visit. Brands that stock kitchen cupboards represent confidence expressed in quiet pounds.
This is neither a shopping list nor advice. It is a way of looking at companies. Seek pricing power that you can almost touch, agreements renewed because changing provider is a faff, returns on capital that do not swing wildly, and balance sheets capable of sleeping at night. Then wait for a valuation that gives you a cushion. Markets offer cheap umbrellas when skies are clear and charge dearly once clouds gather. Your task is to buy before the rain begins.
The principle is ultimately about temperament
Buffett’s advantage is not secret information or some enchanted formula. It is temperament: a composed readiness to look foolish for a period in order to appear wise later. It is a determined preference for businesses supplying real things to real people, bought at prices that can withstand the world’s disorder. The principle supplies a map, but it also gives you a rhythm. Going slowly is permitted.
Most of us begin amid the noise. The important thing is choosing the signal. When a company has a moat you can explain without diagrams, candid managers who treat capital as important, figures that quietly show consistency, and a price that does not demand perfection, you are approaching Buffett’s sweet spot. The longer I invest, the more faith I place in the simple line I attached to my screen years ago: Buy wonderful businesses at fair prices. The market will not issue a certificate to confirm that you are doing it properly. You will recognise your progress when the screen becomes boring and your conviction becomes loud.
Comments
No comments yet. Be the first to comment!
Leave a Comment