
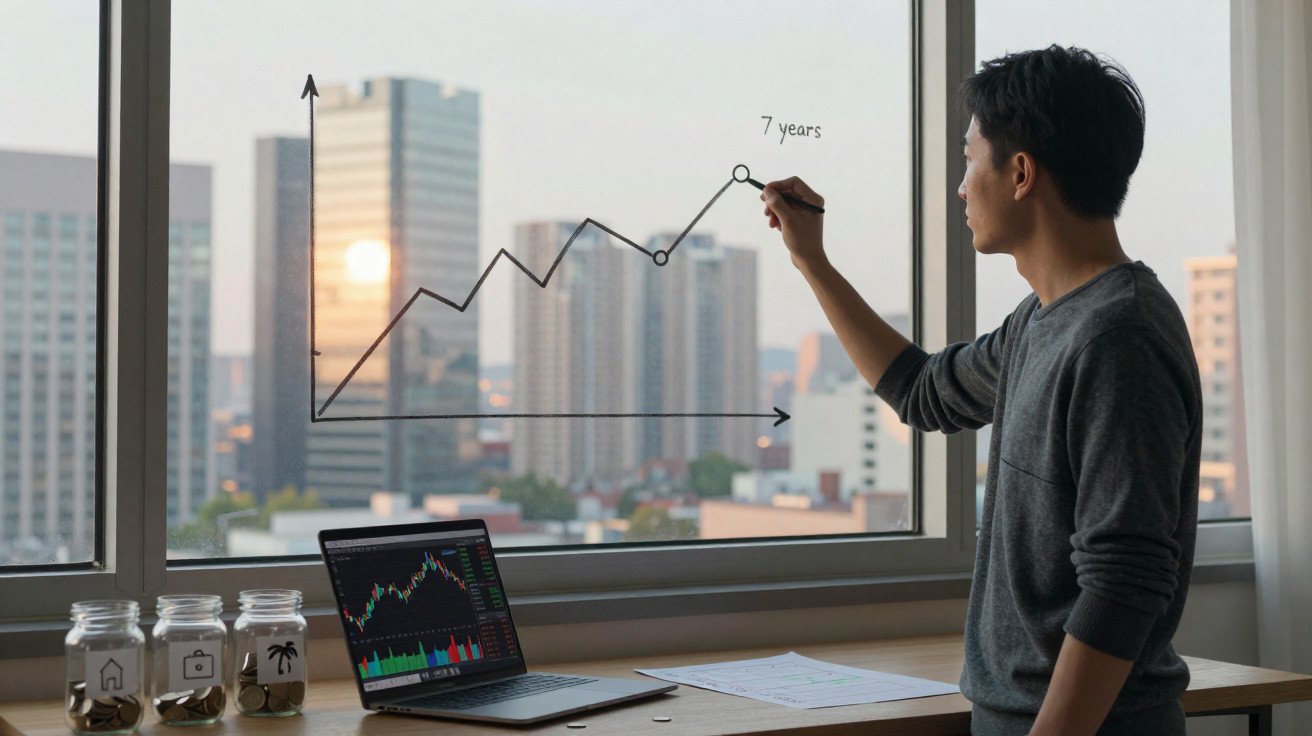
I was running a finger down an old price chart, partly through routine and partly through sheer optimism, when I spotted it: a tidy, almost mischievous pattern. Roughly every seven years, the market went through something dramatic. Not a minor tremor, but a genuine reset. It was the kind of event that could turn prudent savers into unexpected tycoons, provided they could bring themselves to buy when the atmosphere reeked of burnt coffee and grim news. We all know that feeling, when the glow from the screen seems colder than the room and your heart starts arguing with your head. Honestly, I initially assumed I was imagining things. But when I checked the history again, it played the same melody. The unusual thing is not that the cycle appears to exist; it is what can happen if you place faith in it.
The curious seven-year rhythm
A veteran City broker - the sort who still uses a fountain pen to underline passages - once said to me that markets are simply memory combined with money. Memory, he argued, fades to a schedule. He said it with the exhausted conviction of somebody who had traded through Black Monday, the dot-com fireworks and the long, bleak winter of 2008. In his diary, he had made small marks at seven-year intervals. He was not pretending it was exact. He was recognising a pulse.
When I first put it on paper, it seemed almost like a cheat: every seven years, the market offers a bargain. And not a neat, comfortable bargain. It is the untidy sort, packaged in panic and dinner-party disputes. The seven-year window almost never comes with a bell. It shows up through redundancies, midnight central-bank announcements and friends declaring that they will never purchase shares again. A few months later, naturally, it all looks obvious with hindsight.
What the charts reveal: 1987 to 2022 in beats
The seven-year markers
Begin in 1987, with the crash that people remember even when they did not live through it. In one month, the decline split the headlines apart. By 1994, seven years later, markets were not crashing, but they had been hobbled by a vicious bond sell-off and fears over rates. The S&P 500 drifted lower and recovered, the FTSE 100 faltered, and Mexico’s peso crisis whispered across trading floors. It was not devastation, but it was a reset: returns levelled off, nerves wore thin and positions were cleared.
Next came 2001–2002. The dot-com bubble did more than burst; it emptied out dreams. From its 2000 high, the S&P 500 fell almost 50%. The Nasdaq lost far more, while entire careers quietly shifted into consulting. Seven years later, 2008–2009 brought the kind of crash that changes a generation’s language. Banks collapsed. The FTSE dropped by roughly 45% peak-to-trough. Passing a television in a pub, you could tell from the silence exactly what the chart must have looked like.
Another seven years brought 2015–2016, when China’s devaluation scare coincided with an oil-price collapse. It was not a worldwide depression, but portfolios still bent under the strain. Many indices fell by double digits. Small caps fought for breath. Then came 2022: inflation surged, rates raced higher and the bear market appeared. The S&P 500 lost roughly a quarter from its highs, technology fell considerably more, and UK gilts endured the sort of drawdown that nobody had modelled at scale. Those are five beats: 1987, 1994, 2001–2002, 2008–2009, 2015–2016, and 2022. It resembles a metronome with a cough, yet it keeps enough time for anyone prepared to wait.
What occurred between the markers
This is the part that builds wealth: the recovery curves. Had you invested at or around the 1994 malaise and held on until the 2000 peak, the S&P 500 would have roughly tripled. Buying around the 2009 lows and holding until mid-2015 produced something close to another threefold gain. From the winter of 2016 to the highs of 2021, there was another powerful rise, driven by software and chips. Even the 2022 bear market had, by late 2024, returned major US benchmarks to fresh highs. The exact result depends on the dates selected, dividends and whether you chased the hot sectors, but the form remains familiar: a fall followed by a rise.
That rise is where millionaires tend to emerge quietly. It is not because they found some miracle share with a meme attached to it, but because they viewed the seven-year slump as a clearance sale. They bought the index. Perhaps they added a few world-class businesses that had suddenly become 60% cheaper. Then they sat through the dull middle period, all the way to the euphoria that feels like drinking champagne on a Tuesday.
Why seven years keeps reappearing
There are tidy academic explanations, and then there is the explanation you can sense in real life. People forget. Boards are replaced. Credit conditions unwind. Venture capital pours into a theme, dries up and eventually returns for the next fashionable idea. Political cycles rearrange priorities. A product introduced in year one reaches scale by year five, becomes saturated in year seven and faces disruption by year ten. Somewhere along that path, the market needs a wash and a reset.
Loan terms, corporate refinancing periods and budget cycles often bunch around three, five and seven years. Central banks battle the previous war until inflation or unemployment makes them fight another one. Stories become stretched until reality pulls them back into a smaller form. Seven years is long enough for the crowd to forget and for the cycle to reset. It is short enough for the scars to keep itching, yet long enough for old errors to seem novel once they are dressed in fresh jargon.
How millionaires actually used the seven-year cycle
The three-bucket approach
The people who got this right were not heroes. Their plan could fit into a text message, and they followed it while friends were doomscrolling. They maintained three buckets. The first was for everyday life: untouchable and dull. The second was for regular monthly investing, whatever the weather. The third was smaller, but kept ready for seven-year storms. Once the storm arrived, they put that third bucket into the market in two or three tranches, because nobody knows the bottom while the wind is still howling.
They did not require perfect timing. What they needed was a strong stomach and a clock. Buy near the fear of 2015–2016, then hold into the glow of 2021. Buy near the mud of 2009, then hold into the shrug of 2015. They were not checking prices every morning. Let us be honest: nobody truly does this every day. Instead, they went for walks, took the children to school and allowed time to do most of the work.
The dull checklist
Their decisions were unexciting. Global equity trackers. A small collection of dominant franchises with moats simple enough to draw on a napkin. Businesses selling the picks and shovels for new gold rushes - chips, cloud, logistics and rail. They focused less on the coming quarter than on the next seven Christmases. They also used tax wrappers so the snowball could keep rolling without being chipped away at the edges.
There is a line I have written so frequently that it now feels like a nursery rhyme: The millionaires weren’t lucky; they were patient. They did not pursue every spike. They kept dry powder for the years when headlines sounded like storm sirens. Nor did they sell everything at the first rebound. They wrote down a number of years and made themselves a promise, the sort you do not announce on social media because breaking it would be too visible.
A subtle British variation
In the UK, the pattern is recognisable, though it wears another coat. The FTSE 100 has a heavy weighting in banks, energy and mining, meaning its highs and lows can feel closely linked to commodities and global interest rates. The 2015–2016 period hurt especially badly here because oil and mining businesses took a blow to the ribs. In 2022, bondholders suffered as much as equity investors, an unusual symmetry. If you were clever or fortunate enough to fill an ISA during those periods, you gave yourself a tax-free trampoline for the recovery.
Then there is the pound. In 2016, sterling wobbled, making UK investors holding US shares feel as though they had discovered money behind the sofa, before removing it just as swiftly. The key is to understand that this happens and not become theatrically clever about it. Purchase the global tracker inside your ISA when the seven-year rain arrives. Add to your pension if possible. Resist the temptation to outsmart exchange rates at 11:47 p.m. on a Wednesday.
I can still recall the smell of damp coats on the DLR during the 2016 China scare. People looked at headlines on their phones with the bleak expression of a morning after. Then they carried on to work. The market, affronted and bored, reached new highs a few years afterwards. Those who smiled quietly were the people who added to their ISAs on the way down and did not stop when the sunshine returned.
But is it not messy?
It is, and that is precisely the point. The seven-year pattern is not a prophecy. It is a habit that markets cannot entirely abandon because people cannot fully abandon theirs. At times, you will buy too soon. At other times, you will wish you had waited three more weeks. Some days, the gap between your plan and the figure on the screen will feel as wide as a canyon.
That is why process is important. Write down your figures while your hands are calm. Set alerts. Decide how many tranches you will use before you need them. Leave your future self instructions you can rely on when you are exhausted and overstimulated. You don’t need to predict the crash; you need a calendar and a spine. With that, you can survive being wrong about the small details for long enough to be right about the large one: time.
Evidence in the rear-view mirror
Choose the markers and replay the chart. Buy in the gritted-teeth stretch of 1994, hold until 2000, and you captured a market that roughly tripled. Buy the sludge of early 2009, sell nothing through 2015, and your index doubled and then doubled again with dividends. Add a few durable technology and logistics businesses in 2016, and by 2021 you might have read your brokerage statements twice, simply to make sure the commas had remained faithful.
Even the uncomfortable examples paid off if you observed the seven-year period. Buy in late 2022, when inflation narratives beat like a drum, and by late 2024 you were seeing fresh US highs and recovering returns elsewhere. Was it orderly? Not in the slightest. Could it alter a life when carried out with discipline through several cycles? More often than cynics acknowledge.
Why the pattern creates millionaires rather than geniuses
Genius attempts to identify market bottoms to the hour. Millionaires make plans around birthdays and bank holidays. Genius trades a story; millionaires trade a calendar. They recognise that worrying over the next 4% is one way to miss the next 200%. Their goal is not to arrive first. It is to remain present when it counts.
The seven-year habit succeeds because it makes you pay attention to major drawdowns and lengthy holding periods. It converts panic into procedure. It cuts through the noise with one useful question: is this one of those years? If it is, you open the third bucket and press the button, even if your finger trembles. After that, you continue living ordinary days while compounding works the late shift.
Signals to watch without becoming a monk
Three dashboard lights
Credit spreads. IPO windows. Unemployment turning. When all three behave strangely at once, the seven-year drum often begins to beat. Spreads widen, flotations disappear, employment figures bend and front pages replace celebrity gossip with charts.
When that occurs, there is no need to rush about predicting disaster. Take out your notes. Remind yourself how many tranches you intended to make. Buy the highest quality available at a discount large enough to feel faintly improper. Then leave the prophets to debate the second decimal place.
The difficult truth
The seven-year idea is not glamorous. It requires you to do nothing for most of the time, then do the uncomfortable thing at exactly the point when you least want to. This is not a trading strategy; it is a strategy of patience. You will feel foolish if prices continue falling after your first purchase. You will feel greedy when they rebound and friends say that you were fortunate.
Then you will examine a ten-year chart and see that luck looks remarkably like a habit. There is a calmness to it: a quiet desk, a brief checklist and a life not shaped around screens. The wealthiest people I have met chose to move slowly. They talked in years rather than ticks.
The next seven years
If the pattern continues, 2022 was a marker. That implies the next serious, deep reset could be nearer to 2029 than 2026, although smaller storms will arrive and pass. From now until then, we are in the climb that history often gives to those who kept buying when it seemed improper to do so. There will be scares, as there always are: elections, wars, supply disruptions and the AI flavour of the day. A calendar will not shield you from volatility, but it can prevent you inventing stories at 2 a.m.
So note the year down. Put a circle around it on a real page with a real pen. When the music shifts and everybody claims they saw it coming, your script will already be prepared. Seven years is long enough for the crowd to forget and for the cycle to reset. The remaining question is simple, irritating and impossible to resist: when the next storm arrives, will you remember that you had been waiting for it?
Comments
No comments yet. Be the first to comment!
Leave a Comment