
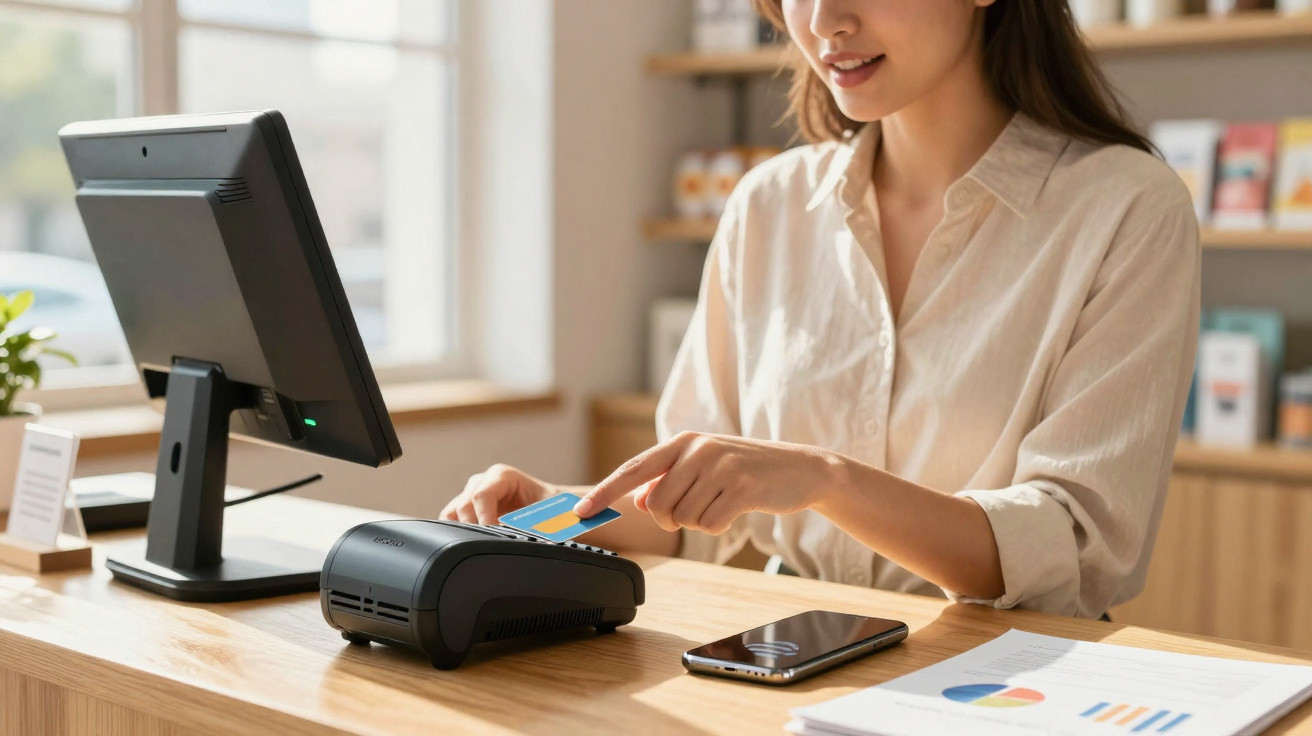
London’s financial regulator is easing the rules for contactless card payments. Banks and payment providers will soon be able to set their own maximum amount, potentially well above the current £100 cap, provided their fraud controls are considered sufficiently robust. Although this may sound like a technical adjustment, it will have tangible everyday implications for millions of customers.
What changes from Thursday
Until now, the UK’s Financial Conduct Authority (FCA) imposed relatively strict conditions on contactless card payments. The key rule was a maximum of £100 for each contactless card transaction, regardless of the bank issuing the card.
Under the new rules, the FCA is removing that fixed ceiling. Firms able to demonstrate resilient fraud-prevention systems can choose their own limit, in theory setting it above £100.
“Banks and payment providers will be free to set the limit for contactless payments themselves – both higher and lower.”
Importantly, the major UK banks have already indicated that they will retain the £100 limit for the time being. However, they also say they will keep the situation under review and may make changes in future.
Why the FCA is relaxing contactless card payment rules
The regulator has several aims with this reform:
- Consumer expectations: Contactless payment is now commonplace, and customers expect swift, seamless transactions even for larger purchases.
- Inflation: As prices rise, the existing maximum is reached more quickly than it was a few years ago.
- Technology: Improvements in fraud prevention, data analysis and real-time monitoring allow greater flexibility without abandoning security.
The FCA also hopes the extra freedom will encourage banks to strengthen their anti-fraud measures. Providers that permit higher contactless amounts must raise their security standards accordingly.
Contactless payments are booming: the figures behind the trend
Recent UK data illustrates just how much day-to-day payment habits have shifted:
- Around 94.6 per cent of all eligible in-store card payments were made contactlessly in 2024.
- There are now roughly ten times as many contactless transactions each month as there were in 2015.
- Contactless payments account for 67 per cent of all credit-card payments and 76 per cent of all debit-card payments.
- The average contactless transaction is just under £18.
Contactless payment is therefore no longer a niche option for very small purchases; it has become the standard way to pay at the till.
What banks can do now – and what they are not doing yet
Although the new framework formally provides almost unlimited scope, providers are taking a cautious approach. Here is an overview of the main players in the UK market:
| Bank / provider | Current card limit | Can customers set their own limits in the app? | Plans for future change |
|---|---|---|---|
| NatWest | £100 | Yes, can be reduced below £100; contactless can be switched off | No short-term changes planned |
| Santander UK | £100 | Yes, adjustable in £5 increments; contactless can be switched off | No changes at present |
| Lloyds / Halifax / Bank of Scotland | £100 | Yes, in £5 increments up to £100 | Flexibility remains; limit initially unchanged |
| Barclays | £100 | Yes, adjustable up to £100 | Retaining £100 |
| HSBC UK / First Direct | £100 | A lower card limit cannot currently be set | No short-term change planned |
| Nationwide / Virgin Money | £100 | Yes, smaller limits can be set in the app | Monitoring the situation; no immediate changes |
| TSB | £100 | Limit can be reduced; contactless can be switched off | Upper limit remains £100 |
| Starling Bank | Up to £100 | Yes, from £0 to £100 in the app | Reviewing the rule change; no decision yet |
| Monzo | £100 | Yes, can be reduced or disabled | Reviewed regularly; no current change |
| Revolut | £100 | No lower contactless limit, but a monthly budget can be set | Under review; no plans for a short-term increase |
A clear pattern is emerging: while many providers have not decided to raise their limits, they already allow customers to reduce their personal cap or switch off contactless payments entirely.
What is a “cumulative limit” – and how will it change?
Alongside the limit for an individual transaction, another factor operates in the background: the cumulative limit. Until now, customers have had to enter their PIN again after a certain number of contactless transactions or after reaching a specified total amount. This helps prevent a stolen card from being used repeatedly to drain funds through quick tap-and-go purchases.
Banks will also be allowed to adjust this setting in future. They could, for example, permit more contactless transactions without a PIN or, conversely, request verification sooner. The FCA does, however, require firms to explain any such changes to customers clearly and understandably.
Security: how high is the fraud risk in reality?
As limits increase, so does concern that fraudsters could take more money if they get hold of a card. Banks therefore stress that security comes first. They already absorb most of the cost of card fraud, giving them a direct financial reason not to take excessive risks.
“The basic protection remains: for unauthorised contactless payments, such as those made after a card is stolen or lost, the bank must refund the money.”
Modern fraud-analysis systems can also identify suspicious patterns in real time. Unusual payments can be stopped or blocked following a brief check. At the same time, mobile wallets – payments made with a smartphone or smartwatch – are becoming increasingly important.
Why smartphone payments permit higher amounts
There is one significant distinction: with a phone, the device itself acts as a second security factor. Users must verify their identity, for example with a fingerprint or facial scan. As a result, many providers already allow considerably higher contactless amounts when payment is made by smartphone rather than with the physical plastic card alone.
For customers, this means that a mobile wallet is usually better protected than a physical card alone when they want to make larger contactless payments quickly and regularly.
What consumers can do now
Even if the visible maximum does not initially change much, it is worth checking your own banking app. Many accounts now offer surprisingly detailed controls:
- Set your own maximum for each contactless payment
- Disable the card’s contactless function completely
- Define monthly spending limits for the card
- Turn on instant notifications for every card payment
Anyone uneasy about higher contactless amounts can therefore actively reduce the impact by setting tighter personal limits than those imposed by their bank.
Why this matters for German-speaking countries too
The rule change applies directly only to the UK, but it clearly points towards a development likely to appear in other markets over the medium term: national maximum caps are becoming less rigid, providers are receiving more discretion, and contactless payment is moving ever closer to conventional card payments without a fixed limit.
The central question remains the same everywhere: how much convenience are people willing to accept without getting burned on security? In many countries, customers are simultaneously gaining more options to block cards with one tap in an emergency, adjust limits in an app and receive real-time payment alerts.
One vital point can easily be lost among all the technical details: consumers should understand their card and app settings. Those who know which caps are in place, how often a PIN must be entered and how to block a card in an emergency can use this new freedom with far greater confidence.
In effect, the UK rule change marks the start of a large-scale real-world test: how far can limits be raised before customers become uneasy or fraud cases increase? The answers are likely to be watched very closely in Berlin, Vienna and Zurich over the coming years.
Comments
No comments yet. Be the first to comment!
Leave a Comment