
He is looking at something far smaller: a bulging, folded wallet that will hardly shut. Receipts spill out like confetti, loyalty cards poke out of the side compartments, and a bank card sits somewhere inside, ready to be tapped without a second thought.
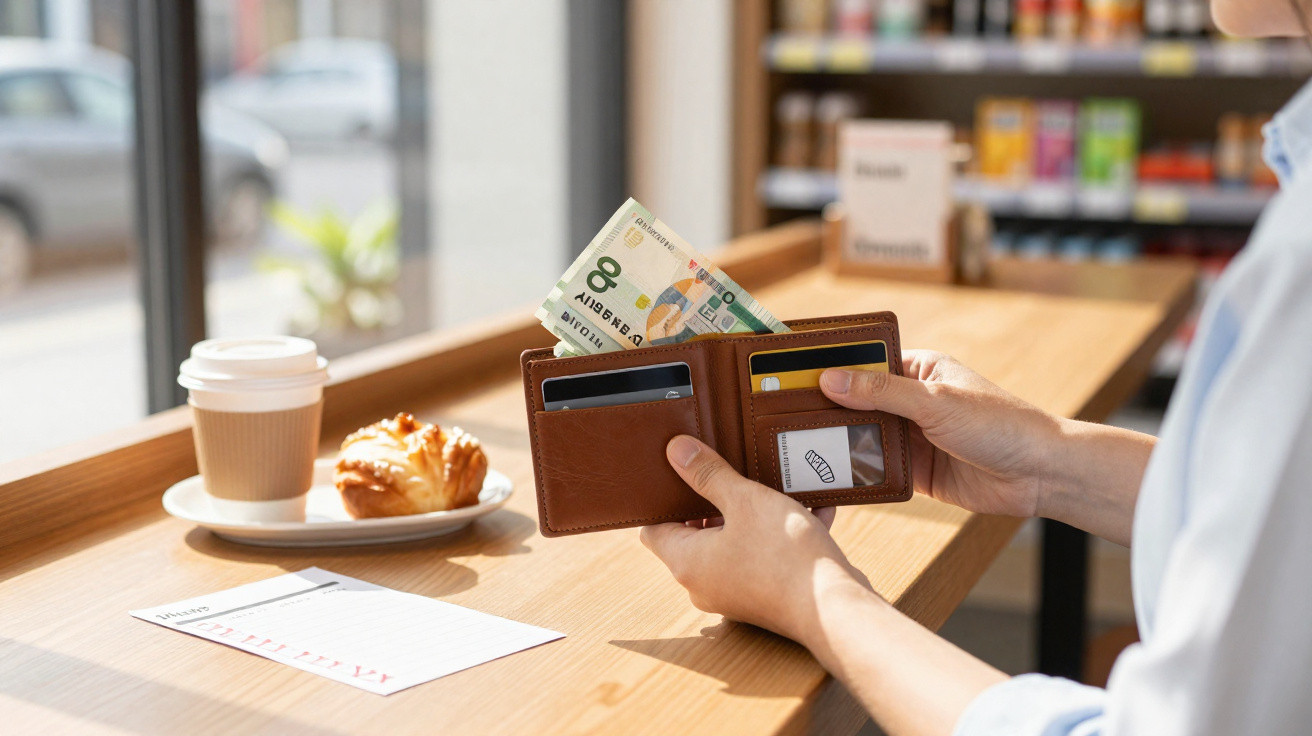
At a till two places away, a woman takes out a slim, well-organised wallet. It contains three cards and a few neatly stacked banknotes. There are no stray bits of paper. She checks the total, hesitates, then quietly puts one item back from her basket.
It is the same shop, the same promotions and the same point in the month. Yet the behaviour is different.
Perhaps the true trigger for spending is not always around us, but in the wallet we carry throughout the day.
The hidden order in your wallet
Most people assume their spending issue starts with a shopping app, persuasive emails or the sale rail. But much of it may begin somewhere rarely discussed: the leather rectangle you open ten times a day. A cluttered wallet can make money feel abstract, like play money mixed in with loyalty cards and old receipts.
A neat wallet has the reverse effect. It delays you for half a second. In that tiny pause, your mind has time to ask, “Do I actually want this?”. When every item has a place, you notice more clearly what is leaving your hand. Banknotes do not disappear among chewing-gum wrappers, and cards are not pulled out as a reflex.
External order can subtly create internal order. Your wallet is a small environment you take everywhere, and environments influence behaviour long before willpower has an opportunity to intervene.
Several years ago, a behavioural economist in London carried out a small, informal “experiment” with his students. He proposed a straightforward exchange: he would purchase a new minimalist wallet for each student who emptied and sorted their current wallet in front of him. They had to discard old receipts, take out inactive cards and retain only the items they genuinely used.
A month later, he sent them a brief follow-up survey. Of the 27 students, 19 said they were “more aware” of their spending. Ten said they made fewer impulse purchases in shops. One student wrote, almost apologetically, that she now felt “a bit guilty” when tapping her card for small purchases - simply because the card was alone, visible and almost exposed.
This is the quiet influence of an orderly wallet: it alters how money enters your awareness. When banknotes are folded neatly and cards sit in separate slots, every payment feels like a small, purposeful decision rather than an automatic background habit. Spending becomes less of a vague movement and more of a distinct action you register.
Psychologists refer to “cue exposure” - the subtle prompts that steer our decisions. A disordered wallet contains plenty of spending cues: loyalty cards urging you to use them, old receipts that make previous splurges seem normal, and coins scattered around like leftovers. Your brain reads this as: “I shop all the time, this is normal”.
An organised wallet removes many of those mental prompts. You are faced with fewer brands, logos and reminders of unplanned purchases. What remains is simple: money comes in, money goes out. This produces what researchers call “financial salience” - the feeling that this is real money rather than points in a game.
There is another effect as well. Keeping one small part of your financial life in order gives your brain a gentle identity prompt: I’m someone who takes care of my money. That sense of identity may do more to settle spending impulses than a budgeting app notification. Apps make noise; your wallet simply and quietly reflects the person you are becoming.
How to make your wallet a quiet spending brake
The first move is not to buy an expensive new wallet. It is to confront the one you already have. Tip it out completely onto a table: every banknote, coin, crumpled ticket and loyalty card from shops you no longer even enjoy. All at once, your wallet that was “only a little messy” can look like a miniature record of past impulses.
Then apply a filter. Keep only what you use each week: your primary bank card, perhaps a spare, identification, one or two essential loyalty cards and some folded banknotes. Nothing more. Put everything else in a drawer or cut it up. Try to leave visible space between the contents of your wallet - some room to breathe. As you return items, assign every one to its own compartment. Keep all banknotes facing the same direction, and carry only a small, deliberate amount of coins, or none at all.
The aim is not perfection. It is friction. That extra second created by order is precisely when an impulse can start to weaken.
Many people begin enthusiastically before returning to disorder in the second week. Life becomes hectic, and the wallet turns back into a pocket-sized bin. This is normal. On a busy Tuesday, slipping a receipt inside “just for now” can seem easier than finding a bin. Then “just for now” is repeated twenty times.
The answer is to create a small ritual that suits ordinary life. You might sort your wallet every Sunday evening while the kettle boils, or on every payday. Spend two minutes on it, without fuss: throw away receipts, count your banknotes and notice anything that surprises you. During a difficult month, a small pile of fast-food receipts can hurt to see. But that discomfort can be useful.
Let’s be honest: nobody really does this every day. Daily discipline is not required. What you need is small, truthful contact with your own behaviour often enough to remain aware. A tidy wallet is not a moral achievement; it is simply a practical method of seeing yourself more clearly.
Your wallet can also send a message back to you. One woman I interviewed kept a folded piece of paper behind her main card. In her own handwriting, it said: “Is this worth one hour of my life?” She explained that she did not read it every time, and she did not need to. Merely knowing it was there changed how she felt when reaching for her card.
“The moment my wallet stopped being a storage box and became a checkpoint, my spending changed. Not overnight. But enough that I finally felt I was driving, not being dragged along.”
Small reminders can help sustain this mindset:
- One photograph that recalls what you are truly saving for, rather than ten unrelated cards.
- A cap on card slots - a physical limit that makes you decide what matters.
- A coloured sticky dot on your main card as a visual prompt to “pause” before tapping.
- A handwritten mini-rule, such as “Wait 24 hours for anything over £50”.
- A monthly “wallet day” in your calendar: nothing elaborate, just ten focused minutes.
When wallet order carries into the rest of your life
The value of an organised wallet is not that it saves a few coins. It is that it gradually reshapes the story you tell yourself about money. A cluttered wallet says, “Things happen to me. Money comes, money goes, I’m just trying to keep up.” A neat wallet repeats a different message: “I have limits. I make choices.” It may sound minor, but it is not.
Over time, this can influence other choices. You may be more inclined to check your banking app before a major purchase. You may find it harder to say “I’ll just put it on the card” without reflecting first. You might even begin carrying a fixed amount of cash for treats - and, once it has gone, it has gone. Not because of guilt, but because of clarity.
On a difficult day, an orderly wallet can offer unexpected comfort. Even if your finances are not where you want them to be, opening something neat and intentional can feel grounding. It shows that your future self has a seat at the table too, rather than only the version of you seeking the quick thrill of buying something shiny.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Visual order | A streamlined wallet makes money feel more “real” and visible | Reduces reflexive and automatic purchases |
| Mental micro-pause | Each payment requires a clear, deliberate action | Creates enough time to ask whether the purchase is worthwhile |
| Financial identity | An organised wallet reinforces the idea “I take care of my money” | Helps change habits without relying solely on willpower |
FAQ
- Does a tidy wallet really change spending, or is it just symbolic? It does both. Physical order reduces visual clutter and spending cues, while its symbolism moves your identity towards “someone who chooses”, affecting genuine behaviour.
- Should I stop carrying cash to avoid impulse buys? Not necessarily. For some people, cash actually feels more concrete than digital payments. Try carrying a set amount for flexible spending and observe how you respond.
- How often should I declutter my wallet? Once a week or once per pay cycle is generally sufficient. The most important thing is a small, repeatable routine that keeps you connected to your habits.
- Is a minimalist wallet always better? A slimmer wallet can help, but only when its contents are intentional. A small wallet crammed with random cards sends the same mixed messages as a large, messy one.
- What if my life needs lots of cards and receipts? Separate the functions: keep your everyday wallet minimal, and store extras in a separate card holder or pouch at home or in your bag.
Comments
No comments yet. Be the first to comment!
Leave a Comment