
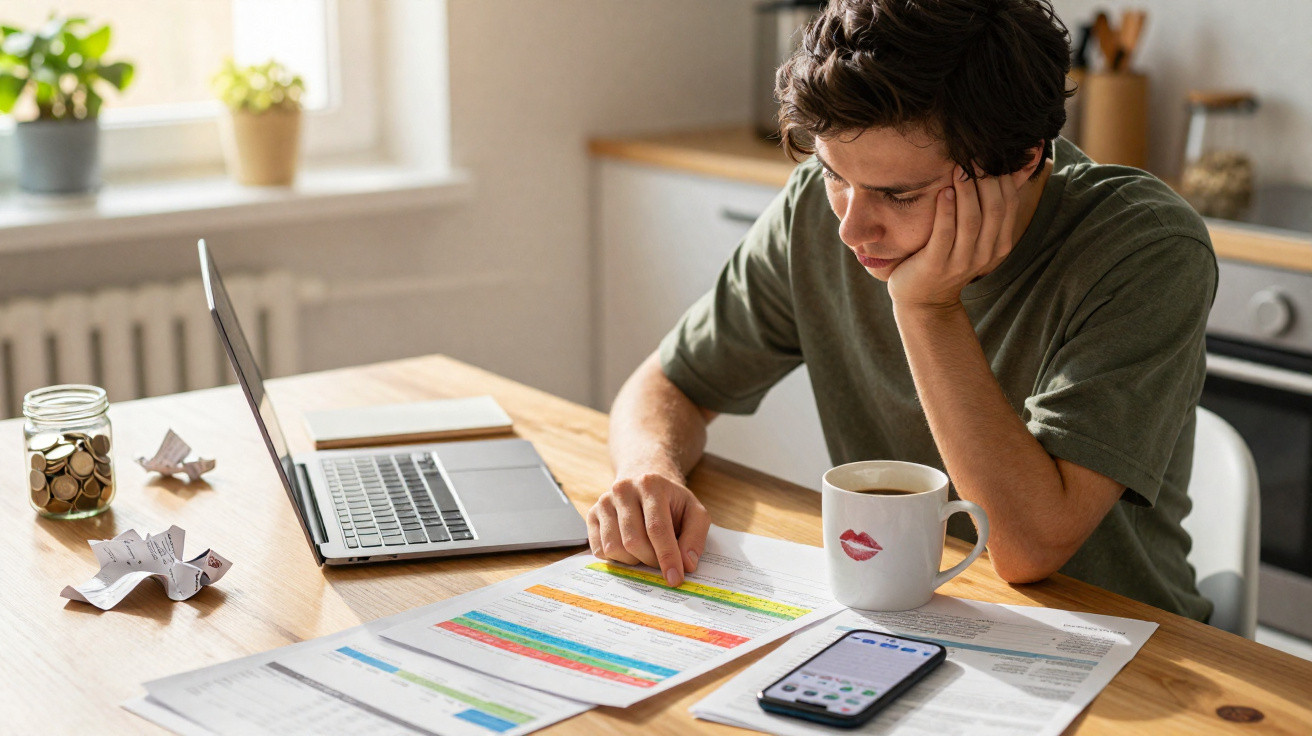
On the final Sunday of each month, the coffee table vanishes beneath receipts: bus tickets, coffee-shop loyalty cards and a creased chemist’s receipt that somehow made it through the washing machine. Meanwhile, the banking app on the laptop tells its own small story of the previous four weeks: supermarket trips, late-night takeaways and a “quick” Amazon look that somehow became three separate purchases.
Most of us take a quick look, recoil at the total and close the app.
Yet, if you linger for a moment, something unexpected happens. Patterns begin to surface. Small routines emerge from the clutter. Before long, your financial story looks nothing like the version you had in your mind.
Why your money reality never matches your memory
Ask somebody what they spend on eating out each month and they will usually take a guess. “Oh, not that much. Maybe once or twice a week.” Then their bank statement reveals thirteen restaurant payments, three late-night delivery orders and several trips to cafés.
Memory is selective. It rounds off the edges, ignores the mundane details and removes the parts that feel uncomfortable. But those uncomfortable details are exactly where money tends to go.
That is why even a straightforward monthly spending review can feel confronting: it reflects the life you truly lead, rather than the one you imagine you lead.
Consider Sophie, 32, who believed rent was her “big problem”. She grumbled about it every month. “If my rent was lower, I’d finally be able to save,” she’d say. One quiet Sunday, she reviewed three months of spending in full, checking every entry line by line.
Her rent was expensive, certainly, but another figure stood out: transport. She had spent more on ride-hailing journeys and last-minute train fares than she had on food shopping. Most individual costs were small: £6.80 here, £11.40 there, plus an airport journey she had completely forgotten.
Once she combined those payments, the “high rent” was no longer the main culprit. The real drain came from the small, near-invisible journeys she never consciously included in her calculations.
There is a reason such leaks remain out of sight. We recall the large, painful costs: a car repair, a surprisingly high energy bill or a birthday meal that exceeded the budget. Small everyday card payments scarcely register. The brain labels them as “normal life” and carries on.
A monthly spending review interrupts that blur. Instead of examining isolated purchases, you can see categories, frequency and timing.
Patterns are not visible in a single transaction. They emerge in groups, and groups only become clear when you take a broad enough view.
How to review a month of spending without melting down
Keep the first step ridiculously simple. Choose one day, open your main bank or card account and download transactions from the last complete month. You do not need an elaborate spreadsheet initially; a basic list will do.
Next, work through each entry and assign it a broad category: groceries, eating out, transport, rent, fun, impulse, health, children or “no idea”. That final category matters. If you cannot recall why you spent the money, mark it.
This initial review is not about getting everything perfect. It is about discovering where your money really goes between Monday and Sunday.
This is where many people struggle: halfway through, they begin judging themselves and snap the laptop shut. A run of takeaway payments appears, and the inner critic takes over: “You’re so careless. You waste money constantly.” That voice ends the review faster than any total ever could.
Instead, treat the exercise as a detective would, not as though you are a defendant in court. You are not being judged; you are collecting evidence.
Some months will be untidy. Others may be dominated by medical costs or school expenses. Sometimes the statement will simply show that you were exhausted and paid to avoid cooking on three separate evenings. That’s still information.
When you finish your review, stop and identify just three things: one surprise, one pattern and one small lever you could adjust next month.
“Once I started doing monthly reviews, I realised my ‘coffee problem’ wasn’t coffee at all,” says Leo, 28. “It was the days I skipped breakfast. Those were always the days with two lattes, a pastry, and then takeaway for lunch. The pattern wasn’t caffeine. It was mornings.”
- Identify one “invisible” category: something you never mention but regularly spend money on each week.
- Pay attention to emotional days: evenings when spending rises after bad news, stress or boredom.
- Watch for timing spikes: pay-day weekends, mid-month lows and Sunday-night comfort purchases.
- Pick one experiment: a small adjustment to test next month, rather than a complete life transformation.
What monthly spending patterns quietly say about your life
A month of spending acts rather like a diary without descriptions. It records the brunches you accepted, the hobbies you dropped and the subscriptions you forgot were still being paid. Look carefully and you may spot shifts in mood, periods of burnout and flashes of optimism.
Some people notice they spend most on “treats” during the same week they complain most about money. Others find that their costliest days are not weekends at all, but lonely Tuesdays.
In truth, hardly anyone completes this exercise every day. A monthly review is frequent enough to catch a habit before it becomes entrenched, while being infrequent enough to feel manageable.
Monthly reviews regularly uncover a simple reality: your values and your spending do not always agree. You may insist that you “don’t care about clothes”, then find a new fashion purchase every week. You may say travel matters most to you, only to discover that random delivery apps absorb half your money.
Seen in this light, a spending review is not a punishment but an act of alignment. It means asking yourself, “Does this match the life I say I want?”
At times, the answer will be yes. You may realise that you genuinely value weekly coffees with a friend and would prefer to reduce another cost instead. That is a pattern to preserve, not remove.
A monthly review can also reveal identity drift. Perhaps three years ago you went to the gym three times a week. Your bank statement still assumes that you do. Every month, the membership payment quietly leaves your account while you pass the gym without a thought.
A 30-minute monthly check creates a necessary reality check: “Is this still me?”
After that, decisions tend to become easier. End memberships you do not use. Replace two delivery orders each month with a proper Saturday food shop. Reschedule a forgotten “rainy day” savings payment for the same date as your rent, so it is out of sight before you choose to miss it.
| Key point | Detail | Value for the reader |
|---|---|---|
| Monthly reviews uncover hidden patterns | Small, regular costs form clear categories across 30 days | Creates a realistic view of where money truly goes |
| Prioritise categories over individual purchases | Sort transactions by type, mood or timing instead of scrutinising every payment | Limits guilt and identifies genuine points of influence |
| Turn findings into small experiments | Adjust only one habit each month according to what you notice | Makes financial progress feel realistic and sustainable |
FAQ:
- How long should a monthly spending review take? For most people, 30–45 minutes is enough. The first review may take longer, but you will soon find a routine and it will feel more like a quick money check-in.
- Do I need a special app or spreadsheet? No. To begin, a bank export and several broad categories are sufficient. You can use apps or templates later if you enjoy the process.
- What if my spending is “too messy” to face? Begin with one account or card and a single week, then build up to the whole month. You are not trying to impress anybody; you are simply trying to see reality a little more clearly.
- How many categories should I use? Keep it broad: 8–12 categories suits most people. Too many labels will leave you overwhelmed by detail rather than able to see patterns.
- What do I actually change after the review? Choose one small experiment based on what you found: set a limit on delivery evenings, use a weekly cash envelope for cafés or cancel one unused subscription. Review again next month, then adapt.
Comments
No comments yet. Be the first to comment!
Leave a Comment