
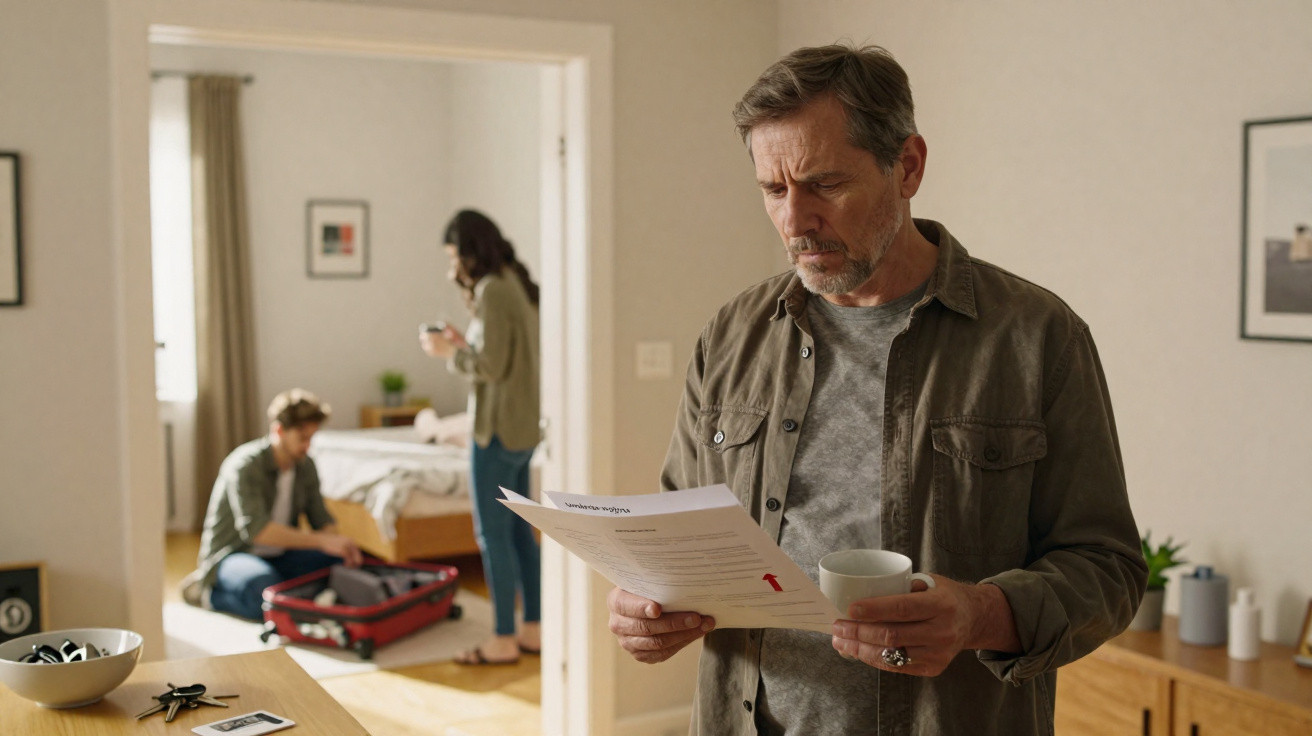
He believed he was giving a struggling relative a lifeline.
Then a letter from the tax office transformed that act of kindness into an unexpected bill.
The experience of a homeowner whose property tax increased after he allowed his unemployed cousin to live with him rent free has prompted heated online debate. A low-key family arrangement has become a warning about tax rules, how homes are used, and the point at which generosity meets bureaucracy.
A favour that became a financial shock
The unnamed homeowner owns a modest three-bedroom property in a suburban neighbourhood. Last year, his cousin lost his job and no longer had a secure place to stay. The answer appeared straightforward: he could use the spare bedroom without paying rent while he got back on his feet.
His cousin used the address for benefit claims and job applications, and the arrangement worked without difficulty for several months. There was no contract, no official tenancy and, crucially, no rent.
That changed when the homeowner received his annual property tax assessment.
The tax authority now treated part of the property as a “non-primary residential use”, triggering a higher tax bill.
The charge had risen by several hundred dollars compared with the previous year, accompanied by a note referring to a review of the property’s “usage profile”. The homeowner says he had never been told that this might happen.
How a spare room can alter property tax status
Property tax arrangements differ between countries and regions, but one principle is widespread: the way a home is used may affect the tax payable. In certain areas, owner-occupiers receive a reduced rate or particular exemptions. Those benefits may be reduced if officials conclude that part of the home is being used as another dwelling or as income-producing accommodation.
In this instance, the local assessor examined information showing that another adult was living at the property, making separate benefit claims and with no indication of shared finances. That raised the issue of whether the cousin constituted a separate household rather than simply being a guest.
Officials argued that the property now functioned as a “multi-occupancy residence”, even though no rent changed hands.
After being categorised this way, the property entered a higher tax bracket, comparable to homes divided into flats or rented to several unrelated tenants. In the homeowner’s view, his domestic circumstances had not changed in any meaningful way, other than his decision to help a family member.
Online backlash: kind gesture or careless error?
When the account appeared on social media and local forums, opinion split sharply. Some considered him the victim of inflexible regulations that overlook family support. Others said he should have investigated the consequences before allowing somebody to stay for an extended period.
Critics: “You turned your home into a shared dwelling”
People less sympathetic to the homeowner stressed that tax systems cannot assess someone’s intentions. They merely identify the available indicators: an additional adult resident, separate official records and a long-term stay.
- One view is that a relative who moves in without a fixed end date means the property is no longer an ordinary single-family home.
- They argue that enforcement would become unworkable if councils made exceptions for every “cousin” or “friend”.
- Some commenters say the homeowner still gained from shared household bills and chores, despite not receiving rent.
Seen from this perspective, the higher bill is simply the consistent application of existing rules, while the homeowner’s error was failing to obtain advice beforehand.
Supporters: “You’re punished for helping family”
Supporters, however, believe the situation delivers a troubling message when household costs are increasing and family connections are frequently the final safety net.
“If helping your cousin sleep indoors costs you hundreds more a year, many people will simply shut their doors,” one commenter wrote.
They ask whether rigid definitions such as “primary residence” and “multi-occupancy” should be used where there is no rental income whatsoever. In their view, tax systems are penalising people who are not landlords but relatives attempting to do the right thing.
What tax offices assess when reviewing a home
Although terminology differs from region to region, assessors commonly consider much the same evidence. Tax specialists identify several usual triggers for a review of a property’s classification:
| Factor | Why it matters |
|---|---|
| Number of unrelated adults | Several adults who are not a couple may indicate a multi-occupancy arrangement. |
| Separate financial records | Separate benefit claims or tax records at one address can suggest independent households. |
| Length of stay | A brief stay appears to be a visit, whereas many months suggests residence. |
| Physical layout | Locked bedrooms, separate entrances or dedicated kitchenettes may signal a divided dwelling. |
| Declared use | The description of the property on forms and in official correspondence can influence the decision. |
In this homeowner’s situation, officials said the prolonged occupation of the home, together with the formal use of its address for benefits, made the cousin more than a visitor. They considered that sufficient to define the arrangement as a type of shared occupancy.
“I only wanted to help my family”
The homeowner says he had never expected his cousin’s unemployment to create a tax issue. They had grown up together, and after the cousin’s relationship ended, he had been sleeping on friends’ sofas.
For the homeowner, the absence of rent was central to the arrangement. He wanted his cousin to concentrate on finding work rather than falling further into debt. When the assessment arrived, he says he felt caught unawares and, in his words, “penalised for having a heart.”
“If I had rented the room out to a stranger, at least I would have had income to cover the extra tax. I got nothing but a bigger bill,” he said.
The cousin is said to feel responsible and has thought about moving out, although doing so would probably leave him in insecure accommodation again. The family is therefore left with a stark decision: pay the increased tax or end the arrangement that prevented one relative from becoming homeless.
Where family support meets policy objectives
The case prompts wider discussion about the overlap between housing policy and taxation. Governments regularly speak of promoting family assistance and informal care networks. Yet tax systems depend on clear categories that can be measured.
Primary-residence property tax relief is intended to help owner-occupiers. When a home begins to resemble shared accommodation, policymakers may become concerned about lightly taxed letting activity, overcrowding or safety requirements. This remains the case even where the reality is merely a cousin sleeping on a spare mattress.
Practical steps before housing a relative
Tax advisers say that, although frustrating, this homeowner’s experience may enable others to avoid similar surprises. Before providing long-term free accommodation to a friend or relative, they recommend several checks:
- Telephone the local tax office anonymously and ask whether another adult at the address could alter the property tax position.
- Establish how long somebody may remain a “guest” before they are treated as a resident for tax or benefit purposes.
- Make written notes of any advice received, including the date and the name of the person spoken to.
- Consider drawing up a basic written agreement stating that the arrangement is support rather than a commercial tenancy, even if it has no legal effect.
- Confirm that accommodating somebody will not affect any council tax reductions, homestead exemptions or comparable reliefs already claimed.
Some regions provide express exemptions for close relatives or carers. Elsewhere, regulations are tighter and tax forms make no distinction between a cousin and a lodger who pays rent. The only reliable approach is to ask early, rather than waiting until the bill arrives.
Understanding the terms behind the dispute
Two phrases underpin this case: “primary residence” and “multi-occupancy.” A primary residence is generally the main home in which a person lives for most of their time. Tax systems often offer that property preferential treatment, including reduced rates or limits on rises.
Multi-occupancy refers to homes in which multiple distinct households live within the same building. Shared student houses and bedsits are typical examples. Such properties may face higher tax and tougher safety requirements because they involve more occupants, greater wear and tear and, often, commercial rent.
The difficulty begins when a family arrangement resembles, on official records, a small-scale shared house. Data systems cannot identify intentions; they see only two adults who are not a couple living at the same address.
Different uses of the same spare room
To see how sensitive these definitions may be, consider three possible uses of one spare bedroom:
- Occasional guest: A friend stays for two weeks after a break-up, retains their previous address and contributes nothing towards bills. Most tax offices would regard this as ordinary hospitality.
- Long-term family support: A cousin moves in for a year, registers for benefits at the address, helps with groceries and treats it as his sole home. This occupies a grey area: some systems still view it as a standard family household, while others begin to investigate.
- Formal lodger: A stranger rents the bedroom under a written agreement and pays rent every month. In almost all places, this may lead to a different tax treatment.
What surprised this homeowner was that his local authority considered the second example too similar to the third. The lack of rent did not stop officials from applying a higher tax band.
As more people turn to relatives in response to rising housing costs, cases at these boundaries are likely to become more common. The story of one man, his cousin and an unwelcome tax demand may be the start of a broader debate over how systems assess generosity within a family home.
Comments
No comments yet. Be the first to comment!
Leave a Comment