
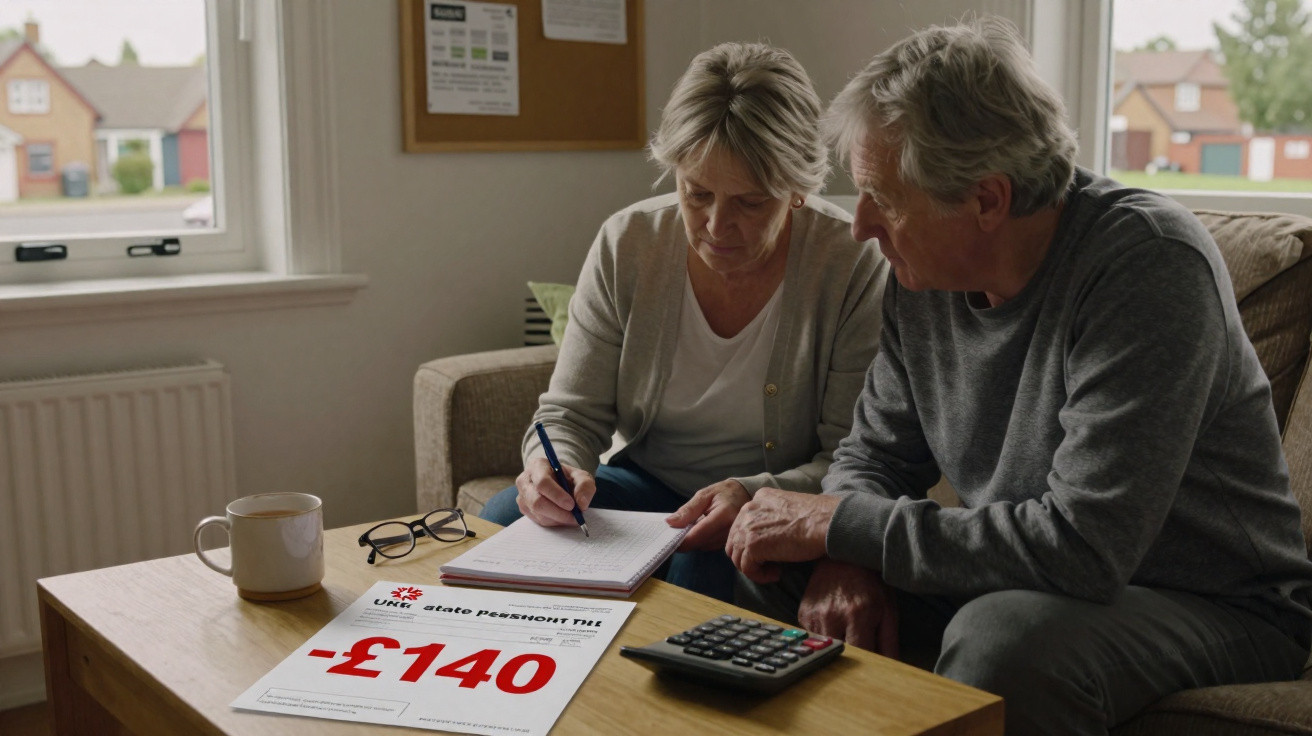
It can catch you in the most everyday moments. Standing at the supermarket checkout as the total climbs on the display far faster than your basket seems to justify. Or sitting at the kitchen table with a mug of inexpensive tea, reading a DWP letter that manages to be courteous and harsh in equal measure.
For millions of pensioners throughout the UK, that letter now delivers one shared message: a State Pension cut has been confirmed, and roughly £140 a month will disappear from household budgets from February.
It is not an indulgence. It is a boiler service, a food shop or a week’s heating.
The figures may be impersonal. Their consequences are not.
What does a £140 monthly cut mean in everyday life?
In a government spreadsheet, £140 may appear to be little more than a footnote. In real life, it removes an entire layer of financial safety.
A retired couple in Sunderland set out the sums on a notepad beside the kettle. That £140 covered their weekly grocery shop and internet bill, both gone at once. For a widower in Birmingham, the same amount paid for his bus pass, phone and the “little bits” that made his week feel human – a Thursday café breakfast and Sunday bingo.
This is not about giving up yacht fuel or skiing holidays. It is about losing ordinary life.
A recent calculation by independent analysts indicates that about 1.2 million pensioners close to the poverty line are likely to experience this reduction most severely. Many were already keeping bills afloat like spinning plates, using credit cards for council tax and boiler repairs rather than treats.
Most people know the feeling: opening online banking and sensing your stomach sink before your mind has processed the balance. For older people relying on fixed incomes, that stops being an occasional experience and becomes routine.
The State Pension has traditionally been presented as a basic agreement: pay in during your working life and receive enough to manage in old age. Reducing it by £140 every month does more than weaken that agreement; it calls it into question.
Behind the headlines sits a relatively stark rationale. The government cites increasing welfare costs, an ageing population and strain on public finances.
Its official position is that the change forms part of a “rebalancing” of support, intended to steer more people towards private savings and “personal responsibility”. Put simply, the State is retreating in the hope that families, savings and additional income will fill the gap.
In truth, hardly anyone manages this every day. Few people in their 20s, 30s or even 40s are saving enough to replace a State Pension that is getting smaller in full.
The cut makes explicit what many policy specialists have quietly said for years: the notion of one dependable pension safety net is gradually being dismantled.
How pensioners can adapt to the £140 State Pension cut
For most people, hearing “£140 less per month” prompts an immediate search for a pen. The modest household budget becomes a battleground.
A practical approach mentioned repeatedly is a list with three columns. The first should contain completely fixed costs – rent or mortgage payments, council tax and essential utilities. The second is for important but adjustable spending – food, telephone and transport. The third covers extras – subscriptions, treats and anything that can be put on hold.
Making yourself place each outgoing in one of those columns puts the hard reality of the cut on paper rather than leaving it in your mind. It cannot create money from nothing, but it provides a clear place to begin.
Many pensioners say the calculation is not the most difficult part; pride is. After paying in for an entire working life, applying for additional help can feel degrading, as though you have failed an unseen test.
But the understated reality is that billions of pounds in benefits remain unclaimed every year. Pension Credit, Council Tax reductions and help with energy costs are not handouts; they belong to a system that you funded through decades of taxation.
A frequent error is thinking that you “won’t qualify” because you own your home or receive a small private pension. Another is abandoning the process after a confusing form or a lengthy phone queue. The system is tiring by design, but that doesn’t mean you’re not entitled to support.
Listening to those experiencing this cut, the strongest feeling is often not anger but a particular form of exhaustion. It is the exhaustion of having to account for every pound and being told to “tighten belts” that are already on their final notch.
“People think you just stop spending when you retire,” says Margaret, 74, from Leeds. “But the bills don’t retire with you. The gas still goes up. The council tax still goes up. Only now, my pension is going down.”
When advisers and campaigners discuss coping with this new position, several small but practical actions come up repeatedly:
- Check whether you qualify for Pension Credit, housing support or Council Tax support, even if you believe you are on the borderline.
- Review direct debits and stop outdated subscriptions, duplicate insurance policies or services you no longer use.
- Speak to your energy supplier about hardship schemes or payment plans before arrears accumulate.
- Discuss modest, regular support with family early, instead of waiting for a last-minute crisis.
- Contact local Age UK, Citizens Advice or community centres for free benefit checks and assistance completing forms.
What the cut reveals about ageing, money and responsibility
Step back from individual household budgets and a different picture comes into view. The February reduction is not merely a change to a budget; it tells a story about how a country regards its older people.
For those still in employment, it acts as a warning signal. If a central State benefit can fall by £140 a month now, what form will it take in 10, 20 or 30 years?
For families in the so-called “sandwich generation” – raising children while concerned about elderly parents – it adds another burden to already overloaded shoulders. The question gradually moves from “Will the State look after us?” to “Which family member will be able to?”
The emotional divide is pronounced. On one side is a feeling of betrayal among people who planned retirement around a promise that now appears open to negotiation.
On the other is increasing weariness among younger workers, who are told they must contribute more, retire later, accept less and somehow make up for the holes created by reduced public services. Generational conflict makes an easy headline, but the reality is more complicated: many households are pooling money across three or even four generations simply to keep going.
The simplest sentence at the centre of this may be: the safety net is getting thinner, and we’re all going to feel it sooner or later. Whether you are 25 or 75, it is an idea that tends to stay with you.
The reduction also exposes a less visible division: the gap between people with assets and those without them. If you own your home outright, have a reasonable private pension and perhaps savings or investments, losing £140 each month is difficult but manageable.
If you rent, have health problems or spent your working life in low-paid, physically demanding work, £140 isn’t a trim, it’s an amputation. That divide is likely only to grow as younger generations encounter less secure employment, higher housing costs and weaker workplace pensions.
People are beginning to pose different questions. They are asking not only “How much will my pension be?” but also “What do I actually want my old age to feel like – and who is realistically going to fund that?”
| Key point | Detail | Value for the reader |
|---|---|---|
| - | Understand the £140 monthly State Pension cut from February | Helps you understand how and why your income is changing |
| - | Identify practical ways to rebalance your budget and claim support | Gives you specific actions rather than vague advice to “tighten your belt” |
| - | See the wider context around ageing, family support and future pensions | Enables you to plan ahead, speak openly with relatives and avoid unpleasant surprises |
Frequently asked questions
- Question 1: Why has the State Pension been reduced by around £140 per month from February?
- Question 2: Does this cut apply to everyone, or only to certain pensioners?
- Question 3: Can Pension Credit or other benefits help make up the shortfall?
- Question 4: What can I do now if retirement is still years away?
- Question 5: Where can I find free, reliable help to check what I am entitled to?
Comments
No comments yet. Be the first to comment!
Leave a Comment