
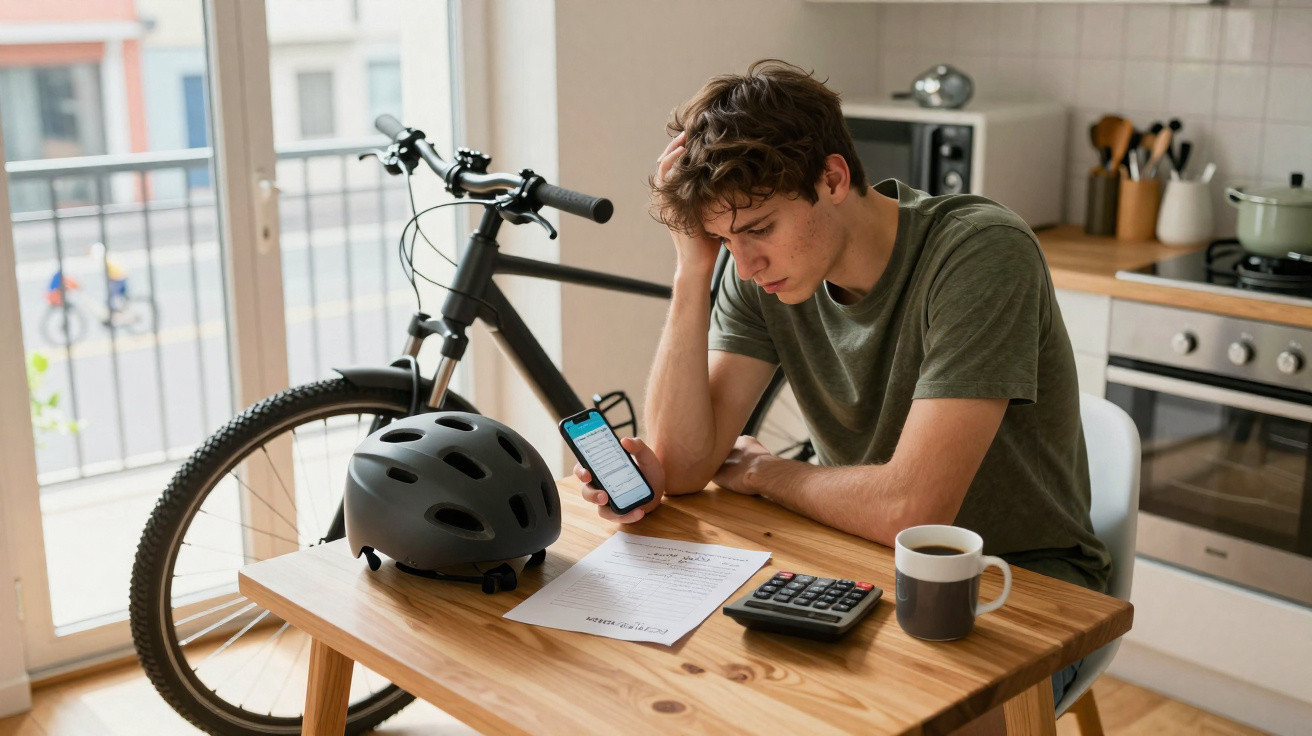
A casual favour between friends has become a tax problem, prompting uncomfortable questions about the point at which sharing turns into business.
A straightforward e-bike loan in return for a small contribution towards costs has resulted in a tax demand, an annoyed cyclist and a fierce online argument over how far authorities should intervene when people earn money from their own equipment.
From friendly favour to taxable income
The case attracting attention among cyclists and taxpayers concerns a man who purchased an electric bike for his everyday journey to work. The e-bike was expensive, but it enabled him to leave the car behind, shorten his commute and reach work without arriving soaked in sweat.
After a friend’s bicycle broke down, the commuter offered to hire out his e-bike on days when he was not using it. The proposal appeared uncomplicated: lend the bike, share operating costs and help a friend. The friend paid a modest monthly sum, well below a commercial hire charge.
The cyclist maintains that he is not operating a side hustle. As he sees it, the payments simply meet electricity costs, wear and tear, and part of the original purchase price. He argues that he is no better off at the end of each month than he was at the beginning.
The tax office saw things very differently: regular payments meant taxable income, even if the owner felt there was no “real” profit.
When the agreement came to the authorities’ attention - reportedly during a routine check of his finances - the tax office classified the monthly payments as rental income. This created a duty to declare the money received and, potentially, pay income tax on it.
When does sharing become a business?
The dispute highlights a grey area that can catch many people unaware. Throughout Europe, the UK and the US, increasing numbers of people hire out cars, tools, spare rooms and, increasingly, e-bikes to friends, neighbours or strangers.
Tax rules seldom take good intentions into account. Instead, they consider patterns, including frequency, regularity and whether money is transferred between people in an organised arrangement. In this case, the cyclist and his friend had an ongoing agreement, with money paid every month. That was sufficient to attract scrutiny.
Tax authorities generally treat repeated, organised rentals as income, even when the owner says they are just “sharing costs”.
Some readers regard this as excessive intervention. Others argue that conventional landlords and vehicle-hire businesses have to pay tax, so private small-scale rentals should not be wholly outside the system. For the cyclist at the centre of the case, however, it feels particularly unfair. He says that even if he stopped hiring out the bike, he would still have the same loan repayments to make.
Key factors that make small rentals taxable
- Regular, expected payments rather than isolated reimbursements
- A written or clearly understood agreement resembling a rental contract
- Finding “clients” through online platforms or adverts
- Charging beyond strictly demonstrable running costs
- Receiving payment from several people to use the same asset during the year
Depending on the rules in the relevant country, any mixture of these factors may push an informal arrangement into taxable territory.
“I’m not making any profit” – does that argument work?
At the heart of the cyclist’s frustration is his belief that tax should apply only to actual profit. He says the hire charge barely pays for depreciation, occasional tyre replacements and increased insurance costs. In his view, describing this as “income” does not reflect the real position.
Tax law generally applies a narrower, more technical definition of profit. Authorities will usually assess direct, evidenced expenses associated with the hire itself, rather than the full cost of owning the item. For example, they may permit a deduction for electricity used to charge the battery, but not the complete purchase cost of the bike at once.
This can leave a gap between everyday reasoning and legal definitions. Someone who believes they are merely recovering part of a sunk cost may nevertheless be regarded as receiving taxable income.
Just because the owner feels financially “no better off” does not mean the tax system sees zero profit.
Accountants say many people facing similar circumstances are taken aback by the result. They often misjudge when informal sharing begins to resemble a micro-business in the eyes of the law.
How tax offices are adapting to the sharing economy
The e-bike case forms part of a broader trend. As peer-to-peer platforms expand, governments are strengthening rules and monitoring small-scale rentals more closely. From short-term holiday accommodation to car sharing, tax offices are seeking to prevent income from slipping through gaps in the system.
In certain countries, online platforms are now required to report users’ earnings directly to tax authorities. Private arrangements may also draw attention when payments are made through traceable bank transfers or online wallets.
| Activity | Typical treatment by tax authorities |
|---|---|
| Occasional fuel money from a friend for a lift | Often ignored as casual cost sharing |
| Regular room rental via short-stay sites | Usually taxed as rental income |
| Ongoing e-bike or car rentals against a monthly fee | Frequently seen as taxable side income |
| Loan of personal items without money changing hands | Not taxable in most systems |
The cyclist’s experience strikes a chord because it conflicts with a widely held instinct: practical help between friends ought to be supported, particularly when it encourages lower-carbon travel. Tax systems, however, are based on equal treatment rather than on how friendly an arrangement may appear.
A debate that splits cyclists and taxpayers
Cycling forums and social media are deeply split. Some contributors say the cyclist understood what he was doing: he converted a valuable asset into a reliable revenue stream, and tax is therefore a fair outcome.
Others see the ruling as bureaucratic overreach. They refer to government initiatives encouraging cycling and low-carbon transport. From that perspective, penalising someone for getting more use from an e-bike appears inconsistent.
Supporters of the cyclist say the tax rules are out of step with climate goals and new ways of sharing expensive kit.
The disagreement reveals a wider policy issue: should tax rules become more flexible to promote sharing, or remain firm to safeguard the tax base? At present, the cyclist at the heart of the dispute feels trapped between those unresolved positions.
What casual e-bike lenders should know
For readers who own e-bikes or other costly equipment, this case offers a warning. Several steps may help to limit the risk of an unexpected tax bill:
- Keep arrangements genuinely infrequent rather than monthly or long-running
- Restrict payments to transparent, evidenced expenses, such as electricity or particular repairs
- Retain simple records of dates, sums received and the reasons for them
- Check whether your country has a small “trading allowance” or tax-free limit for minor side income
- Speak to your insurer, since paid rentals may invalidate standard bicycle insurance
Some tax systems offer restricted exemptions for very small earnings. In some jurisdictions, for instance, the first portion of side income received in a year may be disregarded. This may not remove the requirement to declare it, but it can reduce or even eliminate the tax due.
Scenarios that might trigger tax on your gear
Consider three cyclists in different situations:
- Anna occasionally lends her e-bike to a neighbour when the neighbour’s car breaks down. She does not accept payment, although she may receive a bottle of wine from time to time. This is more likely to be seen as private generosity than income.
- Ben charges a colleague a small sum every Friday to use the bike for errands, with payment made through a banking app. The arrangement is regular, traceable and straightforward to add up. Tax authorities could treat it as income, even where the sums are small.
- Carla advertises her e-bike on a rental platform and receives dozens of bookings each year. This is highly likely to be regarded as business activity, with clear tax responsibilities.
These scenarios illustrate that frequency, organisation and visibility can matter at least as much as the amount paid.
Key terms and risks people often overlook
Two terms appear repeatedly in discussions of this case: “cost sharing” and “benefit in kind”. Cost sharing generally means dividing a bill so that nobody makes a financial gain. Benefit in kind describes a non-cash advantage received by someone, such as free use of a vehicle, which can be taxable under certain rules.
Many cyclists who lend out e-bikes also overlook the legal implications if there is an accident. Once payment is involved, the relationship appears less like a favour and more like a service. If the borrower crashes, issues around liability, insurance cover and safety checks may arise alongside the tax question.
Mixing friendship, money and expensive equipment can create a trail of financial and legal consequences that no one intended at the start.
The story of the taxed e-bike rental underlines growing friction between informal sharing and formal tax systems. As equipment becomes more expensive and sharing becomes more common, more people will confront the same uneasy question: when does a friendly agreement quietly turn into taxable income?
Comments
No comments yet. Be the first to comment!
Leave a Comment