
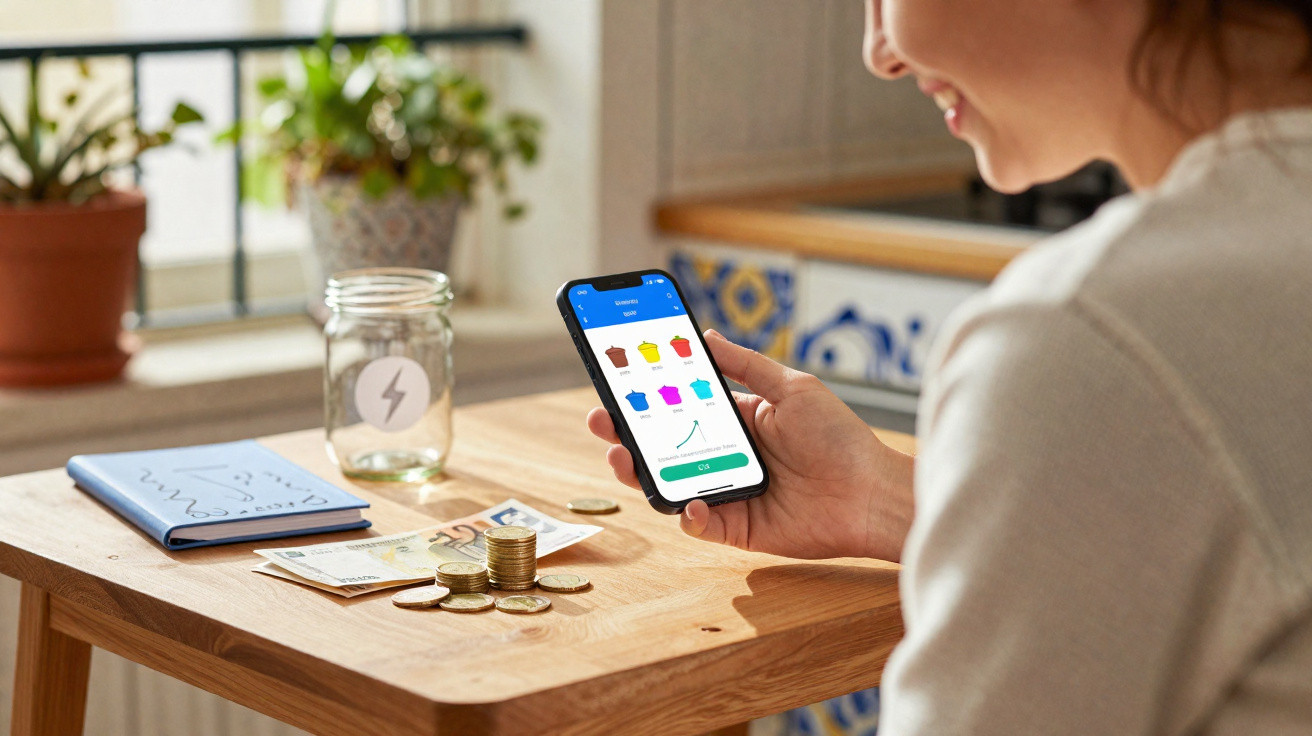
They grow when unremarkable habits become routine, when your cash shifts before your resolve starts to wobble, and when a tool gives you a prompt at exactly the right moment. I found that prompt in Monzo’s Pots, and it helped my rainy-day money build faster than any standard high-street savings account I had previously used.
One wet Tuesday in March, I stared at my phone as if it were about to announce something dramatic. My salary reached Monzo at 00:07 and, at 00:08, small transfers began racing into colourful Pots. Rent went to the Bills Pot. Grocery money was set aside. My “oh no” money-my emergency fund-was moved away before I could start thinking about a cheeky takeaway. It felt as though I had employed a discreet overnight accountant who never passed judgement. By the following morning, I could see a figure I had not seen before: a buffer that felt real rather than hopeful. During that first week, I realised this potting approach was growing my emergency fund 15% faster than my former high-street system. The secret was not interest; it was choreography.
When Monzo Pots changed the script
I did not move banks for better rates or flashy features. I changed because my old one-account setup allowed everything to blur together. Payday would arrive, I would do the sums in my head, and then spontaneous spending and bills would compete inside one chaotic balance. Monzo Pots separated those impulses. Emergency money had a protected place instead of being whatever was “left over if I behaved”. That visual divide made me save like a saver without making me live like a monk. In the first month, I spotted something unexpected: I looked at my Pot balances as runners check their pace-interested rather than ashamed.
Here is the practical part. Round-ups sent 23p, 41p and 79p into my Emergency Pot each day, like a tap dripping in reverse. Salary Sorter transferred a set portion at midnight on payday, without any fuss. I also made an automation in Monzo: whenever I spent money at a bar, £2 moved into the Pot-a small tax for my future self. Over eight weeks, my balance grew 15% more than it had over the same period with my old bank. Monzo had not created extra money; the structure simply stopped me dipping into it after a long Friday night.
There is a reason this setup works. Pots add friction where it helps and make movement effortless where it does not. Your emergency money is separated by design rather than by self-control. Each payday, cash moves behind those barriers before everyday life can steal your attention. Since Pots are visible, named and tied to goals, a loose intention such as “save more” becomes something tangible to defend: “Oh-No Fund, £1,000 target”. When you are building your first layer of security, behaviour matters more than yield. Interest is the extra; the system is the main event.
The Monzo Pots strategy I followed
The first step was choosing names. I set up three Pots-Bills, Groceries and Emergency-along with a slightly cheeky “Guilt-Free” Pot for small indulgences. I then used Salary Sorter to divide my pay the instant it arrived: fixed sums for Bills and Groceries, a percentage for Emergency, and a small amount for treats. I enabled round-ups on every card payment and added a multiplier at weekends. All at once, the Emergency Pot was no longer an ambition; it was a regular payment to my future self.
Then came the sweep. The day before payday, I did a “Zero Day” clear-out. Whatever remained in my main account went immediately into the Emergency Pot-money I had not expected and did not miss. I also connected a virtual card to my Guilt-Free Pot for wants rather than essentials. Once the Pot was empty, the spending for fun stopped. There was no spiral of guilt, only a helpful limit. Honestly, nobody maintains this manually every day. That is why the rules and labels do the hard work when motivation decides to have a lie-in.
I steered clear of two mistakes: choosing targets so ambitious that they failed in the second week, and treating things such as Black Friday as “sort of emergencies” worth raiding the Emergency Pot for. Whenever I felt tempted, I added small automatic prompts.
“Payday is a decision point. Decide once, automate forever. You can’t overspend money you never see.”
I also kept a short checklist in my pocket to maintain the routine:
- Give Pots real-world names: “Oh-No Fund”, “Rent”, “Food”.
- Sort your salary as it arrives, not after your morning coffee.
- Round up each card transaction and use a weekend multiplier.
- Pay any leftovers to yourself on the day before payday.
- Treat the Emergency Pot as “break glass only”.
What changes when your money moves before you do
There is a reason this approach feels so different. Everyone knows the feeling of a bill arriving and their shoulders rising towards their ears. With potting, the money for bills sits separately, like plates on a draining rack-already clean instead of waiting in the sink. The inner question shifts from “Can I afford this?” to “This has already been covered.” That sense of calm is the compound interest of good behaviour. Once it appears, saving stops being a battle and becomes background music.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Automate on payday | Use Salary Sorter to move fixed and percentage amounts into named Pots as soon as money arrives | Creates momentum before willpower weakens |
| Layer micro-savings | Use round-ups, weekend multipliers and small “taxes” on fun spending | Converts daily spending into consistent growth |
| Protect the emergency boundary | Keep a separate Emergency Pot and avoid using it for “almost emergencies” | Keeps your safety net in place when life happens |
FAQ:
- What do you mean by “15% faster”? I compared eight weeks of growth using Pots, round-ups and payday sweeps against eight weeks with my old high-street setup. The potting system pushed my balance 15% higher over the same period, mainly because of behaviour rather than the rate.
- Do I need Monzo Plus or Premium for this? No. The essentials-Pots, Salary Sorter and round-ups-are available with the standard account. Paid plans offer additional features, but the core habit-building system is free.
- Is this about interest or psychology? Both matter. Rates certainly help, but the main benefit came from automatic rules that prevented me from spending money I had intended to save.
- What if my income is irregular? Use percentages rather than set amounts, and carry out manual “sweeps” after every payment. Smaller, regular transfers work better than grand one-off efforts.
- How big should the Emergency Pot be? Traditional guidance suggests 3–6 months’ worth of essentials. Begin with one month of bills and groceries, then build from there. Tiny steps count if they happen every payday.
Comments
No comments yet. Be the first to comment!
Leave a Comment