
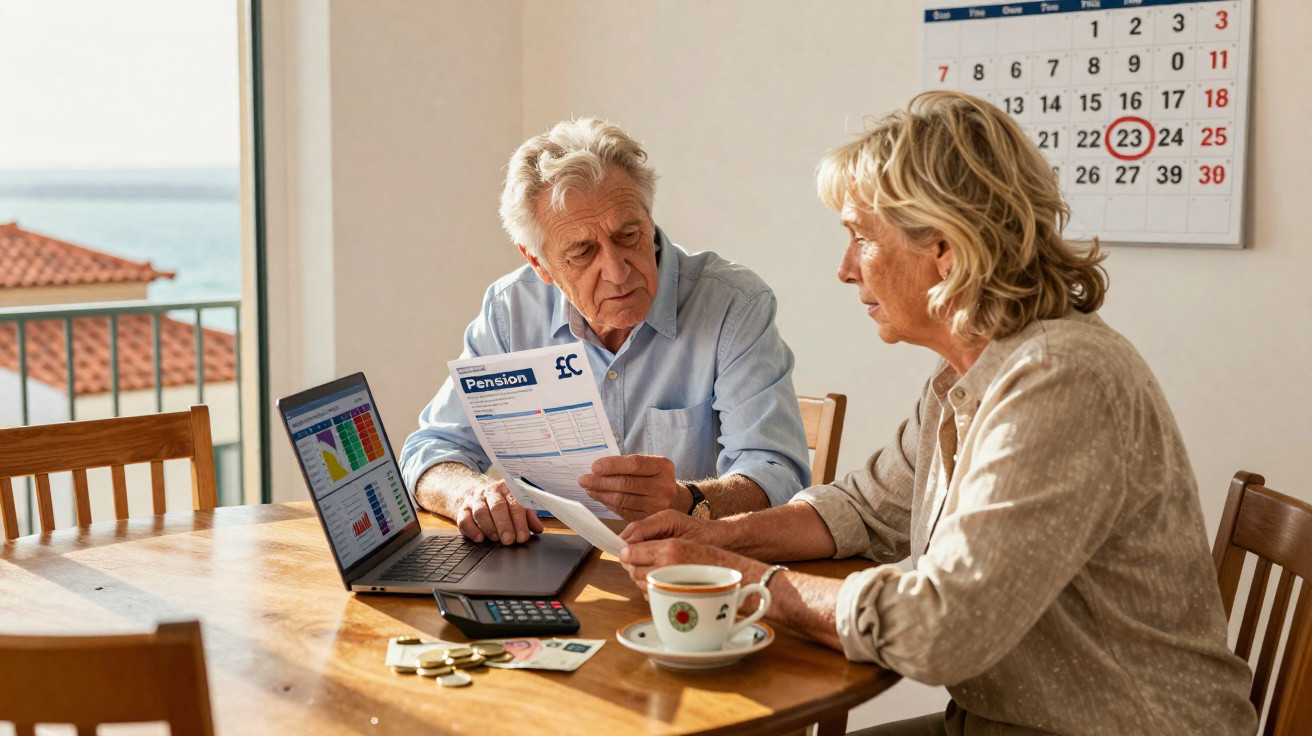
Margaret, 69, was sitting at her kitchen table in Leeds when she opened an email headed “Changes to your pension from 2026”. It was written in the chilly, orderly style large organisations favour. She read the subject line twice: new rules, possible adjustments, review your plans.
Her eyes moved to the calendar on the fridge, with birthdays circled in red and a pencilled reminder of the Scarborough weekend she had been saving towards. All at once, those modest plans seemed uncertain. Figures on a screen, decisions made in Westminster, and ordinary life caught between them.
Similar messages are reaching millions of retired people across the UK. Some briefly scan them before deleting them; others feel their stomach tighten; some panic privately while acting as though nothing is wrong. One point is increasingly hard to ignore.
This is not merely about pension paperwork – it is about what “retirement” will actually mean by 2026.
Why the pension landscape is shifting before 2026
Visit a café on a weekday morning and the conversation around retirement has changed. There is less discussion of cruises and more concern about whether the heating will still be affordable if pension income falls behind. People can sense movement in the system. State pension arrangements, private pension pots and tax thresholds are all changing while the cost of living has become painfully tangible.
The coming years look likely to mark a watershed. The apparently generous triple lock is facing increasing strain. Auto-enrolment schemes have now had time to develop, but many savers have accumulated less than they had hoped. As people live longer, pension income has to last for more years, while inflation steadily reduces the value of what once appeared to be a respectable retirement sum.
Behind the headlines sits one straightforward worry: by 2026, what if the safety net is not quite where people believed it would be?
Consider the state pension first. For years, the triple lock – the commitment to increase payments by whichever is highest of earnings growth, inflation or 2.5% – has been a prized political policy. But it comes at a high cost. With public finances under pressure, economists and think tanks are openly discussing alterations, reductions or a move to a “softer” form of the lock.
Even a modest adjustment to the calculation could amount to thousands of pounds less across an ordinary retirement. For somebody whose income is largely dependent on the state pension, that could be the difference between topping up the gas meter without concern and continually calculating costs while shopping for groceries. Many people still do not appreciate how heavily their future income can depend on a few lines in a Budget announcement.
Private and workplace pensions are not protected from change either. Automatic enrolment brought millions of people into pension saving, but contribution rates are frequently insufficient. Career interruptions caused by childcare, illness or caring for parents have also left many people with incomplete pension records. By 2026, the government is widely expected to advance reforms concerning matters such as minimum auto-enrolment contributions, the age when people are “nudged” into saving, and the degree of retirement flexibility schemes must provide.
There is a complication: additional flexibility may feel reassuring initially, while producing gradual losses later. Some people withdraw funds too rapidly, choose unsuitable investments or retain too much cash as inflation diminishes their pension pot. Pension withdrawal tax rules and lifetime limits are also continually being reviewed, so a change in either could quickly make a plan that seemed prudent yesterday appear far less wise. Many retirees may not notice the consequences until several years have gone by.
How many retirees could lose out – and what can be done now
Before 2026, one especially useful step is to set out, in clear language, exactly where retirement income is expected to come from and how changes to the rules could affect every source. This does not require a complex spreadsheet. A simple paper list is enough: estimated state pension, workplace pensions, personal pensions, savings, and any income from rent or part-time work.
For each source, make a note of three points: when you expect to access it, how it is taxed and what might realistically change. If the state pension age rises again for younger groups, for example, could that leave an income gap? If a future government reduces tax-free allowances, could your drawdown plan unexpectedly result in a higher tax bill? This sort of outline may not be exciting, but it transforms general anxiety into something that can be changed.
After that comes the uncomfortable question: “If my income were 10% lower than I expect, what gives?” Asking it alone can help prevent unpleasant shocks in the future.
The most common errors people make ahead of a period of pension reform are, strangely enough, very human ones. They disregard provider letters because the wording seems unfamiliar. They believe the planning stage ended when they retired. Or they rely on outdated rules they vaguely recall from a friend’s comment or a newspaper headline. All are understandable responses, but over 20 or 30 years they can prove dangerously expensive.
There is pride involved as well. Many older people are reluctant to say they find new pension products or online portals confusing. They politely agree when somebody refers to “drawdown” or “lifetime allowance”, then continue exactly as they did before. On a difficult day, shame about money can weigh as heavily as worry about money.
Let us be honest: nobody really reads every line of an annual pension statement or models five different possible outcomes. That does not mean you are destined to lose out, however. Small, targeted steps are more effective than ambitious, flawless plans that you will never maintain.
One financial planner in Manchester put it bluntly:
“The danger with the 2026 changes isn’t that people will be left with nothing – it’s that thousands will quietly end up with ‘just a bit less’ than they could have had, every single year, because they never matched their behaviour to the new rules.”
There is a route away from that gradual loss. Begin by asking your provider or adviser straightforward questions: “How would a change to the triple lock affect my income over 10 years?” “Am I at risk of paying more tax on my withdrawals if thresholds move?” “Is my pot too exposed to inflation?” You do not need to be fluent in pension jargon to raise them.
- Arrange one dedicated pension review each year, treating it with the same importance as a medical appointment.
- Store every pension letter in one physical folder instead of leaving them scattered through drawers and email inboxes.
- Make use of free services including the government’s State Pension forecast and Pension Tracing Service.
- Discuss openly with family what you expect and what could alter.
- When something is unclear, write your question down before the call and read it aloud exactly as written.
The emotional side of “losing out” – and why 2026 is a line in the sand
Most people have experienced the moment of discovering that the rules changed some time ago while they continued following the previous version. For many retirees, pensions now feel like that. They stopped working on the basis of one set of assumptions: the triple lock would remain, tax rules would be stable, inflation would stay moderate and markets would be favourable. Reality then moved on.
By 2026, the distance between those assumptions and the new rules could be painful. It will not necessarily be dramatic. More often, it may mean a delayed holiday, fewer trips out with grandchildren or reducing the food shop “just in case”. Such changes do not always appear in statistics, but they determine how retirement feels. This quiet narrowing of choices is among the cruellest types of financial loss.
Treating pensions as nothing more than arithmetic misses the essential issue. Retirement forms part of the story people tell themselves about the final third of their lives. Policy alterations and reforms, particularly where they are rushed or badly explained, can feel as though someone has rewritten the script halfway through a play. It is hardly surprising that so many people disengage. Yet that silence generally benefits only one side – and it is not the retiree.
There is another threat that receives less attention: tension between generations. While the government balances the costs of supporting an ageing population against pressure from younger voters, it may favour policies that restrain state pension growth or place greater responsibility on private saving. That does not inevitably mean catastrophe for existing retirees, but it does mean the former certainty – “the state will always look after us the same way” – has disappeared.
For people who have already retired or are approaching retirement, the next couple of years offer an opportunity to regain some control. This is not about protest slogans, but calm and practical choices: reshaping budgets around more cautious income estimates, considering part-time work through preference rather than sudden necessity, or making more imaginative use of housing wealth. These measures can reduce the impact if reforms prove tougher than expected.
The more people regard pensions as something living – requiring occasional care and attention – the less likely they are to be caught unprepared by 2026 and what follows. A retirement capable of bending is more likely to avoid breaking.
The larger issue is what sort of later life Britain wishes to provide for people who spent decades contributing. That discussion is already happening in Whitehall think tanks, on talk radio and quietly around kitchen tables from Aberdeen to Plymouth. The results will not be tidy. Certain compromises will hurt, while others may feel long overdue.
For the moment, the strongest action an individual retiree can take is to replace indistinct fear with specific understanding. Which rules are you dependent on? Which could change? How vulnerable is your present definition of “enough” if the triple lock is weakened, tax thresholds remain frozen for longer, or investment returns underperform?
The answers will differ from person to person, and they will not always be reassuring. But discussing that discomfort with a partner, adult children or trusted advisers can turn it into something more useful: a shared project. A plan that can adapt rather than a fragile hope resting on promises from the past.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Pressure on the triple lock | Reforms by 2026 could reduce the real growth of the state pension | Helps people prepare for state income that may be lower than expected |
| Changing private pension rules | Greater flexibility also brings a higher risk of drawing down too quickly or making poor asset allocations | Encourages a review of drawdown strategy before the rules change |
| Emotional and practical effect | Small annual losses can result in tangible day-to-day sacrifices | Provides a framework for adjusting budgets and expectations rather than simply enduring the impact |
FAQ:
- Will the UK triple lock definitely change by 2026? Nobody can be certain, but growing fiscal pressure and recent discussions make some type of adjustment fairly likely, particularly if inflation and earnings remain volatile.
- Could my existing state pension be reduced? Direct reductions to pensions already being paid are politically highly contentious and historically uncommon; the greater danger is slower future uprating, which gradually reduces spending power.
- Are private pensions safe from government changes? Regulation protects the money in your pension pot, but tax treatment, contribution rules and access ages can change, affecting how much you ultimately retain.
- Is it worth getting financial advice before 2026? For anyone with several pensions or a substantial pot, one advice session may pay for itself by preventing tax traps and plans that do not fit the new rules.
- What if I’ve left planning too late? It is seldom “too late” to make improvements: modest steps such as consolidating old pots, changing withdrawals or reviewing investment risk can still have a meaningful effect, even in your 70s.
Comments
No comments yet. Be the first to comment!
Leave a Comment