
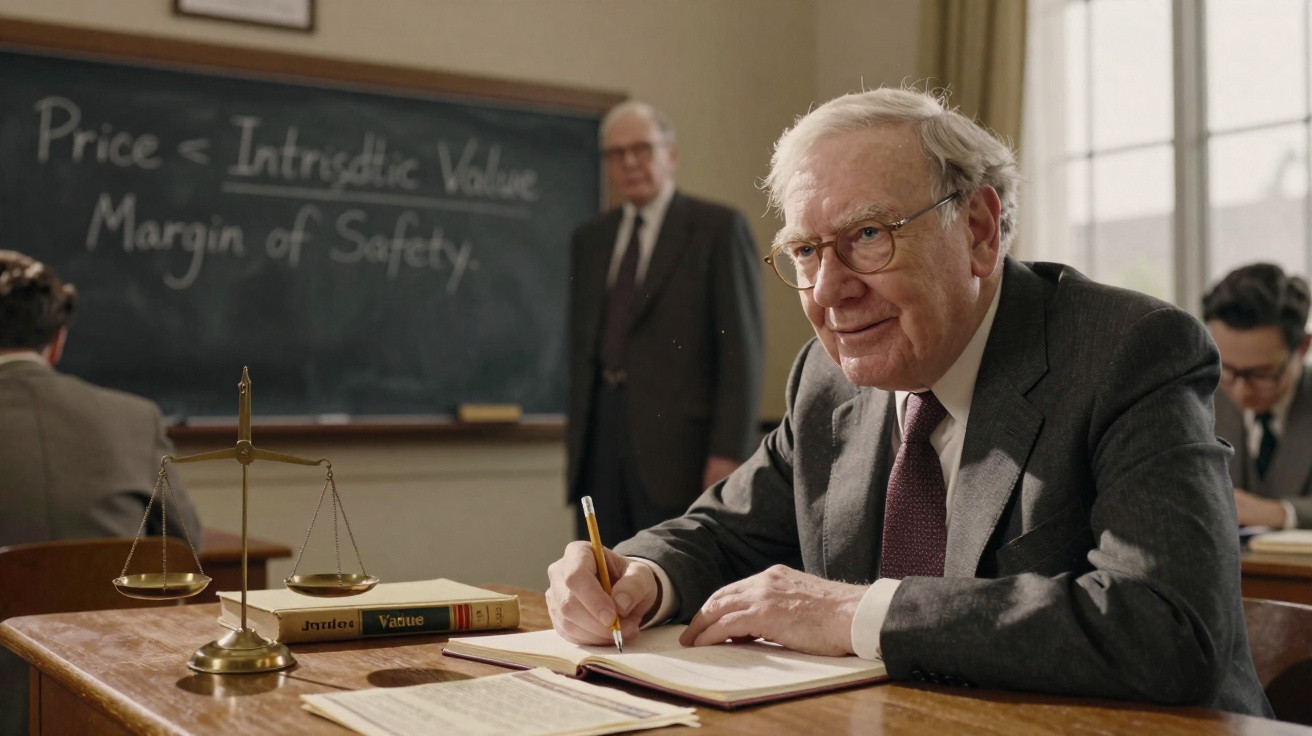
It is not the silence that settles over a spreadsheet, but the hush that follows when someone older and wiser begins to describe risk as though it has a life of its own. Imagine a modest lecture theatre in the late afternoon, with chalk dust suspended like a light fog. In the front row sits an exhausted student, fidgeting yet attentive. Between ticking wall clocks and open notebooks, a quiet notion altered the paths of lives and bank balances. It was neither showy nor a concealed stock tip. It was a different way to look at things. Once it enters your view, it stays there.
That notion is the unbroken line linking Benjamin Graham and Warren Buffett, and it may be the line you need right now.
The day the room changed
Warren Buffett recounts it in his understated Omaha drawl, as you might speak of a beloved teacher who never had to shout. At Columbia Business School, he was young and eager enough to pursue any share that seemed lively. Benjamin Graham then entered the room, set down his leather case and began discussing value as if it could be held and measured. Not price, but value. The distinction was almost shocking.
Graham did not speak like a trader. He came across more like a surveyor: someone meticulous about inspecting a building’s foundations before purchasing it. He discussed businesses as though they were farms, shops or railways whose tracks you could walk yourself. Cash, assets and earning power were what mattered. The stock market, he explained, would throw prices at you each day; the task was to remain level-headed. Amid scribbling pens and a hissing radiator, the definition suddenly became clear.
The principle with steel inside it
What Graham really meant
Graham’s central message was remarkably straightforward: establish a company’s intrinsic value, then pay substantially less than that figure. The difference between its worth and your purchase price forms a protective buffer against disaster. When your valuation is carefully considered and the discount is ample, the world can shake without knocking you down. That difference has a name: the margin of safety.
The single rule that survived every crash: demand a margin of safety. It is not glamorous, and it does not make compelling television. Yet when the lights dim and everyone heads for the same exit, that padding stops you being trampled. The market has no interest in how persuasive your confidence sounds; it cares whether you allowed room to make mistakes.
Why it calmed Buffett
Buffett was suited to this approach by temperament. He enjoyed calm calculations and the fulfilment of assessing ten-year records instead of attempting to forecast the coming quarter. Graham supplied language for an instinct Buffett already trusted: patience is stronger than panic. Being approximately right, buying below your own estimate and then remaining still felt like permission to quit the sprint.
This is value investing on a human scale. Rather than trying to forecast every raindrop, you construct a roof with enough overlap to withstand an unexpected shower. It is a grown-up idea in an immature market, which is precisely why it appeals to people able to tolerate some boredom.
Meeting Mr Market, the noisy neighbour
To make his lesson memorable, Graham created a character. Every day, Mr Market appears at your door with a quoted price. On certain mornings he is euphoric and would pay an absurd amount for your shares. On others, he is miserable and offers only pennies. You are not required to debate with him, cure him or demonstrate your intelligence. You need only use him when helpful and ignore him the rest of the time.
Most of us have watched a screen turn red and felt our pulse rise alongside it. Phones vibrate, headlines roar and, somewhere between the kettle and the kitchen table, fear leads you to press “sell”. Mr Market occupies that narrow space between thinking and acting. Graham’s lesson closed the gap. Regard daily prices as you would the weather: step outside when conditions suit you, and make tea when they do not.
Buffett adopted that parable as though it were a suit requiring no alterations. He demonstrated that the market’s mood is an instrument rather than an instructor. Price makes offers and value provides the anchor; hold one in each hand without allowing their roles to reverse.
What buying for less actually looks like
The mispricing you can smell
When people hear “buy a pound for 60p”, they assume it is a fairy tale. But then a scandal erupts, an industry becomes unfashionable, or a dull company acquires a nickname that invites the market’s mockery. American Express faced its salad oil scandal, while the figures for its underlying business still made sense. Washington Post appeared small only because the market failed to inspect its store of assets. Coca-Cola was a worldwide habit priced as if it were merely a drink. In every instance, the arithmetic of value differed from the drama of the day.
There is also something sensory about this work, if you allow it. Consider the muted thump of an annual report falling on a desk, or the paper scent of footnotes, where reality often hides. A chart may mislead you, but a much-handled set of accounts read with a pencil seldom will. In that stillness, you decide what the business is worth to a rational owner and wait for Mr Market either to panic or to lose interest.
How the margin carries you
Purchasing below value, with genuine breathing room rather than a tiny sliver of discount, gives you choices. If the future proves ordinary, you remain all right. If it is better than expected, you are pleased. Should one part of your assessment be wrong, the discount takes some of the impact. The margin of safety is not pessimism; it is optimism wearing a seatbelt.
Buffett’s evolution over time, from cigar butts to wonderful businesses at fair prices, did not remove Graham’s principle. It made it richer. A broad moat contributes to your safety as well. Reliable cash flows, honest management and straightforward products that people purchase even in bad weather all add strands to the net that catches you when a stitch is missed.
The hardest part is the waiting
In truth, hardly anyone manages this perfectly every day. We speak confidently about patience, only for our thumbs to expose us as we refresh a chart. The required discipline is almost household-like: select carefully, purchase carefully and then allow time to do its work. That unglamorous process powers fortunes which appear glamorous from the outside.
Brilliance is not essential; composure when the room is noisy is. There is a reason Buffett devotes more time to reading than to trading. Time and space for thought are a competitive advantage that costs nothing, although they can seem unfashionable. The margin of safety is more than a figure in a valuation model: it is also the room in your diary that you defend from other people’s urgency.
The modern dilemma: noise vs nerve
We now live inside a feed: alerts, charts, expert threads and the entire carnival. Everyone has an opinion, and most deliver it at volume eleven. That is a difficult environment for Graham’s quiet rule, as your attention is captured before your judgement has even had coffee.
For a UK investor, the temptation is to hand calmness over to a product: an ETF here, a robo-portfolio there, each useful within its limits. Yet the principle asks a more demanding question: do you understand what you own, what it is worth and how much slack you have created? It does not become a social-media trend because it cannot be squeezed into a hot take.
Margin of safety works across cycles and investment styles. It is not an argument between value and growth; it is a habit of survival. When sterling swings, interest rates leap and newspapers carry the scent of panic, the rule provides a small private room in which to think clearly.
A simple practice for this week
Choose a company you could describe to an intelligent teenager. Look for no magic or rockets, simply a business that makes or sells something you understand. Read its five most recent annual reports, then note the two or three factors that genuinely drive it. Ignore the headlines and focus on the elements that pay the bills.
Next, take an ordinary sheet of paper and set out your best estimate of its value as a range rather than one heroic number. Use sober assumptions, consider what may go wrong and insist on a discount that your future self would appreciate. If Mr Market offers a price below your range by a worthwhile amount, pay attention. If not, take a walk.
Price is not value. Say it aloud before you press buy. Teach your instincts to value the word “no”, because returns are often concealed there. Constant activity earns no prize. The reward comes from acting decisively at the right price, with a cushion already in place.
What makes this feel almost moral
Graham’s teaching involves more than mathematics. It is a stance towards the world. Businesses are created by people who turn up, report honestly through their figures and seek to serve customers without setting fire to the furniture. Purchasing at a reasonable discount does not punish them. Instead, it sets a limit against the market’s emotional swings, allowing you to become a more dependable partner.
That steadiness compounds into something almost tangible in a quiet kitchen: a portfolio that helps you sleep. There are fewer midnight scrolls, fewer nervous trades and less need to apologise to yourself. Life does not turn into a straight line, but it no longer feels like a fire drill.
Missteps, and why they don’t kill you
Nobody produces a flawless scorecard. Buffett ignored technology for years before eventually moving into it. He held some investments for too long, bought others too early and learned where everyone could see. A margin of safety makes those jolts a form of tuition rather than destruction. Recovery remains possible when you paid less than the business was worth.
At times, you will underestimate just how strange the world can become. That is acceptable. The remedy is not larger spreadsheets but wider margins. Demand a greater gap when you are tired, excited or have just read a clever thread. Excitement undermines price discipline. Sleep on it, then measure twice and cut once.
The human bit we rarely admit
Most people do not truly want a portfolio. They want a story they can trust when rain begins falling and headlines start to howl. Graham’s principle offers a story with backbone. You completed the work, paid less than the asset was worth and left room to be mistaken. That is a narrative you can carry through a chaotic week.
There is a subtle sound that signals you may be doing it properly: silence. It is the silence of not looking at your phone every ten minutes, and of a watchlist that is largely waiting. Patience is a position. From the outside it appears passive; within, it is as active as a heartbeat.
What Buffett carried forward
Buffett did not idolise Graham. He took in Graham’s teaching and then followed his own route, choosing stronger brands and broader moats. The principle stayed with him throughout. He continues to ask what an asset is worth to a sensible owner and how large his cushion is. He also continues to treat Mr Market as a servant rather than a guide.
That is the element that stretches from a student’s desk to Berkshire Hathaway’s annual meeting. The decimal points may differ, but the stance remains unchanged. At the heart of every major decision is the same agreement: buy with a margin of safety, then continue with your life while compounding performs its slow, modest ballet.
If you remember one picture
Imagine standing outside a shop window in drizzle, looking at a jacket you have wanted for some time. You understand what it is worth to you. A sale finally brings it within your range. You do not argue with the rain or the mannequin’s expression. You purchase it, smile and leave. At all other times, you simply walk on by.
The market is more crowded than a high street at Christmas, yet the logic of buying is identical. Understand the value, wait for the discount and require the cushion. Then use the item for years. The investment principle Benjamin Graham taught Warren Buffett is not a spell. It is a steady hand on your shoulder when the world becomes loud and, if you allow it, it can transform your money life from a chase into something quietly and stubbornly sane.
Comments
No comments yet. Be the first to comment!
Leave a Comment