
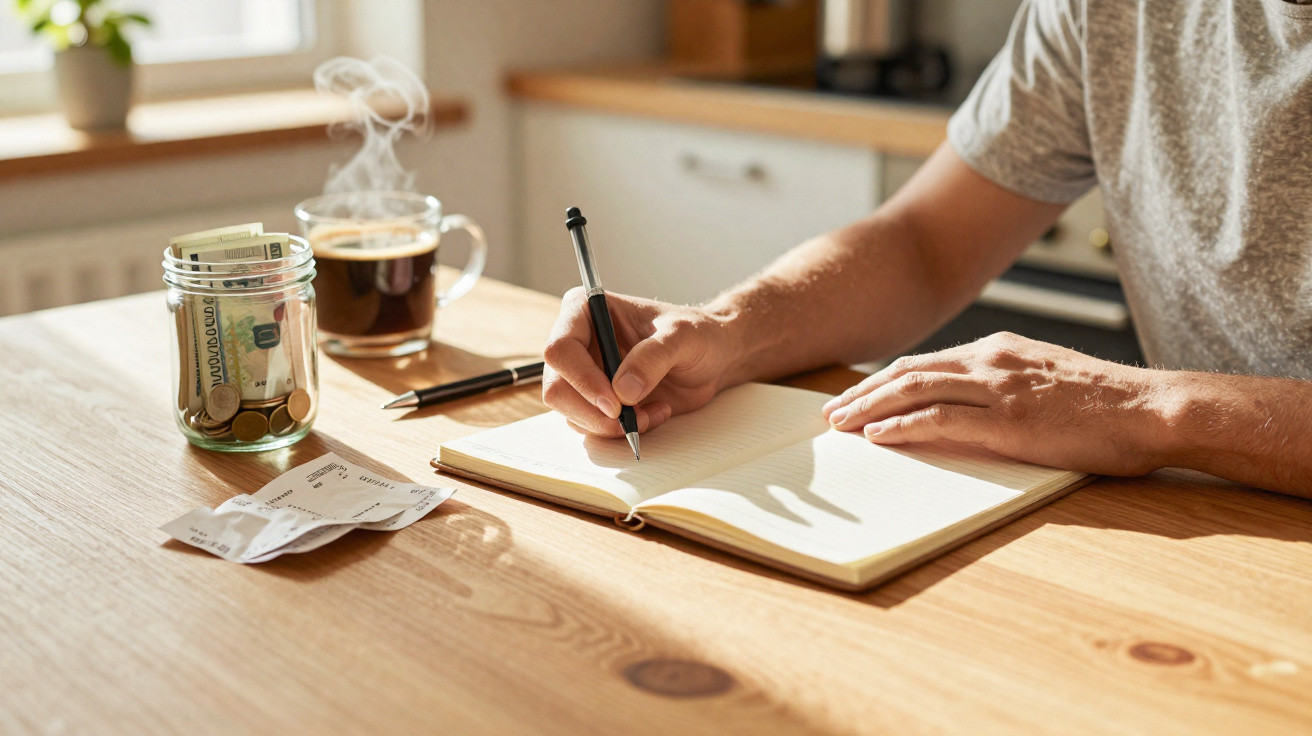
The alert appeared at 9:14 p.m. Your banking app helpfully reported that you had spent £14.90 on “FOOD & DRINK”, as though that told you anything useful. You looked at the label on your phone while the half-finished poke bowl beside you went cold. On paper, you were “within budget”. In reality, you still could not say where your money was disappearing to.
Most of us know that feeling: checking our balance and wondering whether somebody else has been spending our wages.
Budgeting apps offer the promise of clarity, charts and control. You download one, categorise several payments and feel responsible for a week. Then everyday life takes over, alerts accumulate and the colourful charts become little more than background decoration.
Yet people who steadily make financial progress often rely on something far simpler.
The low-tech trick that quietly beats most budgeting apps
Ask financially relaxed people how they monitor their spending and a familiar pattern emerges. Rather than enthusiastically recommending the newest app, they mention a notebook, a basic spreadsheet or a battered piece of paper tucked into a wallet.
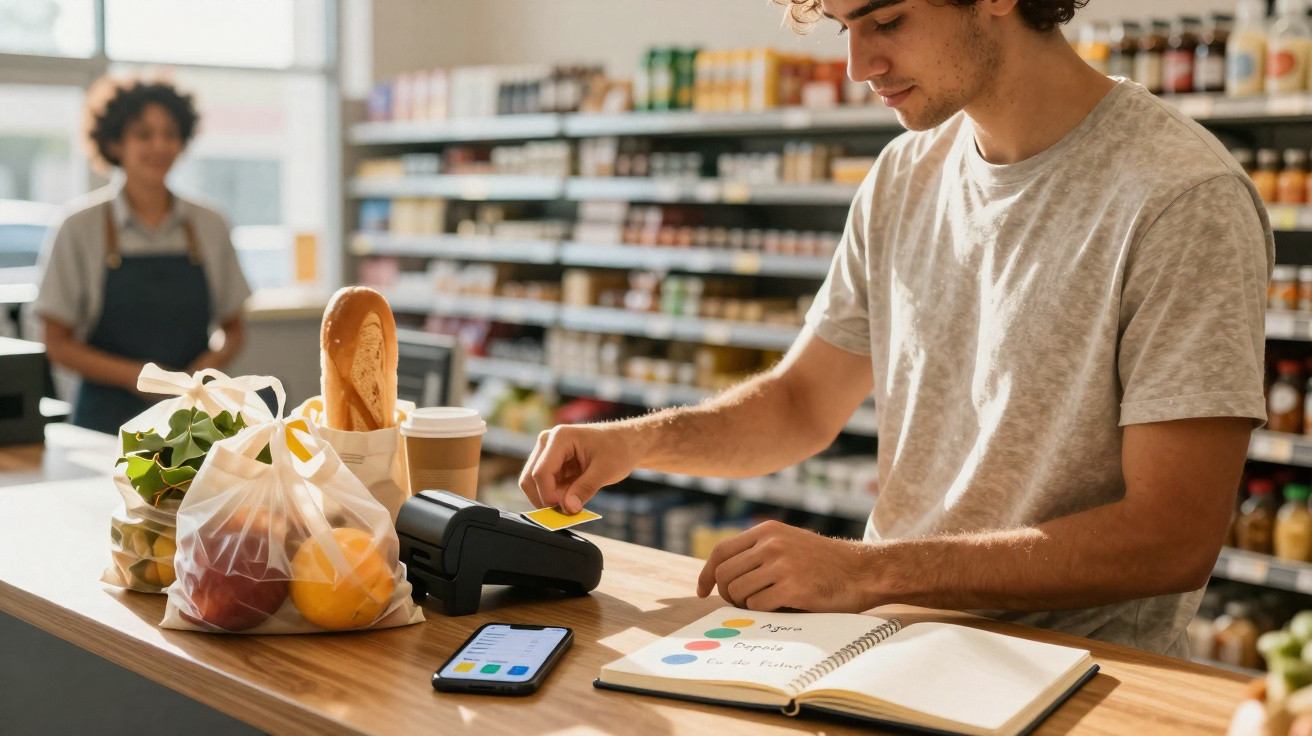
The approach is almost painfully straightforward: whenever they spend money, they record it. Not a few days afterwards, and not “when I have time on Sunday”, but immediately after tapping a card or pressing “confirm”. One short line: the amount, what they bought and perhaps a brief note.
No charts. No AI. Only you, the figure and a pen or keyboard.
Consider Maya, 32, who has a solid marketing salary but still felt short of money by the 20th of each month. She had tested three budgeting apps, each with friendly icons and “insights”. She would link her accounts, look over the pie charts and then… order a takeaway regardless.
One December, following another overdraft charge, she found a pocket notebook in a drawer and wrote “January – Every cent” on its first page. On 2 January, she noted a £3.50 coffee. On 3 January, a £2.10 bus journey. On 4 January, a £27 “quick drink” that became four cocktails.
By the end of that week, the page resembled a confession. No algorithm was needed to show her where the money was leaking away.
This low-tech form of tracking succeeds because it demands the attention that apps attempt to automate away. When an app sorts transactions into neat categories, it can also soften the impact. “Food & Drink: £412” feels remote. “£41, random snacks and ‘I’m tired’ treats this week” lands rather differently.
Recording purchases restores friction. That small gap between using your card and entering the expense works like a speed bump. You will not stop spending altogether, but you begin to spot patterns that your banking app discreetly conceals.
The straightforward truth is that most people do not need increasingly complicated tools; they need more honest contact with their own figures.
How to use the one-line log to change your spending behaviour
This is the precise method that repeatedly appears in accounts from people who finally feel in control of their spending. Choose a single place to capture expenses: a small notebook, a notes app or a very simple spreadsheet. Use only one. Then stick to one rule: every purchase gets one line.
Include the date, the amount and a brief description. “03/04 – £7.80 – lunch sandwich”. “03/04 – £25 – taxi, late and raining”. Nothing more is required. Avoid colours and categories at the beginning. For at least two weeks, keep it as plainly simple as possible.
At the end of the day, briefly look back over the page or column. This is not about judging yourself. It is simply a way to view your day through the trail left by your money.
People tend to stumble over the same obstacles with this approach. They try to build a flawless system from the first day, creating ten categories, colour schemes and rules. Within two days, they are worn out and abandon it. Or they miss entering one purchase and decide the whole process has failed.
In truth, nobody keeps this up perfectly every day for their entire life. You will overlook a coffee here or a parking ticket there. That does not weaken the method. What matters is that most of your spending moves through your awareness, rather than only through your bank’s servers.
If it starts to feel like homework, you have taken it too far. Return to: date, amount, what it was.
With time, the log quietly shifts from being about guilt to being about choice. You start to recognise where you truly want your money to go and where habit has been taking the wheel.
“Once I had to write ‘£68 – random Amazon stuff’ three times in one month, I couldn’t unsee it,” says Ben, 41. “My budget app had always shown ‘Shopping: £200’, but that never hit me in the gut like those three lines did.”
If you would like a little more structure afterwards, add a small weekly review ritual. Read through your entries and mark what felt worthwhile and what did not. Rather than conducting a full analysis, keep it easy with this checklist:
- One expense this week I’m proud of
- One expense that was pure autopilot
- One thing I’d like to do differently next week
- One small habit that would change a lot if repeated
- One number this week that surprised me
Why this “boring” habit quietly changes your future
What is seldom said openly is that money anxiety is not solely about figures. It is also about feeling that life is happening to you, with your bank balance as the evidence. A basic spending log reverses that feeling in a way that apps often cannot.
Instead of waiting for a monthly alert to announce that you have exceeded your budget, you are there at the moment, pen in hand, each time you spend. That awareness creates a calm confidence: you may still spend too much on certain days, but you are no longer unaware.
Across several months, the lines on the page begin to tell a deeply personal story. Not “average user spending trends”, but your routines, your stressful days, your joyful days and those “I gave up and ordered delivery again” evenings.
| Key point | Detail | Value for the reader |
|---|---|---|
| Low-tech tracking beats passive apps | Recording every expense creates useful friction and awareness | Offers a genuine sense of control without complicated tools |
| One-line-per-expense method | Date, amount and a short description, entered as close to the purchase as possible | Makes spending visible and simple to review in minutes |
| Weekly micro-review | A brief reflection on what felt worthwhile versus autopilot spending | Slowly changes habits without severe restriction |
FAQ:
- Do I have to write down absolutely everything I spend? Record as much as you can realistically manage, particularly variable costs such as food, transport and leisure. Missing an occasional item will not undermine the method, provided that most purchases pass through your awareness.
- Isn’t this just the same as using an app, but slower? Not quite. Apps automate the process and remove friction, whereas this method deliberately uses it. Physically entering each expense is what alters your relationship with spending.
- How long before I start seeing results? Most people notice patterns within a week, while behaviour often begins to change within a month. Larger financial improvements, such as clearing debt more quickly, generally become visible after a few consistent months.
- What if I hate notebooks and love my phone? You can absolutely use your phone. A basic notes file or stripped-back spreadsheet works well. The important part is entering every expense yourself instead of allowing an app to import everything automatically.
- Do I still need a formal budget if I do this? You can, although many people find that a clear spending log naturally develops into a flexible budget. Once you know your real figures, setting approximate limits for categories feels far more grounded.
Comments
No comments yet. Be the first to comment!
Leave a Comment