
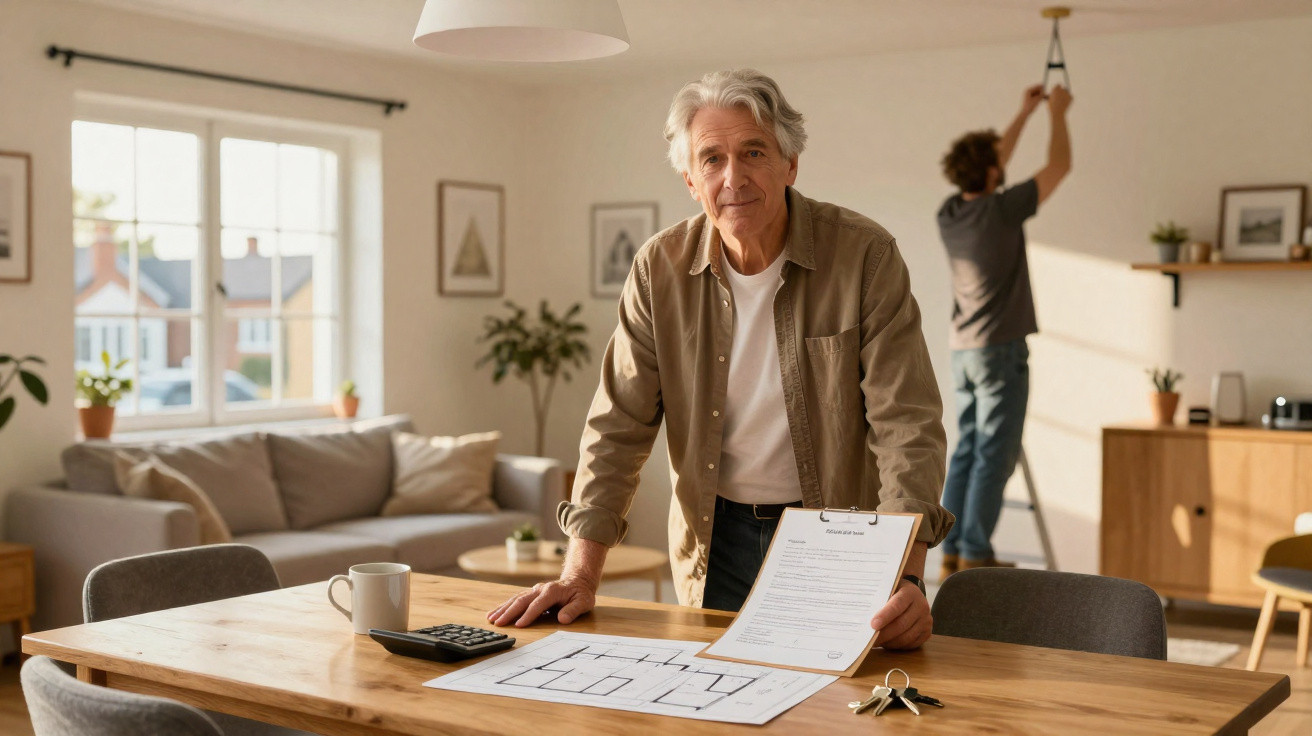
Peter, 74, stands in the centre of his newly painted Kent kitchen, brushing his fingers over the cool quartz worktop as though it might break.
The boiler has been replaced, the windows now keep out the draughts, and the bathroom has a walk-in shower that his knees appreciate every morning. He did not borrow the money. He did not dip into his children’s savings. And he certainly did not win the lottery.
Over the fence, a neighbour asks the question everyone is thinking: “How on earth did you pay for all this?” Peter simply smiles - the smile of someone who made a frightening choice that quietly transformed everything.
He chose a financial option that many Britons still view with suspicion, or avoid entirely.
A 74-year-old, a worn-out house and a quiet financial shift
Peter bought his three-bedroom semi-detached home in 1982 for a sum that now seems tiny. It had orange carpets and an overgrown garden, but it was his castle. As the years went by, however, the roof started to fail. The wiring belonged in another era. The bathroom became less a place to unwind and more an assault course.
He had brought up two children in the house, lost his wife, and seen neighbours arrive and leave. It held a lifetime of memories, as well as problems he could no longer put off. His pension was enough for the essentials, but conventional borrowing felt dangerous at his age. Even so, he wanted one final major improvement: to live comfortably rather than merely “manage”.
His daughter then mentioned a term he had previously heard only in adverts during television quiz shows: equity release.
One grey Tuesday, Peter sat at his kitchen table with a financial adviser. Documents, charts and initially baffling figures were laid out before him. Peter listened with folded arms and a healthy dose of scepticism. Could he access money tied up in his home without selling it or moving? Could he make no monthly payments, with the interest added up and settled only when he died or moved into care?
It seemed smart, but it also felt like a con. Equity release adverts tend to show smiling grey-haired couples walking along a beach. Real life is seldom so polished. But the adviser showed Peter real figures: his home was worth about £425,000, with no mortgage outstanding. He could potentially release roughly £90,000, with protections ensuring that he would never owe more than the property’s value.
He did not take the maximum sum. Instead, he released enough to replace the roof, update the kitchen and bathroom, and install insulation. Then he waited to find out whether disaster would follow.
Equity release, particularly lifetime mortgages, is an option many older Britons instinctively reject. It touches a powerful belief: that the family home is a legacy and that you should “leave the house to the kids”. In a country where outright ownership is seen as a mark of achievement, drawing on that value can feel almost like an admission of failure.
Yet the reality is stark and straightforward. Many older people are “asset rich and cash poor”. Their wealth is locked in bricks and mortar while their boiler struggles on, the stairs become harder to climb, and the bathroom turns into a daily hazard. Peter’s home was worth more than ten times its original purchase price, but his bank balance had not risen in the same way.
By accessing part of its value, Peter was effectively asking his home to give something back. He was not taking in tenants or selling up; he was using a little of tomorrow to make today better. To him, that felt like dignity rather than debt.
How Peter used equity release - and the questions people often miss
The glossy leaflet was not what changed Peter’s mind. It was a spreadsheet his daughter created on her laptop. Together, they entered his age, the possible release amount, estimated interest rates and an assumption about how long he might live. They were not being gloomy, merely practical. How much might remain for the children, and how much more freedom could he have now?
Peter selected a lifetime mortgage with a flexible drawdown facility. In other words, he did not receive all the money at once. He took an initial amount for the urgent work - the roof, electrics and heating - while leaving the rest available should he need it later. Interest accumulated only on the funds he had actually drawn, rather than on the entire approved amount.
He also chose a plan that permitted optional interest payments. He does not make one every month. When he can comfortably afford it, he pays a small sum to stop the interest building too quickly. Some months, he doesn’t pay a penny and doesn’t beat himself up for it.
Many people will understand that uncertainty: the wish for comfort today, alongside the fear of feeling guilty tomorrow. In a cul-de-sac near Peter’s, another couple in their late seventies keep the heating down and their curtains shut to “save a bit”. Their home is valued at almost £500,000, yet their savings would not pay for a replacement boiler.
They say equity release is not for them because “it’s how the kids will get on the ladder.” When their 45-year-old son, who rents, hears this, he shrugs. He would prefer them to be safe and warm than preserve property wealth for his eventual inheritance. On paper, their position resembles Peter’s; emotionally, it could not be more different.
Figures tell one version of the story. Love, duty and unstated family expectations tell another. The decision lies somewhere between them: use the home to make later life better, or protect it as an inheritance while accepting a more precarious present.
The equity release industry has changed over the past decade. Tighter regulation, no-negative-equity guarantees, compulsory advice and more adaptable products have gradually improved the reputation of a market once regarded as something of a wild west. Interest rates have risen again recently, certainly, although property values have also increased in many parts of the UK.
Peter took his time. He spoke first with a broker and then with an independent adviser who was not connected to one particular lender. Both his children were included in the discussions. They raised difficult questions about fees, early repayment charges, inheritance and what might happen if he needed care.
In the end, he chose a lender offering voluntary repayments, no charge for small overpayments and firm no-negative-equity protection. Let’s be honest: nobody really does that every day. Most people accept whatever their bank proposes and hope it works out. Peter’s patient, determined approach is precisely what reduced the risk of his decision.
Practical steps if you are quietly asking, “Could I do that too?”
If Peter could give only one piece of advice, it would be to get completely clear about what you really want your home to do for you - not what you believe you “should” want. Do you want to remain there at all costs? Help your children buy a home? Pay for care at home? Travel? The answers will shape every later decision.
Then arrange a proper valuation rather than relying on an online estimate. The genuine equity in your property is the starting point. After that, speak to an adviser who must also consider alternatives, including downsizing, using savings, letting a room, or local authority adaptation grants.
Equity release should come at the end of a process, not as the result of a glossy advert. Peter agreed only after he realised downsizing would take him too far from his friends and GP, while renting out a room would leave him feeling like a lodger in his own house.
There are several familiar mistakes when people consider this subject. Some release the largest possible amount “just in case”, then allow interest to compound for years on money they never needed. Others proceed without speaking to family, only to encounter tension when their children discover the inheritance will be lower than expected.
Others refuse even to examine the figures because of a vague fear that “the bank will take the house”, despite modern plans not operating in that way. On a more personal level, some older homeowners feel they would be “admitting defeat” by using their property’s value, as though surviving solely on a pension were a moral obligation.
That is understandable on a human level. In practical terms, though, it can result in cold winters, unsafe bathrooms, delayed medical equipment and a persistent background anxiety about money. On a quiet evening, that concern can feel heavier than the walls around you.
Peter puts his choice simply:
“I realised I was sitting in a house that was worth a fortune on paper, while I was stressing over the price of a new boiler. That started to feel a bit silly. This place has looked after me all my life. Letting it pay something back isn’t betrayal. It’s balance.”
Peter found the following short mental checklist useful, and it may help anyone considering this path:
- What do I want my life to look like for the next 5–10 years?
- Have I explored downsizing, grants, or family support first?
- How much inheritance do my children realistically expect or need?
- Which equity release products offer flexible repayments and strong protections?
- How would I feel, honestly, seeing the final statement one day?
A change of perspective can alter the whole question. Rather than asking, “What will I lose?”, ask, “What will this allow me to live?” The answer will not always be “go for equity release”. It may be “stay as you are”, or “move somewhere smaller and pocket the difference”. The important thing is being willing to look.
What this 74-year-old’s decision reveals about ageing, money and home
Peter’s experience is not a fairy tale. It is the story of a man in his seventies who wanted warm showers, safer stairs and a kitchen where his grandchildren could bake biscuits without stumbling over broken tiles. Nothing more. Equity release did not turn him into a globe-trotting retiree; it made his home somewhere he could enjoy again, rather than simply tolerate.
Friends still ask whether he worries about leaving “less” behind. He says he is leaving something else: memories of a warm, welcoming home filled with Sunday roasts and laughter, rather than a chilly museum of unused wealth. As he watches the kettle boil on his new hob on a quiet afternoon, he feels unexpectedly lighter.
At a deeper level, his choice raises a wider question: what is the value of owning something valuable if it never provides meaningful support while you are alive? On a street where property prices have risen like ivy, several neighbours live as though they are short of money in homes worth hundreds of thousands of pounds. It is a distinctly British paradox.
We all recognise the moment when the supposedly “sensible” route may actually be taking years of comfort away from us. Not luxury, simply ease: a walk-in shower instead of a slippery bath, a warm sitting room instead of two jumpers and a blanket, or a kitchen where you can stand, cook and chat without worrying that the lights will fail.
For some people, equity release will never be the right answer, and that is entirely valid. For others, it may be the one option that makes a home a more supportive companion rather than merely a silent promise of future inheritance. Between those two positions are thousands of older Britons who have never truly been told that they have a choice.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Equity release as an option | Uses your home’s value to access cash without selling it or moving out | Provides a route to pay for renovations, care or greater comfort in later life |
| Modern protections | No-negative-equity guarantees, mandatory advice and flexible repayments on many plans | Reduces concerns about “losing the house” and gives more control |
| Family conversations | Including children early makes expectations about inheritance and priorities clearer | Can prevent tension and guilt while ensuring decisions reflect genuine needs |
FAQ:
- Is equity release safe in the UK now? Modern plans from lenders who follow Equity Release Council standards include legal safeguards such as a “no negative equity” guarantee and require independent advice. The key is to work with regulated advisers and compare several offers.
- Will I still own my home if I take equity release? With a lifetime mortgage, you remain the legal owner of your home. The lender has a charge over the property, similar to a traditional mortgage, which is repaid when you die or move into long-term care.
- Does equity release mean my children get nothing? Not necessarily. The final amount they inherit depends on how much you release, how long the plan runs, property price changes, and whether you make any repayments. Some people intentionally release only a portion to keep a clear inheritance buffer.
- Are there alternatives to equity release for funding renovations? Yes. Downsizing, local authority grants for adaptations, using savings, taking in a lodger, or family contributions can all be options. A good adviser should walk you through these before recommending equity release.
- Can I repay equity release early if my situation changes? Many plans allow voluntary repayments and partial early repayments, sometimes with limits per year. Full early repayment can trigger charges, so it’s crucial to read the terms and ask directly about exit fees before signing.
Comments
No comments yet. Be the first to comment!
Leave a Comment