
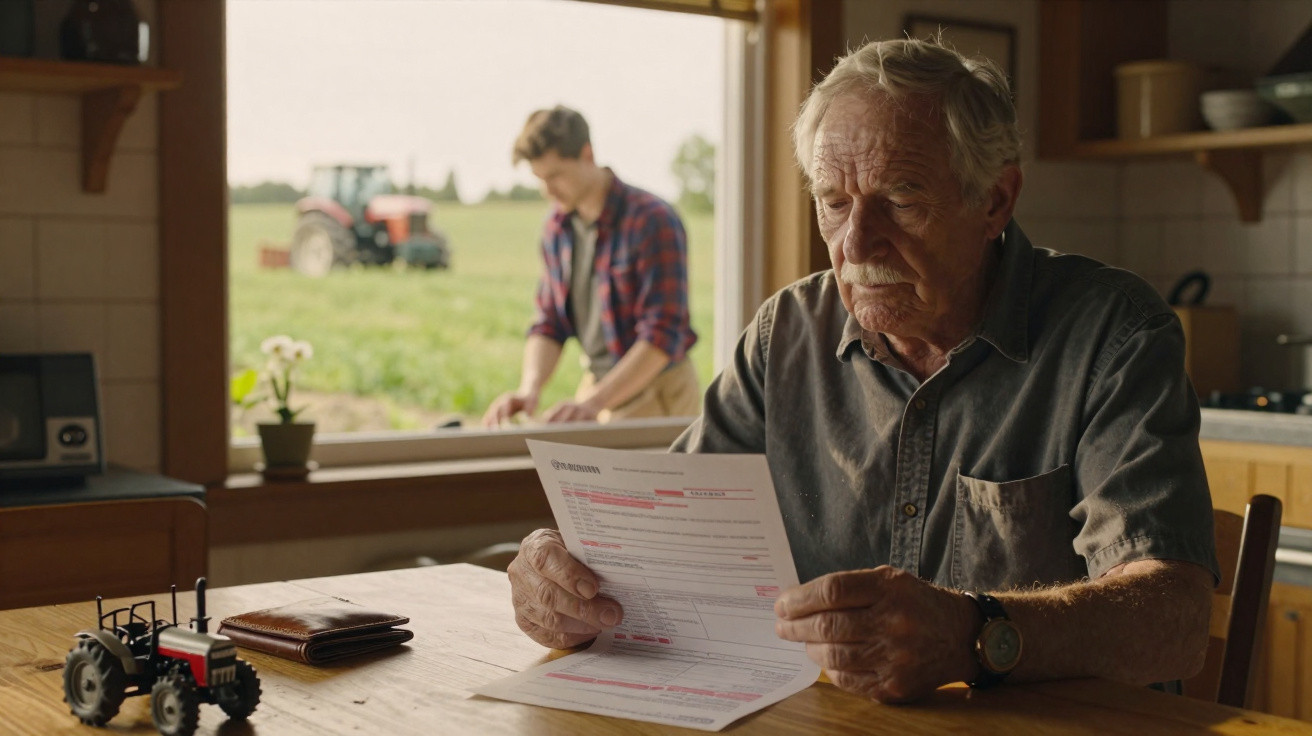
A retired landlord in a threadbare jumper sits on one side, gripping a brown tax letter until his knuckles whiten. Opposite him, a young farmer nervously flicks through his phone, attempting to understand the figures, regulations and penalties. It began as a straightforward act of solidarity: low-cost rent for a young man determined to keep the land productive. Now that act has brought a five-figure tax demand. Apart from the clock, the room is silent. An unspoken question lingers in the dusty late-afternoon light.
When generosity becomes a tax trap
On the surface, it is an almost heart-warming tale. A pensioner who has recently retired chooses not to take advantage of rising land prices. Instead, he lets his small farm to a young farmer at an affordable rate. There are no corporate tenants or speculative investors, only a handshake, a modest agreement and the reassurance of “doing the right thing”.
Then a letter arrives from HMRC. A handshake carries no weight with the figures.
Across the UK, Ireland and parts of Europe, tax systems tend to favour long-term lettings, substantial portfolios and properly documented arrangements. They are much less forgiving of partly informal agreements between neighbours who simply want to support one another. In this case, the pensioner learns that the reduced rent may be treated as a “benefit” provided to the young farmer. What appears morally admirable can, under tax rules, resemble undeclared income or a transfer priced below its true value.
The situation becomes harsh once an accountant puts it into financial terms. Forgoing a few hundred euros in rent each month can lead to a major tax adjustment, interest on late payments and perhaps a penalty. The pensioner’s carefully planned retirement budget is thrown into disarray. The authorities will never meet the young farmer who cleaned the sheds at 5am or delivered potatoes at Christmas. They will see only screen-based figures and a rule that has not been met. The same question returns: was this solidarity, or was it simply foolishness in a world governed by spreadsheets?
How a good deed becomes a fiscal nightmare
The plan itself was uncomplicated. The landlord, living on a modest pension, did not want the land to stand unused. He had farmed it himself in the past. He remembered being young, determined and short of money. He therefore offered the holding at a rent well below the market rate: enough to cover council tax, minor maintenance and provide a little spending money, but not enough to count as an “investment”.
His purpose was personal rather than financial: to give somebody a start in farming.
The young farmer seized the opportunity. Reduced rent allowed him to purchase a small tractor rather than spend all his money on rent. He renovated an old barn, experimented with regenerative methods and shared proud photographs from lambing season. Villagers spoke of “new energy” on the farm. One summer evening, the two watched the sun set across fields they could once again picture remaining productive in 20 years’ time. Neither mentioned capital gains, inheritance thresholds or agricultural relief.
Then tax law collided with real life. Since the rent was substantially lower than local market value, the tax authorities questioned whether the agreement was genuinely commercial. That distinction matters. Where an arrangement is not judged commercial, landlords can lose important reliefs. Inheritance tax may suddenly become a concern. Some expenses may no longer be deductible. If the pensioner also gave away equipment or wrote off rent arrears, those “gifts” could activate gift tax rules or affect future allowances. One generous gesture can create a legal labyrinth.
There is a further complication. In an effort to keep matters easy, the pair may have avoided formal valuations, full lease agreements or professional guidance. The tax office does not reward informality. Where figures do not align clearly with market evidence, the responsibility to prove the case quietly shifts back to the taxpayer. The pensioner, who believed he was sidestepping bureaucracy by relying on trust, discovers that the system is built for people who document generosity as though it were a commercial transaction. It is a harsh lesson delivered in the form of an official letter.
Protecting your generosity without losing it
Solidarity and tax compliance can sit together, even if they appear to be enemies. The first measure is rather unexciting: document everything from the outset. Use a proper farm tenancy agreement, set a credible rent and include a clause explaining any reduction and the method used to calculate it. A written valuation from a local letting agent or surveyor can feel excessive when the intention is simply to “help a lad get started”, yet it may later prove that the rent was not chosen at random. It was a conscious and considered decision.
Another modest but effective approach is to separate the support. Rather than cutting the rent sharply, keep the documented rent nearer to market value and provide help in other ways. Lend machinery from time to time. Give mentoring. Permit delayed payments under a written timetable instead of informally overlooking several months’ rent. More of the arrangement will then retain a commercial appearance for the tax authorities, while the personal support is delivered through distinct, ring-fenced actions that can be more easily explained if questions arise.
Many older landlords and farmers dislike the thought of speaking to an accountant before helping someone. To them, it can make an ethical choice feel like an exercise in spreadsheets. However, a single consultation may preserve the purpose of the gesture. A specialist can identify relevant thresholds, recommend suitable contract structures and explain what to avoid. Some may even state the uncomfortable truth: “If you do it that way, you could blow your retirement.” A blunt warning in a warm office is preferable to an unexpected tax demand at the age of 78, when energy is limited.
There is also an emotional dimension. Helping a young farmer means offering more than land: you are entrusting your name, your reputation and your history. That is why mistakes can feel so painful.
On a freezing January morning, when faced with a five-figure tax bill, it does not merely seem as though you made an error. It feels as if the system has penalised you for caring.
“I wasn’t trying to dodge anything,” one retired landlord in Devon told me. “I just didn’t want the place turned into holiday lets. I thought I was doing my bit. Then the letter came and I felt like an idiot. Solidarity? They treat it like I cooked the books.”
It is difficult not to absorb that shock. Shame starts to take hold. Relatives quietly suggest that you were naïve. You begin to ask yourself whether you should have sold to the highest bidder and booked that cruise. Yet the original impulse can still feel right somewhere inside.
Everyone recognises the point at which paperwork overwhelms something human, leaving you to decide whether you were kind - or merely foolish.
- Before accepting a reduced rent, obtain at least one written estimate of the market rent.
- Use a simple but formal tenancy agreement, even when dealing with friends or neighbours.
- Speak once to a tax adviser who understands rural property or small farms.
- Reassess the arrangement every few years as legislation and property values change.
- Keep brief records explaining how and why you set the rent. Your future self will be grateful.
Is solidarity still worth the risk?
The underlying issue in this story goes beyond tax. It concerns the sort of countryside and economy in which we want to live. If every act of generosity is penalised, people withdraw. They sell to large operators, demand the highest rent the market can support and stop opening the door to an anxious 27-year-old with calloused hands and no security. That loss may not appear in budget documents, but it is real.
Equally, acting as though tax rules do not exist is not solidarity. It is self-sabotage in slow motion. A retired landlord financially devastated by an unforeseen bill is not a local hero. He becomes another warning repeated at the pub: “Helped a young farmer, lost his pension.” That message spreads more quickly than any official guide about “supporting new entrants into agriculture”. Let us be honest: nobody really reads tax guides every week.
Perhaps the answer is to stop treating the heart and the head as opposites. There is nothing uncaring about a carefully drafted lease that safeguards both parties. There is nothing cynical about checking what reliefs apply to long-term farm lettings, or whether your country recognises “agricultural value” for inheritance purposes. A system that genuinely wanted more young farmers would make this route clearer, less punitive and easier to follow without a law degree.
Until then, the decision remains with each of us, at a kitchen table with a pen and a stack of envelopes.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Tax treatment of “solidarity” rents | Rent set far below market value may be reclassified and can result in the loss of certain tax reliefs. | Understand why a generous act may lead to a substantial tax charge. |
| Formalising the relationship | A written lease, market valuation and specialist advice greatly reduce the risks. | Learn how to protect both the retired landlord and the young farmer. |
| Alternatives to reducing rent | Support can be provided through equipment, mentoring or staged payments rather than a major rent reduction. | Find ways to show solidarity without putting your own retirement at risk. |
FAQ:
- Can a landlord legally charge below-market rent to a young farmer? Yes, but the arrangement should be recorded and supported by a market valuation, because very large reductions can affect how tax authorities assess it.
- Why would a discounted farm rent trigger a large tax bill? Tax rules often make reliefs and allowances conditional on “commercial” arrangements; if the rent is judged non-commercial, the landlord could lose key reliefs and face back taxes.
- What’s the safest way to help a young farmer financially? Keep the stated rent reasonably close to market levels, then offer additional support through clear, separate agreements, such as equipment sharing or time-limited rebates.
- Does this problem only affect big landowners? No. Small retired landlords can be affected most severely, as one tax adjustment may wipe out years of modest savings or pension planning.
- Is it still worth acting in solidarity despite the tax risks? Yes, provided generosity is combined with basic legal and tax planning; this protects both the spirit of solidarity and the donor’s own future.
Comments
No comments yet. Be the first to comment!
Leave a Comment