
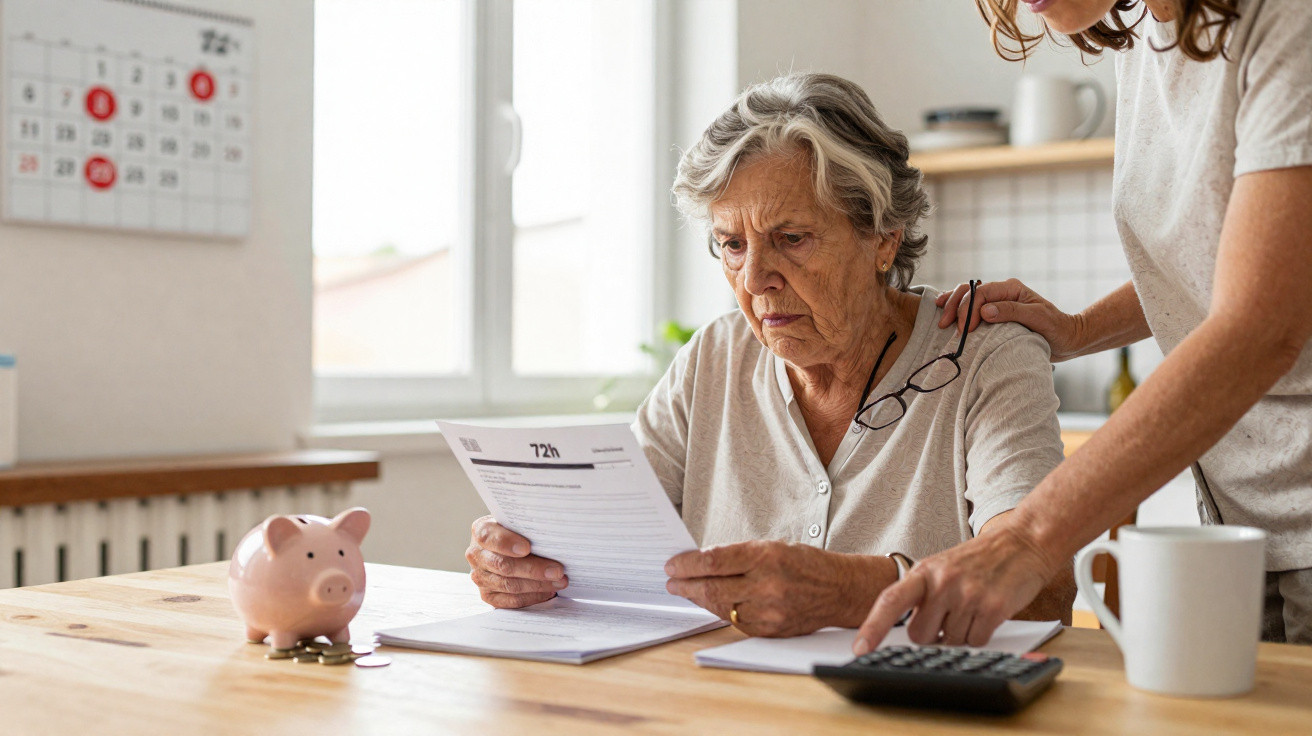
Thick paper, a tidy logo and lifeless wording. “Adjustment to your guaranteed minimum pension.” Margaret, 74, read the sentence twice at her kitchen table while the kettle whined behind her. Adjustment sounded orderly. Her finances were anything but. The amount was lower than it had been the previous year. Her hands did not tremble; instead, they moved more slowly, as though she were walking onto ice. Rent was due in nine days. She had already cut back her shopping list. Car tax was coming up next month. Almost amused, she murmured, “Guaranteed?” before folding the letter into a square that refused to stay folded. The hallway clock ticked with the certainty of something that would be paid on time. Her safety net felt like a thread pinched between two fingers. She made a cup of tea and left it to go cold. The room no longer felt quite the same.
When the floor vanished beneath you
A cut to a guaranteed minimum pension may sound like an administrative detail until it takes money out of an ordinary Tuesday. For many pensioners, that floor was not an extra comfort; it marked the difference between managing and falling behind. Remove it, and worry comes into the home like a draught slipping under the door. On paper, the figures may seem modest-twenty pounds here, forty there-but everyday life is funded in small amounts. A bus pass, a fridge making an alarming hum, another prescription collected later than planned. A “guarantee” is a promise clothed in policy. When it is reduced, dignity is diminished alongside it. Stress takes up residence too.
Consider Iris, 73, from Leeds, who planned her winter spending around an amount she believed she could rely on. Her “minimum” dropped by £36 a month following changes to indexation and a scheme correction for which she was not responsible. That could mean two weeks of heating set very low. Or giving up the gardener, because the weeds can wait. She said she would leave just one light on after 6 p.m. and batch-cook meals to reduce oven use. It felt like the ground moved under her feet. A widower of 77 discovered that a recalculation of his GMP meant the premium for his funeral plan was now squeezing his food budget. These are numbers with sharp edges, cutting wherever they fall.
The explanation lies within the pension system’s hidden pipework. The guaranteed minimum pension, created to reflect a state commitment and contracted-out rights, depends on indexation rules, reconciliation exercises and scheme records that may have sat in filing cabinets for years. Inflation has been high. Some schemes limit increases. Some assume the state will meet the increase, while others do not. Where reconciliation uncovers inconsistencies, pension reductions can follow, even for people late in retirement. What looks like a neat accounting entry to an accountant can feel like a missed meal to the person receiving it. Timing matters as well: reductions seldom arrive when savings are healthy. Retirement cash reserves are often depleted most quickly. For that reason, a reduced “guarantee” means more than lower income. It creates immediate risk.
What to do now if your guaranteed minimum pension is reduced
Make three calls within 72 hours. First, contact your scheme administrator and request a written explanation of the change, the indexation basis and any deadline for an appeal. Second, speak to your local advice service or a pensions helpline and arrange a benefits check for support you may now be entitled to claim. Third, call your utility provider to ask for a vulnerable-customer marker and a payment arrangement adjusted to reflect your revised income. Put together a 90-day plan on paper rather than trying to hold it in your head. Write down fixed costs first, followed by those you can change. If possible, pause one discretionary payment for a single billing cycle while you collect the facts. A temporary pause creates breathing space.
The common mistakes are understandably human. Leaving the letter unopened. Hoping “next month” will somehow look better. Cancelling insurance that remains essential. Paying too much towards debt before checking whether hardship support is available. Allow yourself to be shaken, then take small and practical actions. Most of us have had a moment when the calculator app seems to be passing judgement. Take a breath, then bring the figures into the light. If you were contracted out, ask in writing who is responsible for indexation on your GMP segments and whether any arrears or alignment payment is owed. Let’s be honest: nobody really does that every day. Do it this week. A single telephone call can turn a “no” into a “maybe.”
This is a sentence I repeatedly hear from caseworkers:
“People think a reduction is final. It often isn’t. There’s a process, and the process has doors.”
Keep those doors in sight. Use this short checklist to stabilise things for the next quarter:
- Write to the scheme asking for a “statement of entitlement with indexation detail.” Save a PDF.
- Ask the state pension service about GMP indexation and any review of underpayments.
- Arrange a benefits check covering pension credit, council tax support and winter assistance.
- Change to monthly utility billing and submit an accurate meter reading. Accuracy can save pounds.
- Set a modest emergency-fund goal: enough for one bill, held in a separate pot.
What a reduced GMP means for everyone
When a guaranteed minimum is cut, it reveals a broader story about trust. The social contract becomes thinner first at its edges, where people’s lives are already precarious. A promise made decades ago now encounters prices at today’s till, and the difference is a bruise that cannot be photographed. Some people will cover it through part-time employment or help from family. Others will not have either option. Policy may catch up-or may not-at a pace people cannot afford to live by. Communities can help narrow the gap: neighbours checking on one another, councils providing warm spaces and charities fighting quiet battles. The question hanging over every kettle is straightforward: what should we call a guarantee when it can be withdrawn?
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| - | GMP reductions arise from indexation caps, reconciliation and inflation shocks | Understand the source of the reduction, rather than only the amount |
| - | Immediate action: request a breakdown, check benefits and revise bills | Turn the initial shock into a short plan within 72 hours |
| - | Appeal deadlines and hardship policies exist, often quietly | Regain lost ground or limit the harm through the available process |
FAQ:
What exactly is a guaranteed minimum pension? The guaranteed minimum pension is a minimum level set within certain workplace pension schemes to reflect a state promise arising from years of contracted-out service. It is intended as a baseline to prevent people dropping below a minimum amount, with rules governing annual increases.
Why would my “guarantee” go down? Typical causes include limits on indexation, data reconciliation between scheme and state records, and corrections where earlier assumptions do not match the law. Your letter should state the reason and explain how the figure was calculated.
Can I challenge a reduction? Yes. Request the full calculation, the legal grounds and details of the internal dispute-resolution procedure. Many schemes provide a formal two-stage complaints route, and certain cases may be referred to an ombudsman.
What help can soften the shortfall right now? Check pension credit, council tax support, disability premiums, warm home discounts and social tariffs for broadband or energy. Utility companies can also review payments for vulnerable customers.
How do I protect my budget if this happens again? Build a small reserve pot, move to monthly billing with accurate readings, prepare a straightforward spending sheet and schedule an annual review of your pension statement. It may not be glamorous, but it can stop the floor cracking twice.
Comments
No comments yet. Be the first to comment!
Leave a Comment