
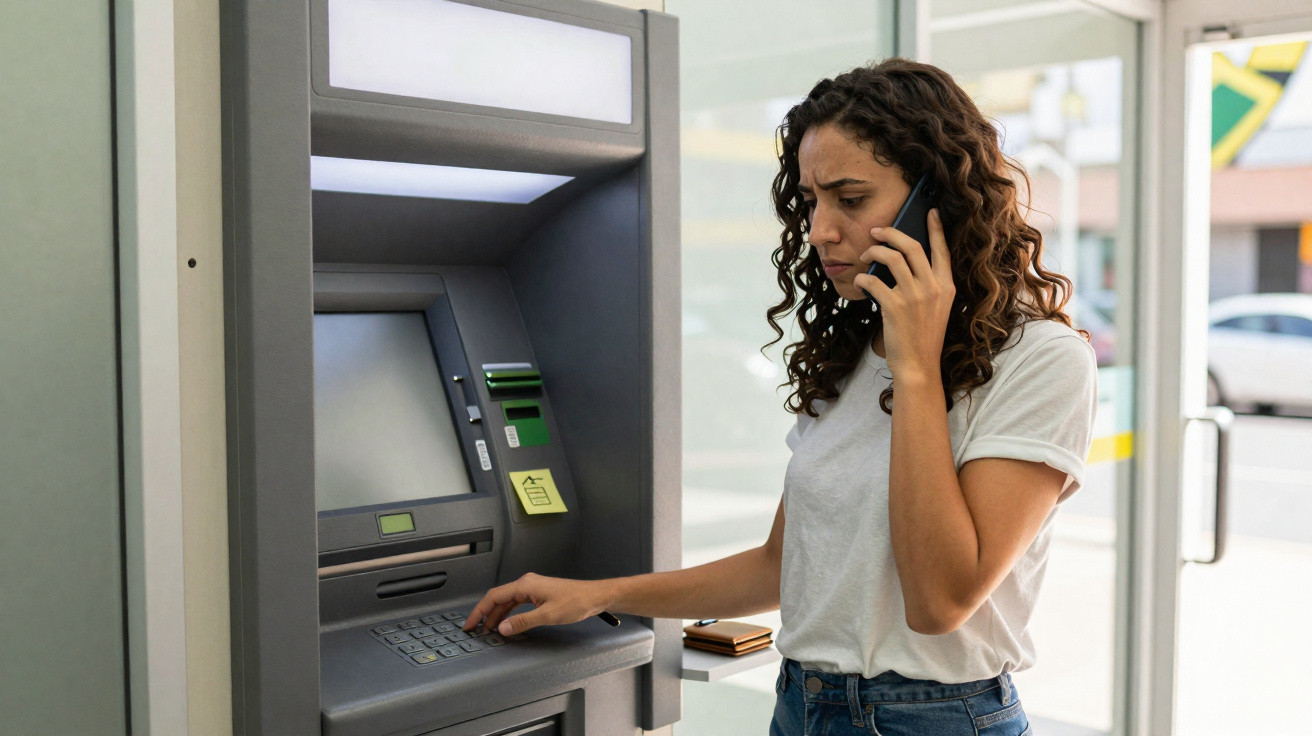
It can happen in crowded city centres, at motorway service stations, in airports or on a quiet Sunday evening when bank branches are closed. When an ATM retains your card, panic can set in immediately, but many people do not know which button to use, who to contact or how to prevent criminals exploiting the situation. This is a clear, practical guide to follow as it happens.
When an ATM retains your card
Modern cash machines have safeguards designed for this exact problem. They account for user mistakes, power interruptions and blocked card slots. Often, pressing the correct button can end the session safely and return the card without involving an engineer.
Head straight for the red “Cancel” or red X button, then keep it pressed for three to five seconds to force the ATM to close your session and eject your card.
On touchscreen ATMs, options commonly include “Cancel”, “End” and “Finish”. Select these in turn and confirm the choice to send the same instruction: end the transaction and attempt to release the card. Some more recent machines also have a specific “Return card” option, occasionally represented by a card symbol with an outward-pointing arrow.
Immediate ATM checklist
- Hold down the red X or “Cancel” button for several seconds.
- On a touchscreen, select “Cancel”, followed by “End” or “Finish”, and then “Confirm”.
- Check for a “Return card” option, press it once and wait for at least 10–20 seconds.
- Remain directly in front of the ATM, with your hand close to the slot but not obstructing it.
- Do not accept assistance from strangers, however well-informed they appear.
- If your card is returned, remove it at once before reading any notification or collecting a receipt.
Do not walk away until the machine clearly ends the session and your card is safely in your hand.
These functions are provided because ATMs regularly encounter problems: customers may leave cards behind during hurried withdrawals, damp or damaged cards can stick in the reader, and power can flicker during a transaction. Issuing a definite instruction to end the session tells the ATM to complete its safety process, which will usually involve returning the card.
If the card still will not come out
If the reset options do not work, act quickly. An ATM may retain a card because of a legitimate fault or because criminals have interfered with it. Either way, take the same action: secure the card digitally before somebody else can use it.
Call your bank before leaving
Use the emergency telephone number on the back of the card, or a 24/7 number displayed on the front of the ATM. If you cannot provide the card number, your bank can normally locate the account using your personal information.
Ask the bank to block the card immediately, stating that it has been “retained by an ATM”. Do this before discussing anything else.
After the card has been blocked, cash withdrawals, chip-and-PIN payments and contactless transactions should be stopped within minutes. While you are still beside the machine, note the precise time and location, such as the branch name, street, supermarket entrance or petrol station.
Information to record immediately
- The ATM identification number or any code label positioned near the display.
- The time and the action you were trying to complete, whether a withdrawal, balance enquiry or PIN change.
- Any error message shown, even if it appeared only briefly.
- Evidence of tampering, including a loose card slot, unusual plastic covers, tape or large added components.
When the ATM is in a staffed bank branch during opening hours, go directly to the counter. Staff can record the issue, establish whether the machine has retained the card and may sometimes arrange for it to be recovered later when you show identification. The process is different for independent cash machines in shops or pubs: rather than return the card, your bank will normally cancel it and issue a replacement.
What may have happened inside the ATM
| Likely scenario | What it means | Best response |
|---|---|---|
| Timeout after cash was paid | The ATM gave you time to remove your card, then drew it back in as a security measure. | Contact your bank, request a block and ask whether the branch can return the card on presentation of ID. |
| Software or power freeze | The machine’s internal system failed and the card mechanism locked. | Press and hold Cancel. If that does not work, ask your bank to block the card and report the fault. |
| Card trap device (“Lebanese loop”) | A thin device has caught the card so criminals can retrieve it once you leave. | Remain there, call your bank and, if it is safe, notify staff or the police. Do not leave the area. |
| Skimming with PIN capture | A false reader and concealed camera have copied your details and observed your PIN. | Block the card straight away, ask for a new card and PIN, and closely monitor your account. |
After calling: monitoring and disputes
After reporting the problem, open your mobile banking app. If they are not already active, enable immediate alerts for every cash withdrawal and shop payment. These provide a live warning if anyone tries to use the card details before the block has fully taken effect.
Report any unrecognised transaction straight away through the fraud helpline or secure messaging service. In the UK, US and much of Europe, banks generally apply a “zero liability” or limited-liability policy to unauthorised card spending, provided you report it promptly and have not disclosed your PIN.
Why contactless and cardless cash lower the risk
One gradual change in banking is reducing the need to insert a plastic card into a slot at all. Many ATMs now allow contactless withdrawals with a physical card, a phone wallet or QR codes created through your banking app.
For contactless cash, tap your card or phone on the reader, choose the amount and enter your PIN. Because the card never enters the ATM, it cannot be caught by a jammed mechanism or trap device.
By using tap‑and‑go or app‑based withdrawals where available, you largely remove the classic “swallowed card” scenario.
Where card-free options are most common
- Busy bank branches in city centres and transport hubs.
- ATMs operated directly by major banks rather than independent providers.
- Newer machines showing the contactless symbol near the keypad.
Your mobile banking app will often have an ATM locator showing which cash machines offer contactless or “cardless cash”. Travellers should be aware that certain overseas cards or e-wallets may still not work with older software, even where the logo is displayed on the machine.
Limits and issues to remember
- Daily cash limits can be lower for contactless and app-based withdrawals.
- Certain ATMs accept phone wallets but not contactless cards, while others do the reverse.
- QR withdrawals prepared in advance generally expire after a short security window.
How to identify a risky ATM before inserting your card
A 10-second inspection can prevent most retained-card problems. Fraud teams say that criminals frequently depend on people being hurried and failing to check the machine properly.
- Lightly move the card slot; it should be solid rather than loose or rattling.
- Inspect the keypad for additional layers or buttons that do not line up correctly.
- Watch for mismatched colours, adhesive residue, tape or bulky attachments around the screen.
- Shield the keypad with your hand when entering your PIN, including at indoor ATMs.
- Choose cash machines inside bank branches or brightly lit shops covered by CCTV where possible.
- Decline help from strangers, particularly if they tell you to press certain buttons or enter your PIN again.
If someone phones you while you’re at an ATM claiming to be from the bank and asking for your PIN, hang up immediately. Banks do not do this.
Extra tools that genuinely reduce your risk
Using app controls, locks and limits
Many banks now include card-management controls in their apps. You may be able to lock the card temporarily between journeys, disable cash withdrawals entirely or set a very low daily limit. Instant notifications for every transaction offer another effective safeguard, acting as a digital alarm if something unexpected occurs.
For regular travellers, particularly those passing through busy airports or nightlife areas, setting strict limits in advance and making tap-based withdrawals can substantially reduce losses if a card is trapped, misplaced or cloned.
What happens behind the scenes to a retained card
When an ATM draws in and retains a card, it will usually place it in a secure container within the safe. At some bank-operated machines, staff later collect these cards, compare them with transaction records and return them to customers who present official identification. In many other situations, especially with third-party ATM operators, retained cards are destroyed routinely for security.
Do not assume you will receive the same card again. Treat it as lost, ask your bank to cancel it and request a replacement. You may also seek reimbursement for charges linked to a failed transaction, including a foreign-use fee or a balance enquiry charge that was not completed correctly.
A short script to remember
- Card retained? Hold the red X or Cancel button for three to five seconds.
- Select the on-screen “End” or “Return card” options and wait the full 20 seconds.
- Still no card? Stay beside the ATM, call your bank’s emergency line and request an immediate block.
- Record the time, ATM location and any error codes; if safe, photograph the screen.
- Enable account alerts and check for unfamiliar withdrawals or purchases.
- Dispute anything suspicious immediately, and request a new card and PIN.
Repeating that script in your mind once or twice before your next cash withdrawal could be the difference between a stressful five-minute wait and a costly fraud dispute lasting several days.
Comments
No comments yet. Be the first to comment!
Leave a Comment