
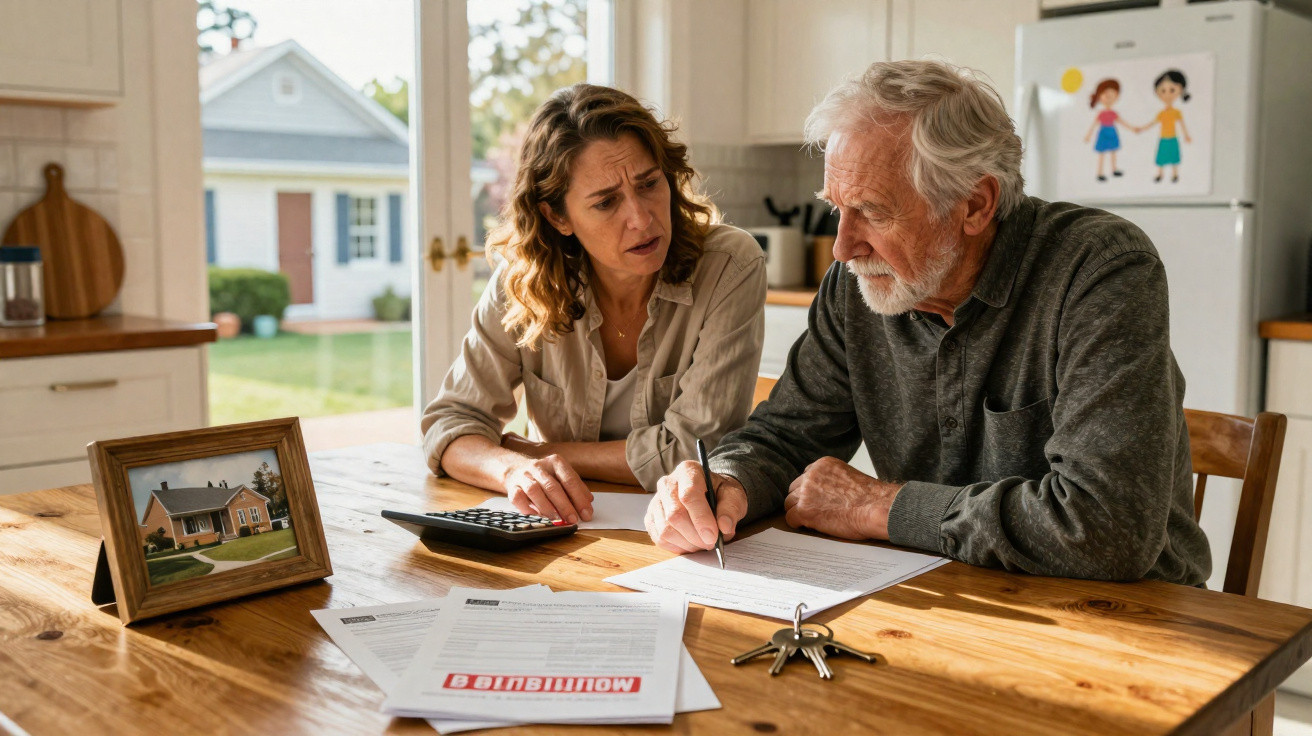
The daughter was still holding the keys when the letter dropped through the door.
The house her father had spent 30 years paying off was finally hers. There was no landlord and no rent to worry about-only the stairs that had always creaked and the garden he had cut back every Sunday.
Then she opened the envelope.
It was an inheritance tax demand on a home that had already contributed to the public purse through property taxes, capital gains tax, renovation permissions, stamp duty and more.
The sum exceeded her yearly salary. She could hold on to the house, or she could keep her savings.
That evening, she posted a single sentence on social media that quickly went viral: “How many times can one home be taxed before it stops being ours?”
The replies poured in.
Clearly, something had broken.
The shock of “being taxed twice” on the same home
For many households, a home is more than bricks and mortar: it is a physical record of a family’s life.
Every mortgage instalment, every weekend spent decorating and every roof leak repaired at 2 a.m. felt like a contribution towards the children’s future.
When the state arrives at the end of that process with an inheritance tax bill, many people feel let down.
One reaction appears again and again, stripped of any nuance: “We already paid.”
They remember the years of property tax, along with the income tax already deducted before each monthly mortgage payment left their bank account.
The thought that death can trigger another tax charge on the same property can feel like a blow to the stomach.
Read through any news discussion on the subject and the same outrage emerges.
In one widely circulated account, a retired couple had devoted decades to paying off a modest three-bedroom house in a suburb that unexpectedly became “prime.”
Its paper value had risen into seven figures.
Yet their daughter was a teacher who was only just managing her day-to-day living costs.
When both parents died within two years of each other, the valuation took her beyond the relevant threshold for an inheritance tax bill.
She had to sell the home to meet the charge, relocate an hour away from her workplace and watch strangers repaint the living room where she had grown up.
The property had climbed the wealth ladder.
She had not.
Governments maintain that inheritance tax is a matter of fairness.
They argue that it limits the formation of dynasties, pays for public services and prevents the very richest families from preserving power across generations.
Opponents respond that middle-class households with unremarkable homes in overheated property markets are being handled as though they were ultra-wealthy.
House-price growth increases wealth on paper, even when the money in the bank remains limited.
So a tax intended for millionaires can unexpectedly affect nurses, shopkeepers and office workers, simply because their parents purchased a house on the “right” street in 1987.
That is where the resentment lies: in the gap between the value the state sees on paper and the cash families genuinely have available.
How families are trying to protect homes before it is too late
Away from the political arguments, a quieter process is unfolding in kitchens and living rooms.
Parents are asking their children to sit down, bringing out long-forgotten files and raising direct questions they once avoided.
Some give away a share of the house during their lifetime.
Others place ownership in family trusts or make their children co-owners so that the transfer takes place over time.
A small number choose to downsize sooner, exchanging the large family property for somewhere smaller and sharing the difference while they can still see their children’s reactions.
There is nothing romantic about it.
It is planning for survival.
Certain errors occur time after time.
Some homeowners leave matters too late, believing the rules will stay as they are or assuming their modest house could never appear on the tax authorities’ radar.
Then a new underground line opens, a technology hub arrives nearby, and their previously ordinary street quietly becomes a goldmine in official valuations.
Their children may then receive condolences and a tax assessment in the very same month.
Others depend solely on family assurances or handwritten notes.
The law seldom gives those much weight.
Documents, valuations and dates are considerably more important than memories.
We have all experienced that moment of deciding to deal with the paperwork “next year”, only for life to continue getting in the way.
Eventually, the debate ceases to be theoretical and reaches your own dining table.
One financial planner told me that he now spends a third of his working time simply explaining taxes connected with death to shocked families.
“People come in thinking this is a problem for billionaires,” he said.
“Then they realize that after 20 years of price growth, their parents’ tiny house puts them straight into the inheritance tax conversation.”
To find their way through this situation, families are increasingly seeking very practical help:
- Straightforward explanations of what local inheritance tax rules actually mean, rather than legal jargon.
- Realistic property valuations completed early, instead of when emotions are at their most intense.
- “What happens if…” projections, so that nobody has to estimate a future tax bill blindly.
- Legal ways to gift or share portions of the home gradually.
- Clear records stored in one place, so relatives are not searching through boxes after a funeral.
In truth, nobody manages this every day.
But families who begin earlier often avoid the most severe surprises.
What the inheritance tax “double tax” dispute reveals about ownership of the future
Once the technical language is removed, this is a straightforward but deeply emotional question.
Is the family home a private legacy, or is it a portion of wealth that should return to the state’s circulation with every generation?
Rules vary greatly between countries and can even differ from one year to the next.
Exemptions can increase or decrease.
Thresholds may rise with inflation, or fail to keep pace with it.
In the middle are families attempting to mourn, arrange a funeral, clear a bedroom full of childhood drawings and respond to a tax letter at the same time.
No spreadsheet can properly measure that burden.
The argument over inheritance tax on homes that have already been taxed is unlikely to disappear.
As property values rise and generations clash over who received which opportunities, the pressure is set only to intensify.
Some people will support higher thresholds, some will call for the tax to be abolished and others will favour applying it only to very large estates.
What remains with many families is a basic fear: that a home they believed belonged to them can be lost because of a bill they never anticipated.
It is the sort of question that remains after the headlines have faded, and one that many people quietly consider at night:
If the house has paid its dues for decades, how much of it really belongs to the family-and how much always belonged to the state?
| Key point | Detail | Value for the reader |
|---|---|---|
| Check local rules early | Inheritance tax thresholds and exemptions differ significantly between areas and can change over time. | Helps you identify whether your family home might create a tax liability, even if your income seems “ordinary”. |
| Plan the transfer during life | Gifting shares, using allowances or introducing gradual co-ownership can reduce or prevent a sudden tax charge. | Lowers the chance that heirs will have to sell the home simply to pay the bill. |
| Keep clear documentation | Written records, valuations and up-to-date wills carry more weight than verbal agreements within a family. | Protects family relationships and reduces pressure during an already distressing time. |
FAQ:
Question 1: Is this really “double taxation” if the house was already taxed for years?
From an emotional perspective, many people believe it is, because one asset can face several different taxes during its lifetime. In legal terms, governments say that each charge applies to a separate event: owning the home, selling it and passing it on after death.Question 2: Does every inherited home get hit by inheritance tax?
No. Most systems provide a tax-free threshold or exemptions for close relatives, and many modest properties remain below that limit. Difficulties arise where house prices increase more rapidly than the limits are updated.Question 3: Can planning really change the size of the tax bill?
Often, yes, provided arrangements stay within the law. Giving gifts across several years, sharing ownership earlier or relying on particular exemptions can substantially reduce what becomes due later.Question 4: What if heirs cannot afford the tax but do not want to sell the house?
Some governments permit payment by instalments or offer special arrangements, while some banks provide loans secured against the property. Every option carries risks, which is why early discussions and advice are important.Question 5: Is the debate only about wealthy families and luxury homes?
No. Rising prices mean entirely ordinary properties bought decades ago can bring middle-income heirs within the inheritance tax net. This conflict between paper wealth and available cash is precisely what is driving today’s backlash.
Comments
No comments yet. Be the first to comment!
Leave a Comment