
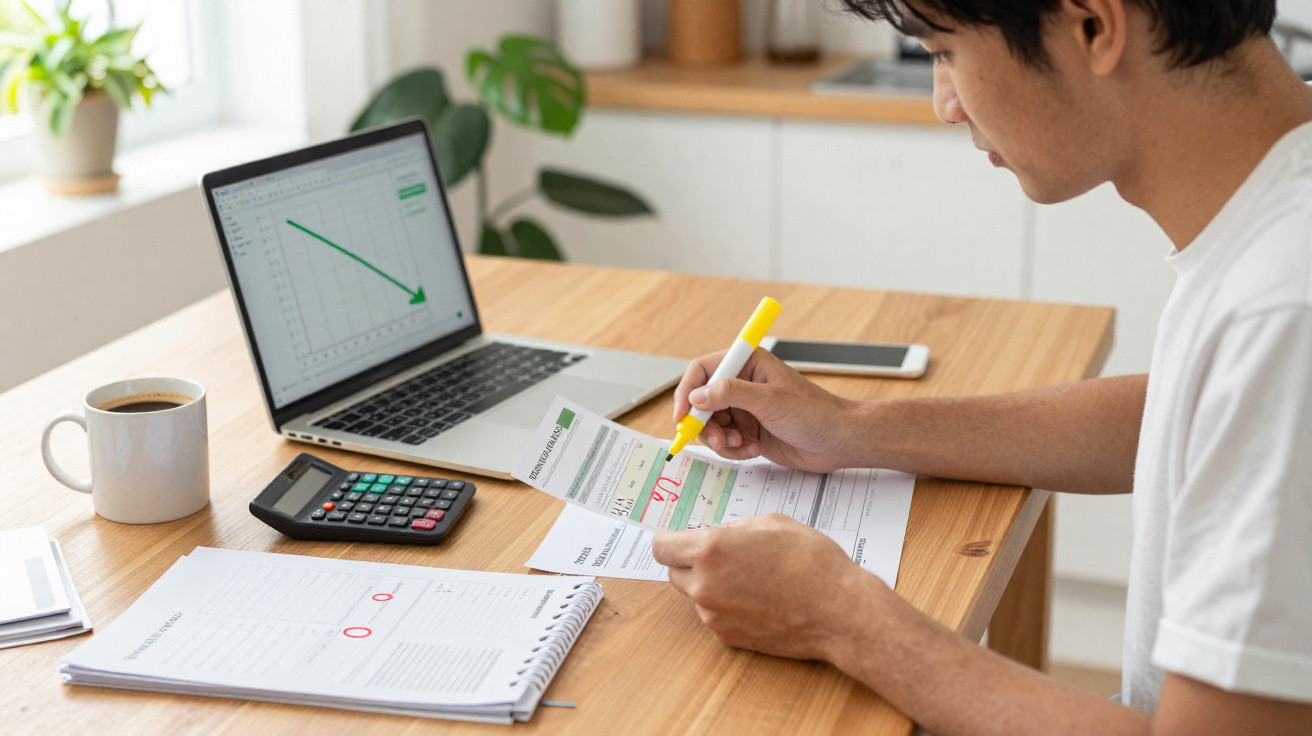
The kettle switches itself off, the laptop display lights up, and Sam at last opens the banking app he has put off checking all month.
Before his tea can cool, the figure lands: a smaller balance, larger direct debits, and the nagging feeling that his money is leaving without his say-so.
He flicks through “£7.99 / £12.49 / £3.50” as though they were meaningless raffle numbers. There is a streaming platform he hardly uses, an insurance extra he cannot recall accepting, and a utility-bill “service charge” that appears to edge up every season.
This is usually how it unfolds on an ordinary Tuesday evening. It is not a major emergency, but a gradual awareness that the small print is steadily coming out on top. In those rows of digital text, something does not seem quite right.
Why your monthly bills rise without you noticing
Hardly anyone gets up intending to throw money away. Instead, it seeps out month after month through bill entries phrased in a way that seems intended to make your eyes glaze over. Bills fade into the background like the fridge’s constant hum: ever-present but seldom challenged.
An extra pound here, a “reviewed tariff” there, or a free trial that became a paid subscription. Individually, none feels dramatic. Together, though, the total quietly rises while any pay increase never seems to improve day-to-day life. That is not simply misfortune; it is how the system is structured.
One UK survey found that the typical household pays for at least four subscriptions it does not actively use. On an average day, this may seem harmless: a fitness app left uncancelled, a magazine rarely opened, or a “pro” version of a tool used only twice a year. Across a year, however, hundreds of pounds can leave your account with almost polite ease.
Picture a Manchester family paying for broadband, mobiles, streaming, a couple of cloud-storage services, breakdown cover, pet insurance and a gym. Each cost is “only” £5–£30. Add a handful of loyalty-scheme fees and utility “administration charges”, and fixed monthly spending may rise by £80 in under two years, despite no significant lifestyle change. It is simply the result of small agreements they scarcely remember making.
The psychology is straightforward. Recurring bills are dull, so most people only skim them, if they read them at all. Dense jargon often encourages you to stop trying to understand them. Automatic payments make collecting money easy for businesses and make it easier for you not to think about it. Price increases arrive in lengthy emails that you are too exhausted to read after work. The system therefore depends on your tiredness and trust, precisely the combination in which hidden fees thrive.
How to review your monthly bills and find hidden costs
Begin with one uninterrupted hour. Rather than vaguely promising yourself that you will “sort out finances one day”, choose a calm evening, make a drink, open online banking and record every monthly payment on a blank sheet or spreadsheet. Give each payment its own line, including the name, amount, date, and whether it is a bill, subscription or debt repayment.
Next, sort them into three broad groups: essential, such as rent, energy and council tax; useful, such as your phone, broadband and perhaps one streaming service; and optional, which covers everything else. Do not debate each expense with yourself yet. First, put your financial life plainly in front of you. That view alone can often be enough of a shock to alter your habits.
After mapping everything out, focus on one category: utilities, subscriptions or banking fees. For utilities, gather the latest three bills for gas, electricity, water and broadband. Check every line for costs other than energy or water, including “standing charge”, “service fee”, “paper billing”, “late payment recovery” and “admin charge”. Compare today’s unit rate with the rate shown on earlier bills. Even small increases count when they apply to every unit you consume.
For subscriptions, search your inbox for “trial” or “subscription started”. You may uncover digital ghosts from years ago. Cancel services that no longer suit your life today, rather than the hopeful version of yourself from three years earlier. For bank accounts, look for packaged-account fees, overdraft interest, “card protection”, “account maintenance”, or foreign transaction charges that appeared after a weekend away. Every item raises the same question: is it genuinely worth its monthly cost?
The next stage is slightly uncomfortable: phoning or messaging providers. Many people stop there because nobody truly enjoys spending 40 minutes on hold listening to tinny 80s cover versions. Nevertheless, this is commonly the point at which the largest savings emerge.
Prepare a script before you start. Write down your existing price, how long you have been with the provider, and a lower competing offer from another provider, found on comparison sites or competitors’ websites. Then call and say calmly: “I’m reviewing my monthly bills and this cost is too high for me. What can you do to reduce it today?” Remain on the call. In this situation, silence can work in your favour.
Some providers will reduce the price, remove a fee, or place you on a more suitable tariff. Others may simply refuse. If that happens, be prepared-and genuinely willing-to change provider. Loyalty rarely rewards you as well as courteous persistence. Let’s be honest: nobody really does this every day. Yet doing it once or twice a year is enough to prevent your costs from quietly rising by default.
“I saved £62 a month in one afternoon just by asking, ‘What is this fee for?’ and not accepting ‘it’s standard’ as an answer.”
There is a subtle sense of power when a customer-service adviser says, “Let me see what I can do,” and an unexplained charge suddenly vanishes. There is no need to argue; you only need to make clear that you are willing to leave if the figures no longer work for you.
- Mark every charge you do not completely understand before making contact.
- Save screenshots or take photographs of bills so that you can cite precise amounts.
- Request email confirmation whenever a fee is removed or a price is lowered.
- Put a reminder in your calendar to check that bill again in 6–12 months.
Most people were not taught how to negotiate with businesses. We learned instead to accept “terms and conditions” without protest. Changing that attitude does not mean becoming confrontational; it means viewing your monthly bills as an agreement between equals rather than a ruling imposed from above.
The long-term routine for lower spending without deprivation
After giving your bills a thorough clean-up, the aim is to avoid drifting immediately back into autopilot. A manageable routine is much more effective than one grand, heroic effort. Choose one day each month-perhaps the first Sunday-for a “money check-in”: 30 minutes with your phone and banking app ready.
Look through the previous month’s transactions and flag anything unfamiliar or anything that prompted a small feeling of “ugh” as it left your account. It could be a subscription you barely used or a bill that felt sharper than expected. This is not about feeling guilty; it is about remaining aware of where your money is actually going.
Every six months, go a little further. Reassess the big four: housing, utilities, communications, meaning phone and broadband, and subscriptions. Have the prices increased? Has a fixed deal expired, leaving you on a standard rate? Is a cheaper or better-suited option now available?
This pattern changes financial control from an annual panic into a lighter, recurring practice. Over time, it also reshapes your response to fresh offers. You begin to distinguish between something that offers genuine value and another £4.99 attempting to join the quiet crowd on your bank statement.
The emotional side matters too. On an exhausting Wednesday evening, turning down an appealing new subscription may feel like giving up a small pleasure. On a sunny Saturday morning, noticing an additional £80 in your account after cutting unnecessary weight from your bills can feel like a modest revolution.
When things are going well, clarity about money lets you spend on what truly matters to you: a trip, a course, time away from work, or a savings buffer. When life is difficult, it offers something more dependable-the sense that, however chaotic the outside world may be, you understand what is happening with your own figures.
At a human level, that is the real purpose of the process. It is less about chasing “gotcha” fees as a sport and more about refusing to sleepwalk through the part of life that determines where your time and energy can be spent. On a quiet evening with tea and a pile of bills, that is a surprisingly radical choice.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Map every monthly direct debit | List each payment and classify it as essential / useful / optional | Clearly see where money goes and identify “ghost” spending |
| Hunt down hidden fees line by line | Find service charges, added extras and quiet tariff increases | Lower costs without changing your standard of living, simply by removing what is unnecessary |
| Negotiate and create a monthly routine | Contact providers, ask for a better deal, then review accounts each month | Keep bills under control and avoid being hit by surprise increases |
FAQ
- How often should I review my monthly bills? Carry out a quick review once a month, then complete a more detailed check every 6–12 months to compare deals, challenge fees and renegotiate.
- Which bill should I check first to reduce costs quickly? Begin with broadband and mobile services. They often include add-ons and loyalty penalties, while providers are generally willing to offer deals when you mention competitors’ prices.
- How can I tell whether a charge on my bill is “normal”? Search online for the exact fee name alongside the company name and compare it with reports from other customers. Then ask the provider what it pays for and whether it can be removed or reduced.
- Is changing providers really worth the effort? Frequently, yes. A few hours of administration can save hundreds of pounds a year, particularly on energy, broadband and insurance.
- What if I feel embarrassed about calling and negotiating? Prepare a brief script, note down your key figures, and remember that you are not asking for a favour-you are deciding where to spend your money. That shift in thinking makes the call far easier.
Comments
No comments yet. Be the first to comment!
Leave a Comment