
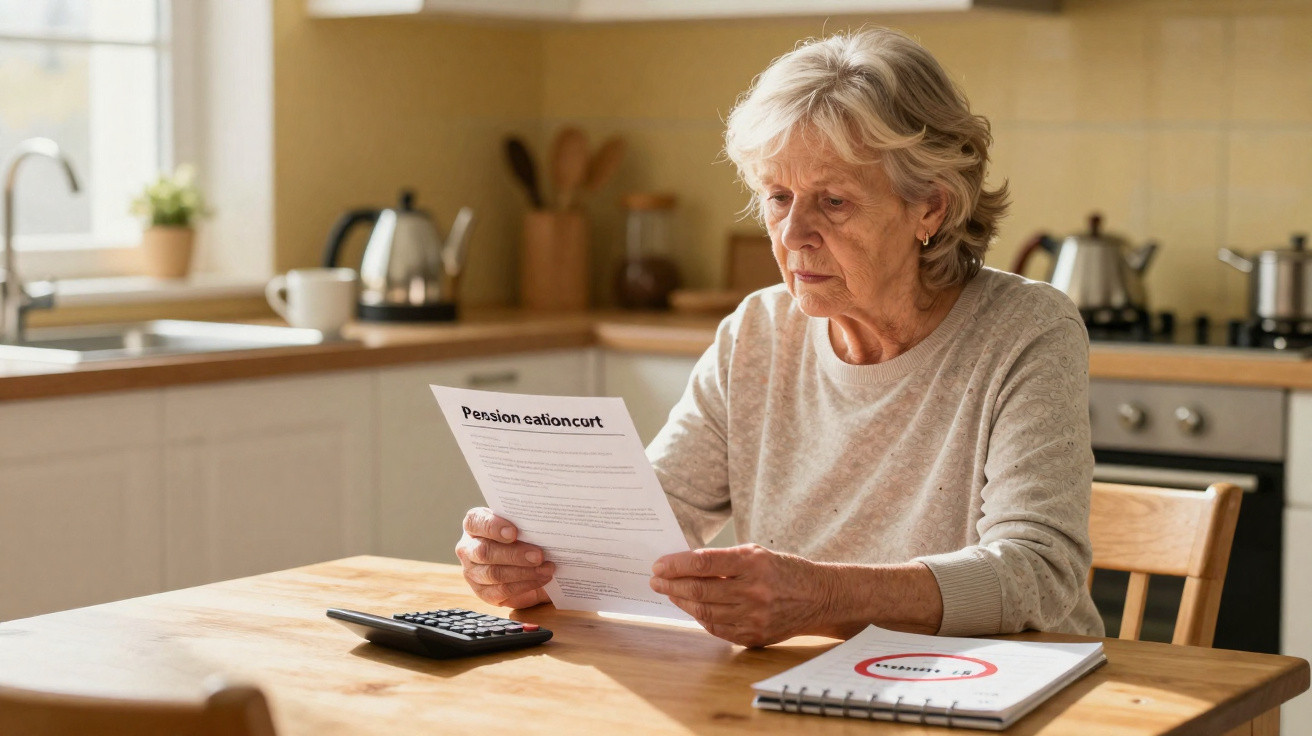
Margaret, 72, barely gave the letter a second glance at first. It was a slim white envelope lying on the doormat beside a takeaway leaflet and an appeal from a charity. Yet when she ran her finger beneath the seal and opened it, the message made the room seem to spin. “Your state pension award is changing from February,” it said, followed by a smaller amount printed plainly beneath it. Roughly £140 less each month. Almost £35 a week. More than she normally spends on groceries in a week.
She filled the kettle and watched it come to the boil, her eyes fixed on the energy-bill reminder attached to the fridge.
One thought kept circling in her mind.
What on earth happens now?
State pension cut: what’s actually changing from February?
A state pension cut due to start in February has been approved, reducing certain payments by approximately £140 a month. It will not affect everyone, it will not apply in every area, and the reasons will differ between claimants. Even so, the outcome is stark: less money reaching bank accounts that are already under strain. In a ministerial briefing, £140 may look like an abstract number. At home, it can mean keeping the heating on for only part of the day rather than from morning to night.
For those living alone, it is the sort of reduction that is felt each morning when they check their banking app.
Alan, 69, believed he had at last found a workable routine with his modest state pension and a little money from savings. He uses a notebook to record weekly costs, including groceries, bus travel and the “little extras” such as grandchildren’s birthday cards. When he worked through the revised figures in his notice - showing a reduction of around £140 a month linked to changes in his individual entitlement - he fell silent.
In one go, it would wipe out his broadband bill, mobile contract and most of a week’s grocery spending.
He made light of it during a call with his daughter, but afterwards caught himself counting the coins in his coat pocket, something he had not needed to do since the 90s.
The detail behind the reduction is hidden behind specialist terminology: entitlement adjustments, uprating calculations that fail to match living costs, and revised calculations for particular credits or supplements. Official paperwork describes this as “alignment”, “rebalancing” and, at times, “sustainability”. For the people affected, it simply means having less.
Over the past two years, prices have risen sharply while the income of many pensioners has barely moved - or has fallen.
The difference between money coming in and money going out is where anxiety takes hold, and February is set to drive more households into that position.
How to respond quickly before the state pension cut begins
Panic may be the immediate reaction. The next step should be to find a pen and paper. Before February, the most useful action is to create a completely honest picture of one month’s finances. Write down your state pension, workplace or private pensions, benefits and any extra income. Then list every regular essential cost: rent or mortgage payments, council tax, energy, insurance, broadband and debt repayments.
Once the revised pension amount is included - £140 less - you can identify the shortfall you really need to meet. It is not an estimate or a fear; it is a figure you can measure.
Seeing that gap clearly makes it easier to decide what can be changed, rather than feeling that events are simply happening to you.
Many people first cut back on modest pleasures, such as a monthly meal out, a streaming subscription or a Friday lottery ticket. That reaction is understandable and may sometimes be unavoidable, but it can also make everyday life feel needlessly restricted. A more effective approach can be to examine the larger bills that are rarely renegotiated: energy tariffs, broadband packages, mobile deals and insurance policies.
Most people know the feeling of realising they have remained on the same tariff for years simply because making the call feels too draining.
A 20-minute phone call or online conversation could reduce costs by £20–£40 a month, already making a dent in the £140 loss.
You do not need to deal with this on your own. A sudden change like this is precisely when an impartial, calm person can be useful. Local Citizens Advice offices, Age UK branches and independent money charities can review your income and spending, identifying overlooked support ranging from benefit entitlements to council assistance.
“I thought I was just stuck with the cut,” said one retired carer who spoke to a welfare adviser at his library. “In the end they found Housing Benefit I hadn’t claimed, and a reduction on my council tax. I’m still worse off, but nowhere near as bad as I’d feared.”
- Review whether you qualify for Pension Credit, Housing Benefit and Council Tax Support.
- Ask your energy supplier about hardship funds and priority support schemes.
- Speak to your local council about discretionary support with increasing costs.
- Check all direct debits from the previous three months and remove any unnecessary payments.
- Contact debt charities promptly if the reduction could cause you to miss repayments.
Living with less: how the £140 cut affects daily life
Away from budgets and acronyms, the reduction is likely to alter how some people manage from one week to the next. Losing £140 a month is not merely a calculation; it can mean turning the oven off sooner, taking less expensive bus routes or lying awake at 4am concerned about rent. Some people may share heating costs by spending longer at community centres, libraries or neighbours’ homes. Others may quietly use savings they had intended to protect for emergencies or funeral costs.
This sort of change affects more than your finances; it can work its way into your sleep, your mood and your feeling of security.
Money worries in later life can also bring an unspoken sense of shame. Even where the rules have changed around them, many pensioners think they “should have planned better” or “not be a burden”. In reality, few people can follow every government change or prepare a full financial projection each year. Policies can change rapidly, while people are occupied with day-to-day life.
Discussing the cut with relatives, friends or local groups may reduce some of that strain. The aim is not simply to complain, but to exchange practical suggestions that work in real life.
At times, the greatest comfort is hearing: “Yes, me too. I’m figuring it out as I go as well.”
There will inevitably be arguments over whether this reduction is fair, necessary or short-sighted. Some people will say the system remains generous by international standards. Others will highlight increasing food-bank use and record household energy debts as evidence that the safety net is coming apart.
Amid all that debate are your own bills and your own front door.
The way you adjust, the people you turn to for support and the decisions you challenge form the quieter story playing out in thousands of homes ahead of February.
| Key point | Detail | Value for the reader |
|---|---|---|
| Check your new pension figure | Go through every line of your latest DWP or pension letter and compare it with earlier payments | Helps avoid unpleasant surprises when the reduced payment arrives in February |
| Add the £140 “gap” to a new budget | Create your monthly budget again using the lower income figure | Makes clear exactly where the shortfall falls and what may need to change |
| Get support early | Speak to charities, councils and advisers before bills become overdue | Gives you a better chance of securing further help and preventing escalating debt |
FAQ: State pension cut and February payments
Who will be affected by the £140 state pension cut? Not all pensioners will receive an identical reduction. The £140 amount represents cuts and adjustments faced by some people from February, depending on their individual entitlement, earlier credits and the calculation of their pension components. Check your own letter or online statement in every case.
Is the triple lock being scrapped with this change? The frequently discussed triple lock concerns how the basic and new State Pension are uprated. This reduction relates to changes in individual payments and recalculations, rather than the complete removal of the triple lock. Even so, some people will see their personal monthly income fall.
What can I do if I can’t cope with the reduced pension? Your first action should be to speak with a free, independent adviser, such as Citizens Advice or Age UK. They can check for unclaimed benefits, support you in dealing with creditors and direct you to council and charity schemes. Do not wait until you have missed payments or accumulated arrears.
Can I challenge my new pension amount? If you believe an error has been made, you can request an explanation and, where appropriate, a mandatory reconsideration. Your pension letter and GOV.UK explain the procedure. It cannot overturn a lawful policy change, but it may correct mistakes in your personal record.
Should I draw down savings or a private pension to cover the cut? This is an individual choice that may affect tax, benefits and the length of time your money will last. Before using funds intended for the longer term, it is sensible to speak with Pension Wise or an independent financial adviser.
Comments
No comments yet. Be the first to comment!
Leave a Comment