
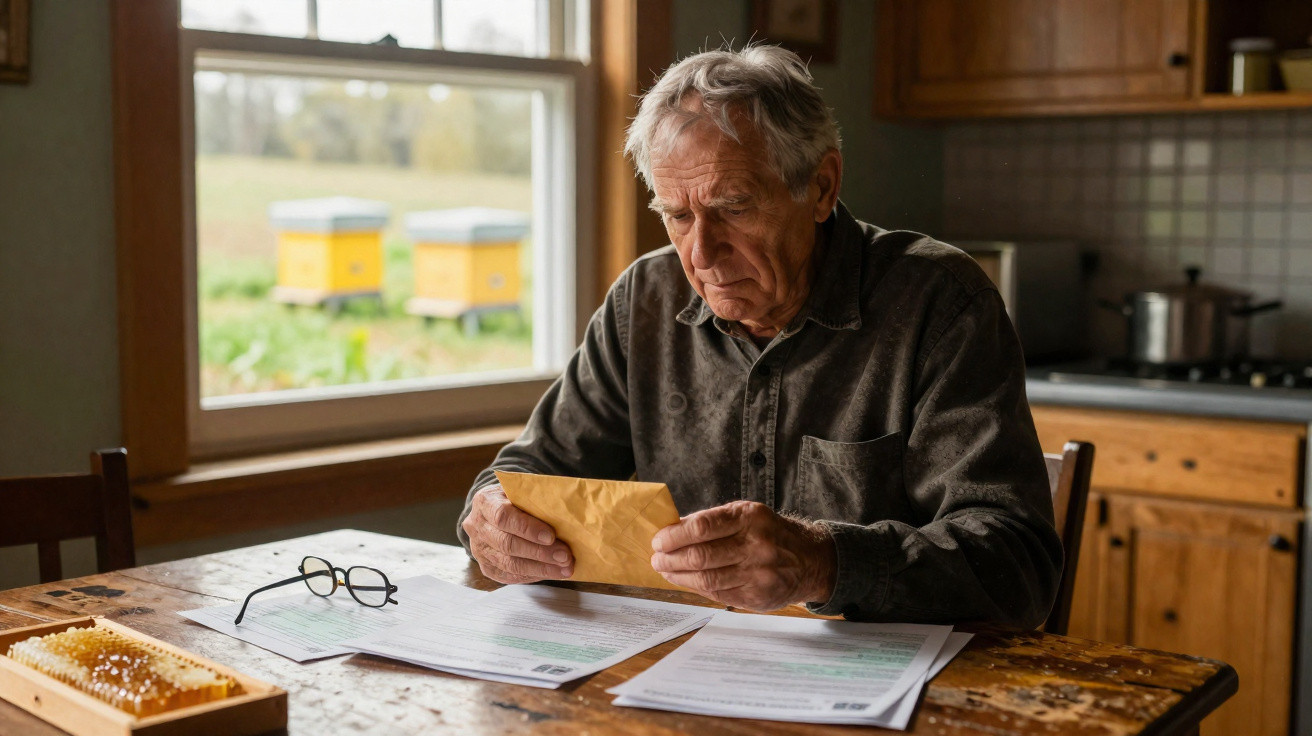
Paul assumed the brown envelope that arrived that day was another routine letter from the tax office. At the kitchen counter, coffee mug in one hand and his dog beside his feet, he opened it expecting a few ordinary details about his modest rural property. Then he stopped cold. The figure printed on the page exceeded his yearly salary.
The tax office wanted several thousand pounds from him. It was not because he had sold land, nor because he had built a home. It was for… allowing a neighbour to graze a handful of cows in his field.
He braced himself against the sink and read the letter three times, before reading it aloud once more, almost hoping the wording would somehow change.
How had an ordinary act of neighbourliness become such a costly snare?
When a simple field becomes a financial minefield
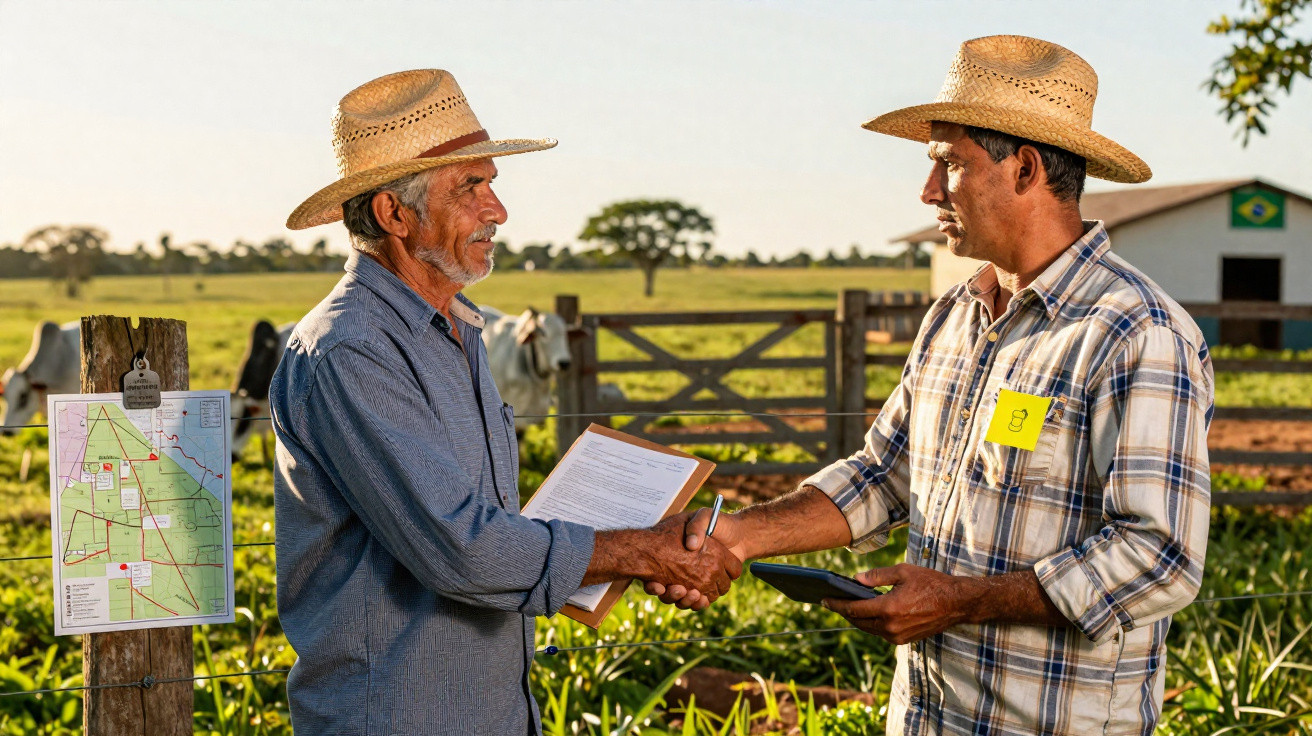
On the surface, the situation seems almost idyllic: a retired teacher with an unused field on a village edge; a young farmer unable to find reasonably priced grazing; a handshake across a fence. There were a few cows, several bales of hay and the steady calm of country life. No contract was drawn up and no cash changed hands, only: “Use it if you like, I’m not doing anything with it.”
Several months later, the same arrangement appeared very different beneath the harsh lights of a tax inspector’s office. The authorities did what they are designed to do: they connected the facts. Agricultural land was being used by a farmer who did not own it. They therefore viewed the arrangement as a standard tenancy, with income, responsibilities and a tidy category within the tax code. The fact that rent had never even been discussed did not fit neatly into the relevant form fields.
Paul is not alone in this experience. Throughout Europe and North America, landowners are learning that “letting someone use a field” may set off a series of unforeseen outcomes: the land can be reclassified, property tax can be reassessed, certain reliefs can be lost, and charges can even be applied retrospectively for several years. The reasoning is detached but clear: as soon as land is deemed to be “in productive use”, the tax system no longer sees generosity; it sees a possible source of revenue. In the tax office’s view, revenue should not escape tax.
The small details that can change everything with the tax office
The gap between “I’m helping my neighbour” and “the state sees me as a small-scale landlord” can be remarkably narrow. Often, it is found in details that hardly seem worth considering. Was permission recorded in writing? Did the farmer repair fences or cut hedges “instead of rent”? Did the owner claim agricultural use on local paperwork to access reduced rates? Considered separately, each detail may appear harmless, but together they can resemble a complete commercial arrangement.
Consider Sophie, who received three hectares from her grandparents. An elderly farmer had cut hay there twice each summer for years. She never received any payment; in return, he kept the access track clear and cut back the hedges. During a municipal land-use review, her fields were identified as “actively farmed”. Her local property tax category changed overnight. Officials maintained that the upkeep had an obvious economic value and counted it as undeclared rent paid in kind. The retrospective demand covered four tax years. She wept while speaking to a clerk by telephone, and he quietly said that he had encountered the same situation many times.
The rationale behind such rulings is starkly straightforward. Tax authorities administer systems rather than personal stories. If land is in use, they presume there is a benefit. If there is a benefit, they presume there is some sort of income. And if income is present, they expect it to be declared. Agricultural land rules, rural reliefs and capital gains provisions are packed with technical conditions that may alter the outcome completely. One box ticked on a form, an old letter sent to the town hall, or an offhand reference during an inspection to “the farmer who uses my land” can set the process in motion. The tax code doesn’t really have a chapter for “I was just trying to be nice.”
How to lend a field without being crushed by the small print
When you own land and somebody asks, “Can I use your field?”, the safest response is to say nothing until you have done some basic checking. That does not mean locking the gate and refusing to help. It means taking a moment, finding a notebook and noting three essential questions: Will any money be paid? Will work or maintenance be provided in return? Will the official description of the land’s use change? Those three issues form the basis on which most tax systems decide what arrangement you have actually entered into.
A brief and unambiguous written agreement is not excessive caution; it protects everyone involved. Even a half-page note stating, in plain terms, “no rent, no exchange of services, no commercial activity created for the owner” may make matters clearer later. Having a local accountant or rural notary review it is far cheaper than receiving an unexpected tax demand. Before a tractor enters the field, it is also sensible to contact your insurer and ask, “A farmer wants to use my field, what does that change?” The answer may not be what you expect.
Many owners feel uncomfortable even raising these issues. They may think, “It’s just a field, I don’t want to treat my neighbour like a client.” This is precisely how difficulties arise. In truth, hardly anyone reads every line of the small print on annual property tax notices. Yet those understated passages often refer to agricultural use, business activity or special reliefs associated with the way land is occupied. Overlooking them will not remove their effect.
Sometimes the kindest thing you can do for your future self is to turn a vague favour into a clear, simple agreement today.
- Before lending – Telephone your local tax office anonymously and explain the arrangement in straightforward language. Ask which category applies to you.
- Put it in writing – Prepare a short note confirming whether there is rent, any service, or no compensation whatsoever. Both parties should sign and retain copies.
- Discuss insurance – Check whether farm machinery, livestock and third-party incidents in the field are insured, and establish which policy provides cover.
- Monitor the forms – A request to “update land use” may carry tax consequences. Find out why it is required and exactly what it will alter.
- Set a time limit – A defined beginning and end date can stop a “temporary favour” from being viewed as a long-term commercial arrangement.
When generosity encounters bureaucracy, who should give way?
Cases such as Paul’s strike a sensitive point because they involve more than tax rules: they expose the tension between rural mutual support and institutional reasoning. For many people, a field is more than an entry in the land registry. It represents childhood, family history and the surrounding landscape. Letting a farmer use it can feel like the right thing to do for the community. When a bill follows, kindness can suddenly feel like an error.
The oddity is that each person involved often believes they are simply fulfilling their role. The farmer is trying to stay afloat while land costs rise. The tax official is applying rules intended to prevent abuse and concealed income. Meanwhile, the landowner looks at the envelope and wonders when good neighbours began to need legal advice to share a meadow. There is considerable misunderstanding between these three perspectives, but very little dialogue.
Perhaps change begins quietly there: with earlier and more open conversations. Owners can ask uncomfortable questions before giving someone a gate key. Farmers can be clear about how they declare the land they work. Local officials can explain in ordinary language how a simple favour may be safeguarded rather than penalised. The next time somebody leans over a fence and asks, “You’re not using that field, are you?”, the sensible reply may be neither yes nor no. It may be, “Let’s sit down for ten minutes and get this clear, so it doesn’t bite either of us later.”
| Key point | Detail | Value for the reader |
|---|---|---|
| Hidden tax triggers | Land-use reclassification, benefits in kind and undeclared “rent” may all result in unexpected demands | Helps identify where a simple favour could begin to resemble taxable income |
| Put it in writing | A brief, plain agreement confirming there is no rent or service protects both the owner and the farmer | Lowers the likelihood of confusion with tax authorities and insurers |
| Ask early, not late | Contact tax offices, notaries and insurers promptly before allowing use of the field | A small number of early questions may prevent thousands in surprise charges later |
FAQ:
- Can I let a farmer use my field for free without paying extra tax? Often, yes, but only where there is truly no rent, no concealed exchange of services and no alteration to the land’s classification. If you receive a “benefit”, tax rules may treat it as income.
- Does maintenance count as rent in the eyes of the tax office? It may do. Where a farmer fixes fences, clears ditches or maintains access “instead of paying”, that work can be treated as rent in kind with an assumed value.
- Should I sign a formal agricultural lease with my neighbour? Not in every case. A straightforward agreement for use can sometimes be sufficient. Although a formal tenancy can provide protection, it may also commit you to lengthy obligations. Local legal advice is essential.
- Can lending a field change my property tax band? Yes. Reclassification as “actively farmed”, or an association with a business, can affect local rates and access to particular reliefs or exemptions.
- What’s the safest first step before I agree to anything? Explain the arrangement anonymously to a local tax adviser or rural notary and ask which form of agreement keeps you outside the “undeclared income” zone.
Comments
No comments yet. Be the first to comment!
Leave a Comment