
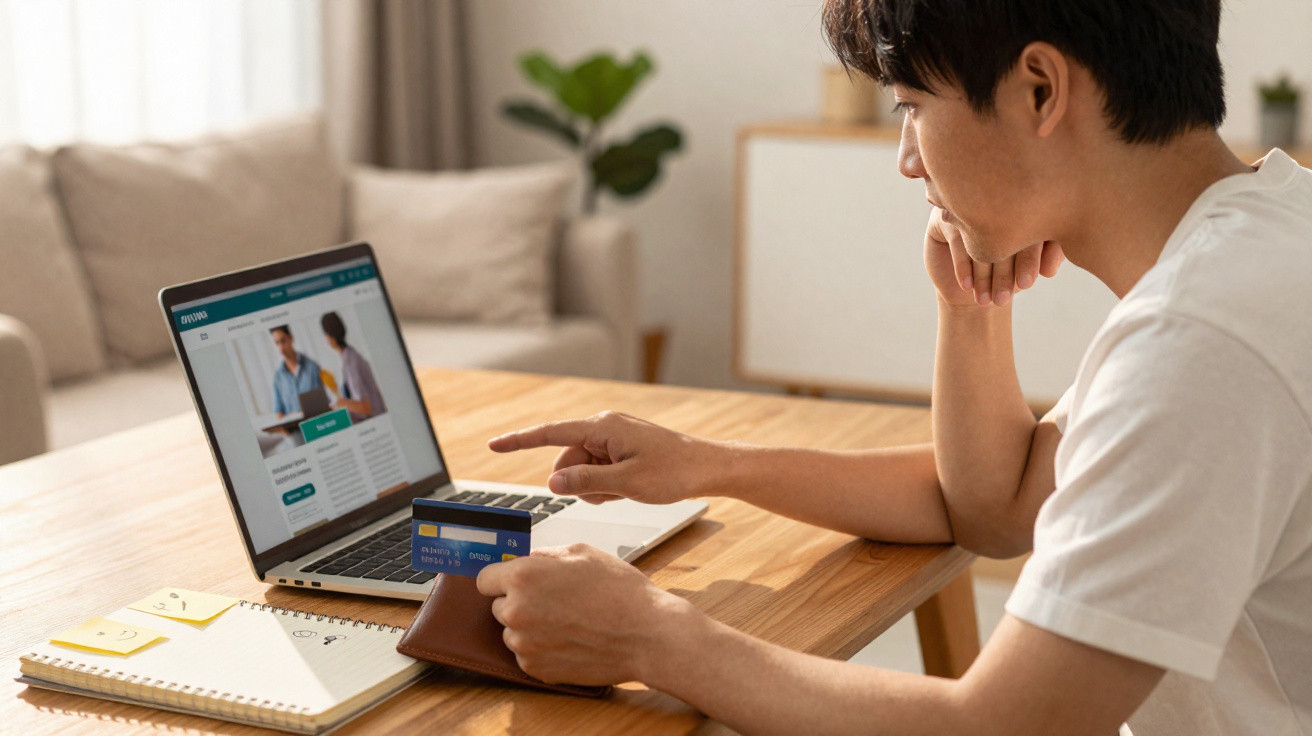
The screen lights up your face. It has been a long day; you are tired, a little drained. Then, without giving it much thought, it is done: order confirmed. There is a brief rush of pleasure, a small hit of adrenaline, followed by guilt, a grim look at your bank balance and the silent promise to “do better next month”.
We have all had those moments when a bank card becomes a kind of emotional plaster. Repeated dozens of times each year, the action feels harmless, almost ordinary. Yet, accumulated over several years, it creates a financial reality far heavier than we care to admit. Behind every impulse purchase is almost always a particular emotion: often overlooked, sometimes buried. Until you can name it, it keeps quietly taking the wheel.
The scene often unfolds in familiar settings: on the sofa, in an open-plan office, on the Tube, or in bed late at night. The items and baskets may differ, but the emotional script returns with striking regularity. So the real question is not, “Why am I buying this?”, but, “What am I trying to feel – or avoid – when I click?” The answer can be unsettling. That is exactly why it can be freeing.
Recognising the emotional triggers behind the click
Before discussing budgets or numbers, it is worth looking at the emotional backdrop. Most impulse purchases do not come from a genuine need, but from a sudden feeling: boredom, loneliness, stress, frustration or the need for a reward. The online shopping site then becomes a vending machine for quick emotions. One scroll, one basket, and your mood seems to lift slightly.
What stands out when you examine spending habits as a journalist might is the repetition: the same times, the same days and the same circumstances. These habits have a logic, even if they initially appear irrational. Emotional triggers are not accidents; they are almost programmed.
Take a simple example: Sarah, 32, a graphic designer, swears she does not “understand” where her money goes. When she reviews three months of bank statements, a brutally clear pattern emerges. Orders for clothes and home décor items surge on Sunday evenings, between 9 pm and 11 pm, always after a weekend she considers “not productive enough”. She is not spending for the pleasure of shopping. She spends to numb a mix of guilt and vague Monday anxiety.
Another example is Karim, 27, who works remotely and regularly orders tech gadgets and delivered food between 3 pm and 5 pm. He says he has “a weakness” for special offers. In fact, his spending peaks at exactly the point when his concentration collapses and he feels alone in front of his screen. The emotional driver is not the offer but the need for a break and stimulation. The basket is a 2.0 coffee break, paid for by card.
In both cases, the impulse purchases are not random. They follow an exceptionally consistent emotional pattern. Emotions look for a quick outlet, and online shopping provides an escape route within easy reach. Once you notice this, your inner dialogue changes. Rather than telling yourself, “I am useless with money”, you can say, “That is the emotion that makes me overspend, at this particular time.” The shift is subtle, but it turns a vague mistake into a specific behaviour that can be observed, named and then addressed.
Turning emotion into a conscious choice
Identifying emotional triggers is one thing; using them to build financial discipline is another. One straightforward method is to keep a “shopping urge journal”. It does not need to be a perfect spreadsheet or a complicated app. Simply jot down a few lines on your phone: the time, place, emotion felt, item wanted, and whether you bought it. To be honest, no one really does this every day. But even a few carefully chosen days can reveal surprisingly clear patterns.
With every urge to buy, write something like: “5:12 pm, office, exhausted, want £129 headphones, did not buy.” Or: “10:45 pm, bed, feeling a bit sad, want to book a weekend away, basket checked out.” This small act of observation creates a brief pause between the emotion and the action. That tiny gap is valuable: it is where financial discipline starts to emerge. You do not suppress the feeling; you look at it, give it a name and postpone the purchase, even if only for a few minutes.
Another practical approach is to introduce an “emotional delay rule” before every non-essential purchase. For instance, anything over £30 requires a 24-hour pause. During those 24 hours, do not simply repeat, “I need to be sensible.” Ask yourself instead: “What exactly was I expecting this item to give me when I wanted to buy it?” Writing the answer in a note or a message to yourself breaks the illusion of urgency. The purchase is no longer an automatic reaction; it becomes a considered decision.
The common mistakes here are deeply human. We judge ourselves too quickly. We tell ourselves that we “have a problem with money” or “have no willpower”. We assume the answer is more income, more control or more discipline. What we forget is that the bank card is often only an emotional thermometer. Shame never helps to build discipline. It merely makes you want to avoid bank statements, ignore notifications and look away. Avoidance is an impulse purchase’s best ally.
Another trap is believing that deleting shopping apps or unsubscribing from every newsletter will solve the problem. It may help for a while, of course, but the emotion itself does not disappear. It finds other outlets: food, games or subscriptions. The real work is accepting that you are seeking something through these purchases: comfort, distraction or a sense of personal worth. Then you can find less costly ways to meet that need.
Financial discipline that lasts is rarely harsh. It is gentle, repetitive and sometimes a little uneven. There will be setbacks: baskets checked out on an exhausting evening and regrets afterwards. The aim is not perfect behaviour, but gradually reducing how often purchases are driven by an unrecognised emotion. Every time you put a word to what you feel just before clicking, you strengthen a quiet muscle: the muscle of conscious choice.
“Money spent impulsively is not just a matter of numbers; it is often an unspoken conversation between our tiredness, our need for affection and our wish to prove something – to ourselves or to others.”
To keep that conversation in sight, some people create a kind of “emotional emergency kit” to use before any impulse purchase. Keep a few simple ideas somewhere accessible, either on your phone or on an actual Post-it note:
- Send a message to a friend before making any purchase above a set amount.
- Go for a five-minute walk without your phone whenever a strong urge to buy appears.
- Every other time, replace an impulse purchase with a free or very low-cost action: a phone call, a hot shower, a playlist or a notebook.
- Create a “Review in 7 days” list, recording every shopping urge along with the date and the emotion felt at the time.
- Set aside a small monthly budget for “controlled treats” to channel the urge to splurge without derailing everything.
Building financial discipline that respects your emotions
The real turning point comes when you stop treating financial discipline as a punishment and start seeing it as a form of self-protection. Recognising your emotional triggers is like learning to read your internal weather forecast before heading out without an umbrella. You know that on days marked by tiredness, loneliness or stress, the risk of spending without thinking rises sharply. Rather than relying solely on mental strength, you prepare in advance: set a lower payment limit, leave your card at home or activate bank notifications.
Another powerful step is to connect every pound “saved” from an impulse purchase to a tangible, visible project. Not vague, distant, impersonal savings, but a meaningful goal that resonates emotionally: a particular trip, a financial safety cushion to leave a toxic job, or a “freedom” fund that lets you dare to say no. Each time you resist an emotion-driven purchase, you are not merely going without it: you are funding that project. You might even write it down: “Today, £35 more towards my future sabbatical month.”
Over the weeks, a quiet change takes place: pride gradually replaces guilt. You no longer define yourself only by the times you gave in, but also by all the clicks you did not make. That kind of pride is more dependable financial fuel than fear of a difficult end of the month. It rests on a simple truth: you can feel intense, uncomfortable emotions and still choose what to do with your money. Stress, loneliness and boredom no longer control you completely. You begin to take the lead.
This transformation is often visible in the smallest details: a shopping session postponed, a basket left waiting, or an evening spent speaking honestly about money with someone close to you. Money management then stops being a battlefield. It becomes a mirror: sometimes demanding, but far more faithful to the person you are becoming. Your bank balance no longer tells only the story of your emotional weaknesses. Little by little, it starts to tell the story of your choices.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Identifying emotional triggers | Observe the times, places and feelings that come before impulse purchases | Better understand why money “disappears” without feeling like a deliberate decision |
| Creating space between emotion and purchase | Shopping urge journal, delay rule, emotional emergency kit | Turn a quick urge into a more thoughtful, aligned decision |
| Connecting discipline to a tangible project | Assign every avoided expense to a specific, motivating goal | Give financial effort meaning and strengthen long-term motivation |
FAQ
How can I tell whether a purchase is genuinely impulsive or simply spontaneous? An impulse purchase often comes from a powerful, sudden emotion, alongside a feeling of urgency and sometimes an “all or nothing” mindset. A spontaneous purchase, by contrast, still fits your budget and priorities, even if it was not on a list.
What can I do if my emotional triggers are linked to work-related stress? Start by identifying the exact times and situations in which you give in. Then replace some of that spending with non-financial micro-rituals: go for a walk, call someone, write down what you are feeling or move to a different space for a few minutes.
I feel so guilty after every impulse purchase; is that helpful? Guilt can signal a mismatch between your values and your actions, but when it is turned against yourself, it holds you back. The aim is not to judge yourself, but to ask calmly: “What was I trying to feel or avoid at that moment?”
Will tracking all my spending make me obsessed with money? If tracking is simple, human and linked to your emotions, it becomes a tool for clarity rather than rigid control. The goal is not perfection, but awareness: seeing what is happening without drama, so that you can adjust.
Can years of impulse purchases really change just by working on emotions? Financial habits run deep, but they can still be reshaped. Recognising your emotional triggers will not instantly remove shopping urges, but it reduces their power and frequency. Over a few months, that difference can completely alter your financial landscape.
Comments
No comments yet. Be the first to comment!
Leave a Comment