
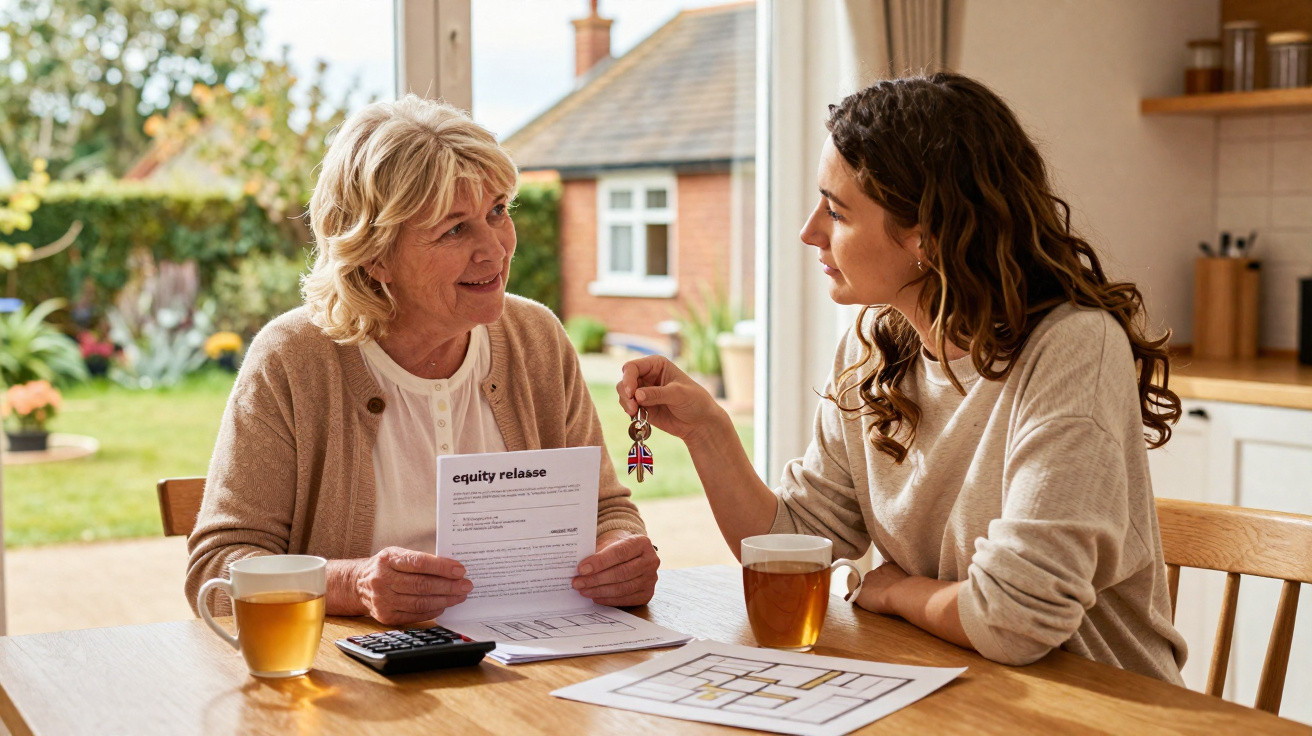
Her gas direct debit has risen yet again, but her pension has not. In the winter sunshine, her semi-detached home on a peaceful English cul-de-sac appears quietly prosperous from outside. It was paid off decades earlier and is now valued at well over £400,000. Officially, she is “comfortable”; in practice, she is searching “help with bills over 70” on an ageing iPad.
Her son has casually raised the subject of “equity release”. A 78-year-old neighbour has recently used it to pay off credit card borrowing and renovate her bathroom. “You’re sitting on a goldmine, Mum,” he tells her. Yet the phrase she remembers from childhood is very different: “Never touch the house.” It is one postcode containing two opposing views.
Equity release in the UK was once discussed in hushed tones, almost as though it were a family embarrassment. It is now steadily becoming more mainstream. A significant change is under way.
Why equity release is suddenly on everyone’s radar
Visit a suburban café at 11am on a Tuesday and listen in. At a table by the window, there may be two people in their seventies discussing “releasing some money from the house”. They are not financial advisers, but grandparents swapping experiences over cappuccinos and flu jabs.
Property wealth has increased dramatically over several decades, particularly in the South and in expanding cities, while retirement income has failed to match it. The divide between the value of a home and the money available in the bank has become a source of quiet anxiety. For an increasing number of older people, equity release seems less taboo and more like a practical option.
The industry figures support what is being discussed in those cafés. The Equity Release Council reports that lifetime mortgages account for the overwhelming majority of plans, with the total sum released every year reaching billions of pounds.
The typical customer is often in their early seventies and owns a property worth considerably more than they ever expected when buying it. Many are not spending the money on sports cars. Instead, they are clearing remaining interest-only mortgages, assisting adult children with deposits, or easing the effect of higher everyday living costs.
A London couple in their late sixties used equity release so that they could finally retire at the same time. Their Walthamstow flat had first doubled and then trebled in value. They looked affluent on paper, but in reality kept working because they feared running out of money. A lifetime mortgage enabled them to clear the final balance on their conventional mortgage, supplement their pensions and remain in the home they loved.
The force bringing equity release into focus is stark but straightforward. Millions of Britons are asset rich but cash poor. House prices have outpaced salaries and pensions, children find it difficult to buy homes, and possible care costs sit in the future. The largest pool of money available is therefore tied up in the home. For years, using that money felt like a failure.
As fixed-rate deals expire, interest rates fluctuate and everyday costs rise, that emotional resistance is starting to weaken. People see a six-figure amount locked into bricks and tiles and ask themselves why life should feel financially strained when their home may be worth more than their entire lifetime’s earnings.
Equity release addresses that issue by converting part of a property’s value into tax-free cash while allowing the owner to remain at home. However, it also has a reputation for unwelcome surprises, which explains why it still causes arguments around the Sunday lunch table.
How to approach equity release without blowing up family peace
Older people who handle equity release most successfully generally begin well before signing any documents. They collect brochures, watch the somewhat awkward television adverts and arrange a free initial discussion with an independent adviser rather than someone connected to only one lender.
One practical step can make a major difference: involving adult children or a trusted friend early in the conversation. This is not about seeking permission, but about preventing surprises. It means explaining the approximate value of the home, the amount being considered and the intended use of the money. When everybody understands the plan, there is less opportunity for resentment to develop later.
Comparing products is another understated but important approach. The equity release market has changed quickly. Certain plans permit voluntary repayments, so interest does not compound quite as severely. Others restrict how much the debt can increase in relation to the property’s value. Looking through these details alone can be tiresome; with an adviser and an interested family member, it becomes less intimidating and more of a shared task.
A common mistake is to regard equity release as free money. It is not. It is a loan secured against the home, and interest can compound over many years. Where repayments are unavailable or unsuitable, the debt can rise more quickly than people anticipate.
Many older people feel guilty merely considering a reduction in what they leave to their children. Others feel equally uncomfortable asking those children for help, and would rather borrow quietly against their home. Both responses are understandable. The important thing is to acknowledge those feelings openly rather than allow them to drive secret choices.
Let us be honest: hardly anyone genuinely does this every day. Reading key facts illustrations, asking “what happens if I live to 95?”, and checking charges for moving home or repaying early can feel like paperwork from another world. An adviser experienced in supporting anxious retirees can take things slowly and explain the jargon.
One woman from Leeds described her turning point this way:
“Once my daughter sat next to me and we called the adviser together, it stopped feeling like I was doing something sneaky. It became a family choice, not my dirty secret.”
For many people, this is the emotional centre of the issue. For decades, the home stood for sacrifice and security. Releasing part of its value can feel like letting down the younger version of yourself who saved every penny for the deposit. Yet it may also protect the older version of yourself from cold winters and unpaid bills.
To stay clear-headed, it can help to put the following in writing using plain English rather than financial language:
- Why the money is needed now: bills, debt, helping children, home adaptations or experiences.
- Which alternatives have been properly considered: downsizing, taking in a lodger, a conventional loan or family support.
- The inheritance trade-off you are willing to accept in exchange for a better quality of life today.
This brief list can be unexpectedly reassuring when glossy brochures and large figures begin to overwhelm you. The aim is not perfection, but honesty with yourself and with those who may eventually inherit your front-door keys.
The quiet cultural shift behind equity release’s rise
A subtle change is taking place in living rooms throughout Britain. The old belief that “the house must be preserved for the children at all costs” is becoming less fixed. In many cases, adult children are gently encouraging their parents to make use of the money they worked to build up.
Across the country, similar words are heard: “We’d rather you were warm and comfortable now than leave us a slightly bigger lump sum one day.” That does not remove the sense of guilt, but it changes how the decision is viewed. Inheritance can be distributed over time through help with childcare, deposits or simply fewer financial worries for Mum and Dad.
Policymakers have also taken notice at a national level. The demographic reality is clear: more people are living longer, pension provision is uneven, and trillions of pounds remain locked in housing equity. Equity release, especially lifetime mortgages with protections such as no-negative-equity guarantees, has become part of the wider toolkit for easing pressure on public finances, even if this is rarely stated openly.
This is why a product that was once controversial is now tightly regulated, extensively advertised and presented as a retirement-planning choice rather than a last-resort escape route.
Most people have experienced the moment when a relative quietly says they have “taken something out of the house”, lowering their voice slightly. A decade ago, the room may have fallen silent. Today, responses are more varied. One sibling asks about interest rates, another questions whether the home could be lost, while somebody else says, “My mate’s mum did that, it worked out alright.”
Equity release now sits in that mix of concern and interest. It is no longer a niche product, but it has not yet become entirely normal either. In fact, that middle ground may be useful. The remaining unease prompts more questions, more second opinions and closer attention to the small print. Older people deserve all of those safeguards when their biggest asset is involved.
The emotional conclusion is straightforward. Equity release is neither a miracle solution nor a villain; it is a tool. Used without care, it can reduce an inheritance and restrict future choices. Used carefully, with frank family discussions and suitable advice, it can turn bricks into breathing space.
For some people, that means paying for home adaptations so they can remain independent. For others, it covers modest pleasures, such as regular train journeys to visit grandchildren or one final major adventure while health permits. For a growing number of British older people, that exchange feels worthwhile. Quietly, equity release is becoming less of a scandal and more of a question: what is a home for, if not to help us live the years within it as well as possible?
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Equity release = loan on your home | Tax-free cash from property value, usually repaid when you die or move into long-term care | Understand the basics before speaking to an adviser |
| Family dialogue changes everything | Involving children early can reduce conflict and guilt while highlighting alternatives | Protect family peace and relationships |
| Modern plans are more flexible | Options include voluntary repayments, downsizing protection and no-negative-equity guarantees | Identify less risky offers that are better suited to your circumstances |
FAQ:
- Is equity release always a bad idea for inheritance? Not always. It will usually reduce what remains, but it can improve your quality of life and may help your family sooner, for instance with deposits or school fees.
- Can I be forced to leave my home after equity release? With regulated lifetime mortgages, you would normally retain the right to live in your home for life or until you move into long-term care, provided you comply with the plan’s terms.
- What happens if house prices fall in the future? No-negative-equity guarantees mean that you will not owe more than the property’s sale value, even if prices decline, provided the plan is from an approved provider.
- Is downsizing a better option than equity release? It may be. Selling and moving can release more money and lower running costs, but it also involves the stress of moving and leaving familiar surroundings. Many people consider both options carefully before deciding.
- How do I know if I’m getting fair advice? Seek an independent, FCA-regulated adviser who can access several lenders, explains charges in plain English and does not pressure you into signing anything.
Comments
No comments yet. Be the first to comment!
Leave a Comment