
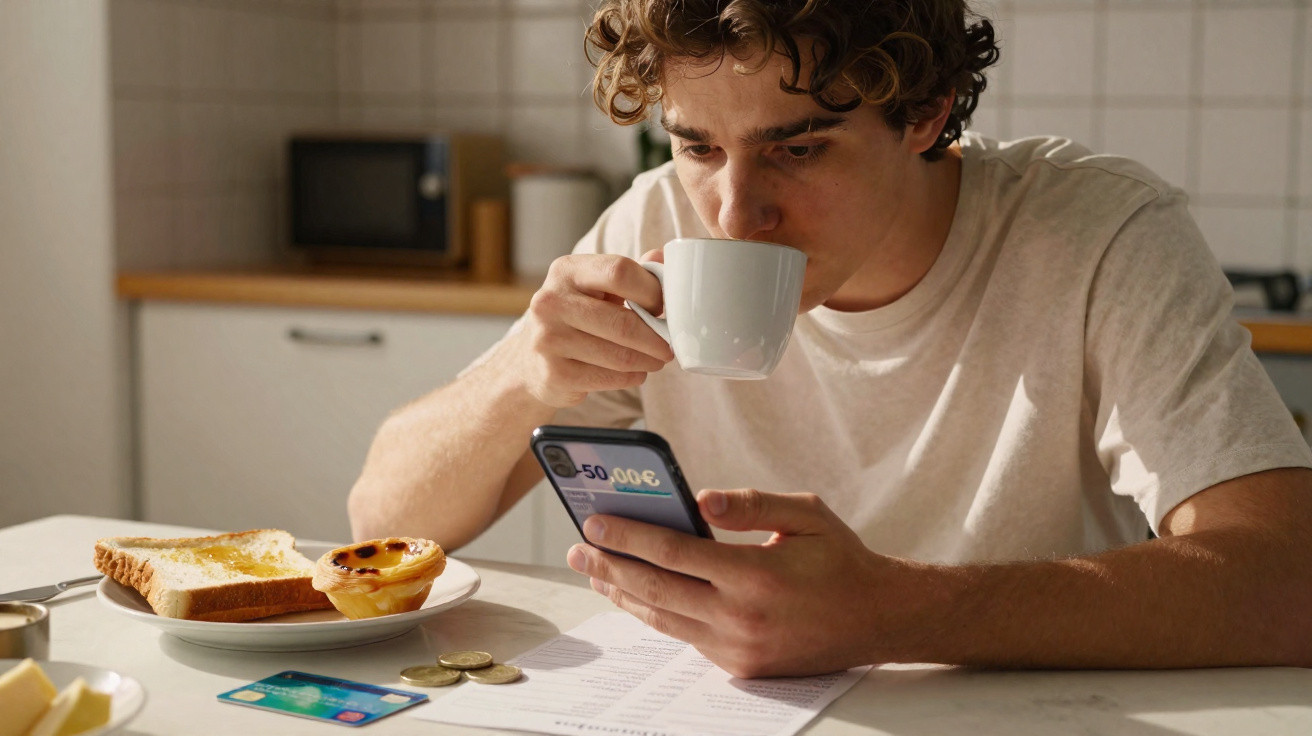
“I’d been careful all month, the kind of careful that means saying no to the after-work taxi and bringing your own lunch in a tub that’s seen better days. I opened my banking app and there it was, a clean $50 gone - neat as a haircut, leaving a straight line where my money used to be. It wasn’t a subscription I recognised, not a cheeky late-night purchase or an energy bill. It wore a polite name, and that’s what made it feel worse. Numbers don’t shout when they leave your account. They tiptoe.”
I later realised that something much like this could be quietly happening to you every month, with all the appeal of a direct debit nobody recalls authorising. The key is to know where to check before yet another month disappears.
The morning “maintenance” took my breakfast money
The entry on my screen did not appear sinister. It was orderly and official-looking, the sort of wording that could easily blend into ordinary banking. “Service plan,” “account fee,” “monthly maintenance,” “protection pack.” Those phrases are designed to be skimmed over. I made a tea, sat at the kitchen table and enlarged the details. The charge date was almost identical to the previous month’s, and I felt that sharp, warm rush behind the ribs we call embarrassment.
It was not because I had made a mistake, but because I had failed to spot it. We scan. We trust. We tend to assume any money gone missing must be our own fault. A modern bank statement is a woodland, and this is the fox weaving through it. I phoned the bank and asked precisely what the plan covered. The adviser followed a script, while the explanation remained hazy, like a dream fading moments after you wake. It was a package of benefits I never used: mobile phone insurance I already held, and airport lounge access I would never use.
The dull label that can cost you $50
Here is the uncomfortable reality: these charges frequently sit behind friendly, administrative-sounding descriptions. “Maintenance.” “Service.” “Membership.” Anything that resembles routine housekeeping can get past your internal alarm. US banks still impose monthly maintenance charges unless you maintain a minimum balance. In the UK, some accounts come packaged with benefits in return for a monthly fee. It does not feel like theft; it feels like the cost of owning a working card and an app that loads.
The total grows more quickly than expected. Fifty dollars per month becomes $600 annually: enough for a good weekend away, or for the unexciting but essential emergency fund we are always urged to create. If you think it could not apply to you, bear this in mind: these fees do not deliver one sharp sting; they slowly drain you. Their names remain deliberately dull, like wallpaper you have stopped seeing.
When the figures simply do not make sense
Most of us have had that moment of scrolling through transactions and murmuring, “Wait, what’s that?” You search the merchant name online and find only a bland corporate website, one that does not refer to you personally but lists a series of “benefits”. The further you investigate, the more likely it seems that you agreed to it somewhere along the way, perhaps on a hurried Tuesday when opening the account and simply needing somewhere for your wages to go. Banks understand that life is hectic, and they build products around busy people.
In truth, nobody downloads PDF statements daily and examines them like an auditor. You notice the rent, supermarket spending and phone bill, then carry on. That gap in attention is where the charge prospers: one modest, regular siphon that becomes embedded in your finances. Once you see it, you can feel irritated and strangely relieved at once, as though you have finally located the drip tapping within a wall.
How the quiet leak begins
Sometimes the leak starts with a free trial for a “premium” account, then continues beyond its end date. At other times, it begins with a sales pitch at the branch counter: you are flustered, you sign, and leave smiling with a welcome pack you never read. It may be an overdraft “protection transfer” charge, moving funds from a linked account for a fee even when the transfer does not prevent any meaningful hardship. Or it could be a monthly fee for paper statements that you did not realise still existed. Modern banking is structured around defaults. When the default is set to “on”, most people do not switch it off.
The industry describes this as sound product design: more features, different tiers and more choice. Yet choice without obvious ways out becomes a maze, and mazes make exhausted people spend. You are not expected to notice every small lever. You are meant to feel fortunate to have the product. That is how a $50 gap can pass unnoticed during a month in which you monitored every coffee and compared every detergent on offer.
The psychology behind a quiet leak
A monthly outgoing can feel like rent, so you accept it. Our minds dislike reassessing expenses already categorised as “normal”. That is why subscription companies value the monthly cycle: it soothes and conditions you. Banks are no exception. A slight shift in wording - “included”, “pack”, “plan” - makes a charge seem like a feature rather than a fee.
Shame also plays a part. You may feel you ought to have known. You might tell yourself that contacting the bank will consume an hour and a small piece of your soul, so you avoid it. The money goes out, the month finishes, and the cycle restarts. Eventually, the budget creaks and you look properly. I don’t remember buying anything worth $50; the money just… dissolved.
What could be charging you $50?
Banks do not all use the same descriptions, and neither does every country rely on the same approach. In the US, it is commonly a “monthly maintenance” charge triggered when your balance falls below a set level, or a “relationship” fee for not holding several products. Some banks add repeat “overdraft protection transfer” fees when your balance remains close to zero. In the UK, packaged bank accounts may cost £10–£20 each month for benefits that sound attractive but duplicate insurance or cover you already have. Add another modest cost - an international usage fee from a service billed overseas - and you can reach the $50 point without realising.
There are more unusual examples too: a postal statement fee, card protection or identity cover you never requested, or a service charge on a dormant foreign-currency balance. There may even be an add-on intended to “help prevent fraud”, despite the fact your bank already protects against fraud. These charges sit in the centre of your statement rather than at its edges. They do not flash for attention. They simply remain there.
How to spot it in five minutes
Open your banking app and search for entries repeated on the same date every month, particularly names that sound administrative rather than part of real life. Watch for “maintenance”, “monthly service”, “pack”, “plan”, “membership”, “protection”, “paper statement”, “overdraft transfer” and “international service”. Open the transaction details, then review the merchant ID or any help link. If a telephone number is listed, ring it. Where there is a contract link, open it and read the first two paragraphs rather than the marketing strapline.
Next, review the previous three months and write down every recurring payment you cannot explain in a single sentence. If you hold more than one account, inspect every one, especially the spare account where money arrives and sits. That is where fees like to settle. Take screenshots of questionable transactions, so you have dates to cite when you call. For a packaged account fee, look through your inbox for the original welcome message; it often contains cancellation instructions that the app does not make prominent.
Review the last three months of statements and look for every monthly repeat you cannot identify in five seconds.
What to say when you phone the bank
Keep it straightforward. Ask the adviser to describe the charge in plain English, then ask if it is optional. If it is, request that it be removed and ask for a retrospective refund for the months in which you did not use the benefits. Explain that you did not know about it, that your circumstances have changed, or that you already hold similar cover elsewhere. Being polite is more useful than being prickly. Clear questions work better than anger.
Should the adviser become vague, ask to speak to a supervisor. Record dates, names and dollar amounts in writing. If you are in the UK and it concerns a packaged account, say that you never used the bundled benefits or that it was mis-sold because you did not need them. If you are in the US, ask what minimum balance would waive the fee and whether a basic account without a monthly charge is available. Many banks do not draw attention to those basic tiers unless customers ask.
If you find a ‘service’ or ‘plan’ charge, phone the bank and ask to downgrade, refund, or close it.
Small changes that stop the $50 drip
Have your salary or primary income paid into the account offering the most fee waivers. Create low-balance alerts at a higher level than seems necessary - not at $0, but at the balance where the maintenance charge would be triggered. Disable overdraft protection if each transfer costs money and it is not genuinely preventing larger fees. If you travel, add a travel notice and check whether your card charges foreign transaction fees; if so, use a fee-free card for overseas-billed purchases.
Remove duplicate cover. If your current account includes mobile phone insurance that you have never claimed on, while your mobile provider already covers theft and damage, the packaged account is effectively selling two umbrellas for one head. Choose e-statements if paper copies cost extra. Go through your direct debits in one session and cancel anything that no longer earns a genuine yes. Ten unobtrusive minutes can recover a whole year of “it’s only fifty”.
Arrange a regular date with your money
Choose one date each month - perhaps your rent date, or another date you will remember - and check your accounts on your phone. Take no more than five minutes. You are not building detailed spreadsheets or banning yourself from spending. You are looking for repetition: entries that recur, merchants that send no emails, and fees that avoid your notice. At the very least, you will train your mind to recognise the fox among the trees.
This is not about getting everything right. It is about seeing things earlier. The sooner you identify a fee, the greater the chance the bank will refund it, and the less time your money is spent funding benefits you never opened. It is a small routine with a substantial knock-on effect.
The myth that it is too small to challenge
Fifty dollars can seem too minor to justify the effort, which is precisely why it works. The bank counts on that calculation. Multiply one supposedly minor inconvenience by several million customers and it becomes clear why banking halls have polished floors. Reversing the fee does more than preserve your own cash: it casts your vote, through your balance, for products that do not penalise forgetfulness.
Your future self will appreciate a less stressful month. One fewer leak creates less pressure elsewhere. It could mean the difference between buying a train ticket without worry and checking your card at the barrier with your throat tight. Money is seldom only about figures. It is also about the burden you carry when you do not feel in control.
When the bank refuses
If the bank will not refund you, ask again with specifics: the dates, the fact that you did not use the benefits, and any overlap with insurance you already hold. If it is a UK packaged account and you believe it was mis-sold, make a formal complaint and, if necessary, take it to the Financial Ombudsman Service. For a US maintenance fee, ask whether a modest adjustment would meet the waiver requirements, such as a monthly transfer or linked savings account. A small change can sometimes reset the default in your favour.
If the product cannot be improved, switch accounts. Move to a straightforward, low-fee option and leave the premium extras behind. Switching banks can feel like moving home, but current account switching services can now complete the process in minutes. The most difficult part is deciding that your money deserves calm.
The partner test: two pairs of eyes
Where finances are shared, carry out the review together. One person may be better at noticing patterns, while the other may be more comfortable phoning up and standing firm. Sit at the kitchen counter, make tea or whatever helps you stay put, and read the previous quarter’s transactions aloud. It is less miserable than it sounds. Finding something and correcting it brings an odd relief, like freeing a drawer that has been stuck for months.
This is also how you uncover duplicated protection - two versions of the same plan across two accounts. Banks benefit when couples do not compare notes. You need not become the spreadsheet couple carrying a ring binder on holiday. Just spend thirty minutes once, and make a shared promise to keep the fox outside.
A small story with a tidier ending
Back to that dull Tuesday: I called, received an explanation, cancelled the plan and requested the previous four months back. The refund arrived two days later, announced by the solid ping of my app. It was not life-changing money or a lottery win. It was better: it felt as though I had repaired something. The low-level hum of worry eased.
The biggest surprise was not the refund itself, but the number of people who contacted me afterwards with the same revelation: a $9 paper fee here, a £15 package there, a $12 overdraft shuffle occurring three times a month. Once it is said aloud, other people start checking. That is how leaks end: one person sees the damp patch and points it out.
Check now and breathe later
If your bank statement feels like something you read in your sleep, bring it into focus. Review one month line by line and mark anything that is not food, bills, rent or joy. Name every recurring payment. Remove what you do not use, and retain what justifies its cost. The saving will feel greater than its value. It will feel like airing a room after a long winter.
Check this today, not next week. Your future self has a use for that $50: a train ticket to visit a friend, the dentist appointment you have delayed, or a small buffer between you and the surprise that always arrives on a rainy day. The fee is not clever; it is merely quiet. Once you have heard it, you cannot un-hear it - and that is the victory you carry into the next month.
Comments
No comments yet. Be the first to comment!
Leave a Comment