
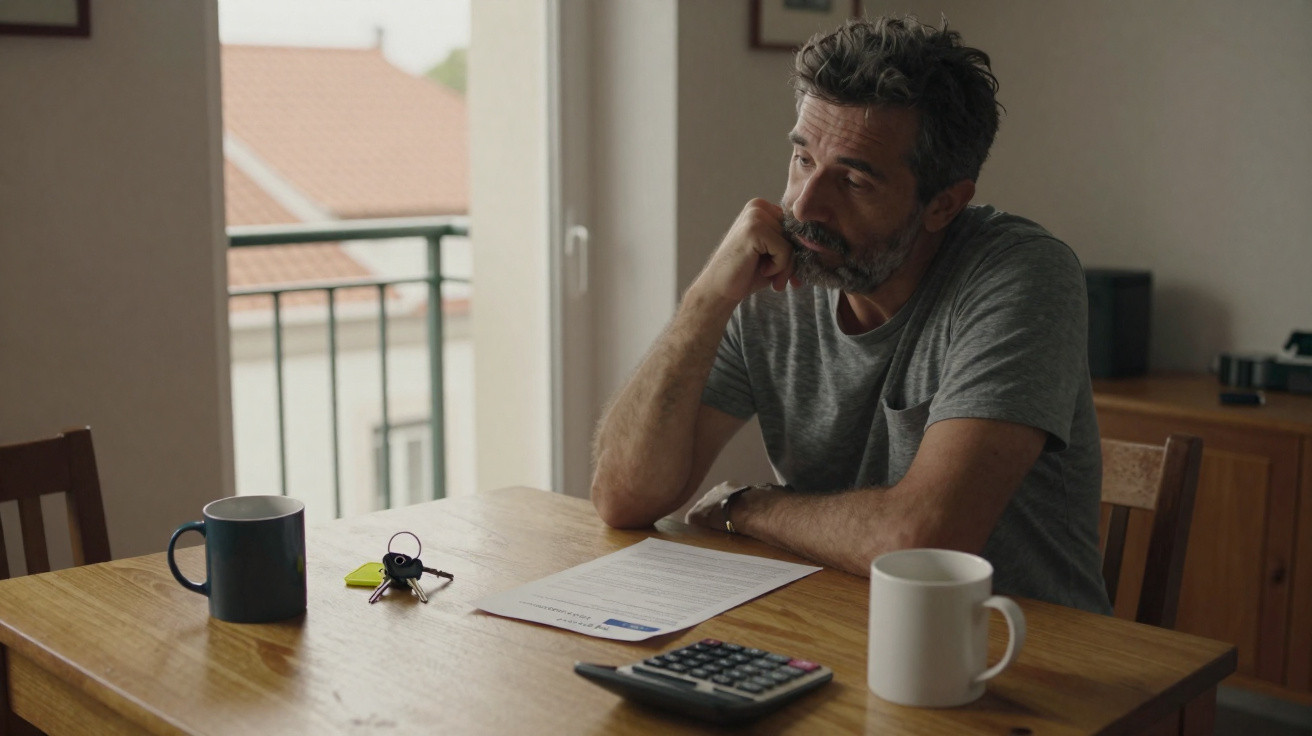
On a bleak Tuesday towards the end of January, Tom opened a brown envelope that he had almost thrown away as junk post. Inside was a council letter matter-of-factly explaining that he owed hundreds in property tax on a flat in a suburb he hardly ever went to. It was a flat where he did not live. A flat he had bought “on paper” to support a friend who was struggling.
He looked from the demand to the WhatsApp conversation in which his friend had once said, “Mate, I swear I’ll handle absolutely everything. You’re just helping with the mortgage on paper.”
The messages were packed with emojis, housewarming plans and jokes about “our” investment.
There were no emojis on the tax demand.
That single envelope turned what had seemed like a small favour into a potentially costly error.
When friendship leads to an unexpected property tax bill
Tom’s situation began much like countless others: he earned a decent wage, had no deposit for a place of his own and firmly believed buying a home in his city was beyond reach. His friend Dan, recently separated and urgently trying to buy a flat where his children could stay, came up with a solution. “You go on the mortgage with me. My credit is shot. You’re clean. Once I’ve sorted everything and remortgaged, we’ll take you off.”
In theory, it appeared to be a sensible favour between mates. Neither of them gave much thought to councils, land registries or who the tax authorities would regard as the actual owner.
Instead, they focused on loyalty and the idea of “helping out, just this once.”
At least in their minds, the arrangement was straightforward. Dan paid the deposit from his savings, topped up by a small loan from his parents. The monthly mortgage instalments left his bank account. It was his flat, with his belongings and his keys.
The title deeds, however, were in both their names. That was where the problems started.
Months afterwards, the local authority refreshed its records and Tom’s name appeared as a co-owner. To the tax office, this was not a case of “helping a mate”. It appeared that he owned a second property. And a second property brings a bill.
No one had alerted him to it. The solicitor had briefly referred to “liability”, buried in the sort of rapid legal explanation that most people simply nod along with.
The reasoning is starkly simple. The system is not interested in who sleeps on the sofa or whose name is displayed on the buzzer. It looks at the names on legal paperwork. In many areas, being recorded as an owner or joint owner can be enough to trigger property tax, second-home surcharges and, at times, higher council tax bands.
As far as the council was concerned, Tom was no longer a lifelong tenant. He was the fortunate co-owner of an attractive two-bedroom flat. He simply… did not live there.
The computer then produced a figure: one capable of quietly tearing apart a budget already built around rent, energy costs and a supermarket loyalty card.
The emotional impact comes afterwards, when a “helping hand” starts to feel more like a hand forcing your head below the water.
Helping with a mortgage without losing your shirt, sleep or friendship
If you have ever considered “just going on the mortgage” for somebody you care about, the first step is deeply unglamorous. Sit down and set out every possible way the arrangement could fail. Put it in writing, in blunt and tedious detail.
Who covers the cost if the boiler breaks down? Who pays if the tax rises sharply? What happens if they lose their job, or if you lose yours?
Next, consult an independent adviser who has no connection to your friend, no investment in your shared history and only one concern: risk. It is their role to raise the uncomfortable points that you may be too polite to mention.
It can seem distrustful, but it is actually a profound form of respect.
Most of us combine friendship and money as we mix drinks: freely, hopefully and without checking the labels. We say “we’ll sort it out later”, trusting that our future selves will somehow be wealthier, calmer and better organised.
That is how people find themselves in joint ownership without a written agreement, an exit strategy, a defined division of costs or any real understanding of their tax position. Then the tax bill arrives and everyone suddenly recalls the small print they skimmed in the PDF from the solicitor.
In truth, almost nobody reads every term of a 30-page contract before signing it.
The answer is to create pauses: sleep on it for one night before signing, speak with someone who has genuinely experienced a difficult property split, and make an anonymous call to the tax office to ask the “stupid” questions.
Tom says he still doesn’t regret helping his friend stay near his kids. “What I regret,” he admits, “is signing something I didn’t fully understand. I didn’t know owning half a place I don’t live in could hit me like this. I thought I was being kind. I didn’t realise I was becoming a landlord in the eyes of the taxman.”
- Set out every worst-case scenario
This is not because you assume disaster will happen, but because both of you should understand what follows if life takes an unexpected turn. - Put it all into a separate written agreement
Specify who pays for what, who arranges repairs, what happens if either person wants to sell and how tax costs are divided. - Speak to the tax office or a professional early
A 20-minute conversation may uncover taxes, surcharges or benefits that you did not realise applied. - Protect your own financial stability
Maintain an emergency fund separate from the property, and do not depend on this “investment” for your future. - Agree how to safeguard the friendship
Decide in advance that, if money creates strain, the priority is finding an exit rather than holding on to the original arrangement.
A flat, a friendship and a cost you cannot invoice
Situations such as Tom’s do not slot tidily into categories of “right” and “wrong”. On one hand, there is a friend who might not have been able to house his children without assistance. On the other, there is a tenant suddenly facing an unbudgeted extra charge on a home he does not regard as his own.
The tax office does not assess loyalty. It scans names, ticks boxes and issues sums payable by a specified date. But when these circumstances are discussed over dinner or in group chats, the real argument is much more complicated: what we owe those we love, and what we owe ourselves.
Some people will argue that Tom was naïve. Others will believe Dan exploited him. Many will privately acknowledge that they would have done precisely the same thing in that moment, for that friend and under that pressure.
We have all known that moment when saying “no” feels colder than any council letter.
Perhaps the real divide is not between owners and tenants, nor between generous friends and careful ones. It lies between what the system acknowledges - names on deeds and entries on forms - and what people see as human: promises, favours and shared history.
If somebody asks you to “just help out with the mortgage” next time, you may still agree. Or you may say, “I need to understand what this means for me, on paper, with the taxman, long-term.”
That sentence may feel uncomfortable at the time.
It could also protect both your bank balance and your friendship.
| Key point | Detail | Value for the reader |
|---|---|---|
| Legal owner = tax target | If your name appears on the deeds or mortgage, the system can regard you as an owner even when you do not live at the property. | Helps you identify concealed tax risks before agreeing to a “favour”. |
| Put agreements in writing | Clear contracts and side agreements establish who pays which costs and what happens when circumstances change. | Limits disputes, safeguards the friendship and supports you if a disagreement arises. |
| Seek detached, unbiased advice | Independent financial or legal guidance highlights worst-case outcomes that you may be tempted to overlook emotionally. | Provides a reality check, so your heart does not sign an agreement your wallet cannot afford. |
FAQ:
- Question 1 Can I genuinely be taxed on a property where I do not live if I am only “helping a friend”?
- Question 2 What questions should I put to a solicitor before agreeing to join somebody else’s mortgage?
- Question 3 Is there a way to avoid second-home or additional property taxes in this type of arrangement?
- Question 4 What happens if my friend stops making mortgage payments while my name remains on the loan?
- Question 5 How can I leave a shared property arrangement without ruining the friendship?
Comments
No comments yet. Be the first to comment!
Leave a Comment