
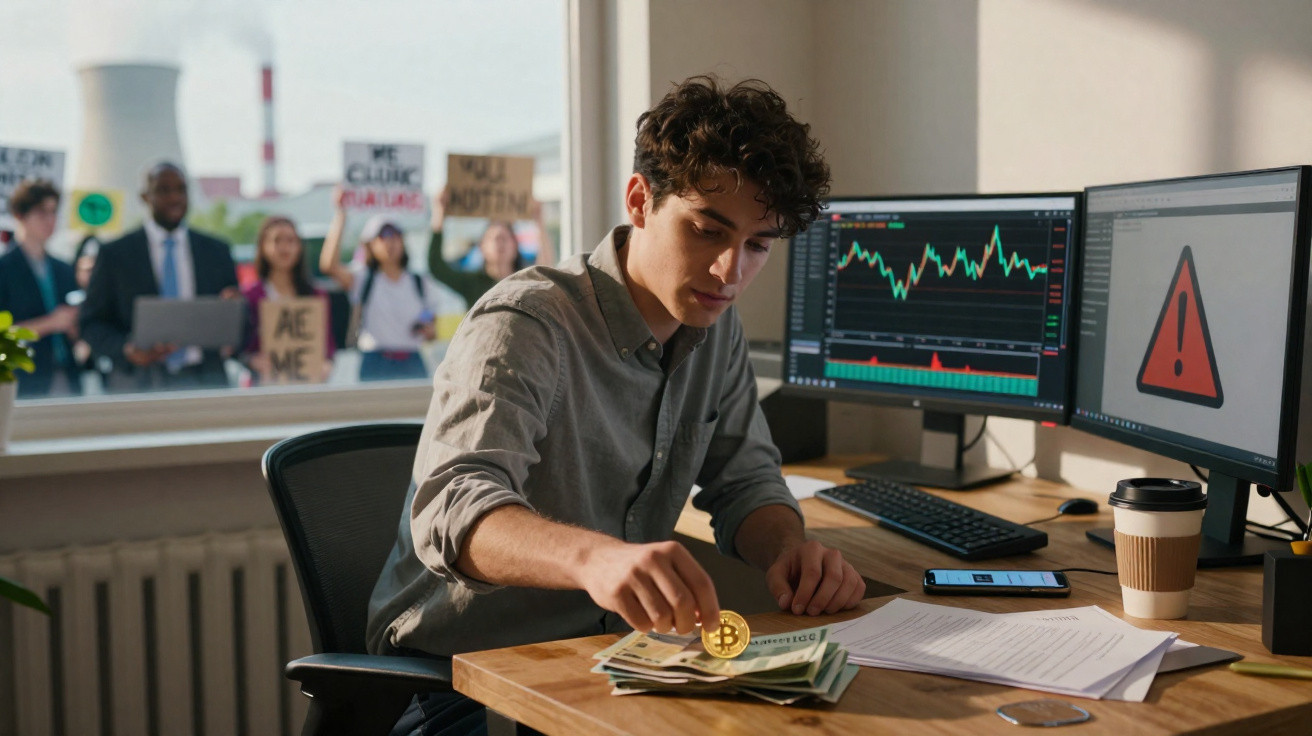
Bitcoin’s promise of seamless digital money is now running into hostile regulators, escalating electricity costs and an increasing wave of fraud.
The formerly romantic tale of a renegade currency has become a bitter struggle involving true believers, sceptics and people quietly taking profits as the clamour intensifies.
Regulators finally shift from curiosity to a crackdown
For years, financial watchdogs viewed bitcoin as an unusual experiment at the outer edge of finance. That approach has changed dramatically. Across Washington, Brussels, Beijing and London, authorities are imposing tighter controls on exchanges, wallets and stablecoins connected to cryptocurrency markets.
Anti-money laundering checks now extend far into services that once celebrated anonymity. Fresh rules in the US, EU and UK require identity checks, transaction disclosures and more robust reserves from businesses dealing in digital assets.
Governments are no longer asking whether crypto should be regulated, only how tough the regime should be and who gets caught first.
Some regulators now openly discuss “de-risking” banks from exposure to crypto. In several jurisdictions, banks already limit payments to certain exchanges or tell customers that any losses may be impossible to recover.
Key pressure points for bitcoin businesses
- Licensing obligations for exchanges and custodians
- Tighter tax reporting for capital gains and losses
- Restrictions on leverage and derivatives tied to bitcoin prices
- KYC/AML checks for even comparatively small transactions
- Possible prohibitions on privacy coins and mixing services
Every additional rule creates more expense and friction, weakening the unrestrained appeal that attracted many users initially.
Energy costs spiral as mining collides with climate politics
Bitcoin mining, which protects the network and produces new coins, uses enormous volumes of electricity. Miners’ profits depend on a straightforward calculation: when bitcoin’s price falls or power costs increase, margins disappear quickly.
Rising global energy prices have forced many smaller mining businesses to close. Bigger industrial operators have repeatedly moved location in pursuit of inexpensive electricity, from Texan wind farms and Kazakh coal plants to hydroelectric and nuclear projects searching for customers.
What began as a geeky hobby using spare computer power has turned into an industrial arms race fought with shipping containers full of specialised machines.
Why climate activists are furious
Environmental groups say bitcoin’s structure promotes wasteful electricity consumption, as miners compete through raw computing capacity. Academic calculations differ, yet many equate bitcoin’s yearly electricity use with that of a medium-sized country.
Climate campaigners present the argument starkly: during accelerating global warming, they regard bitcoin mining as an unnecessary luxury that displaces cleaner applications for electricity.
| Issue | Climate activists’ concern | Bitcoin advocates’ response |
|---|---|---|
| Energy consumption | Large and growing load on power grids | Pushes investment into renewable generation |
| Carbon emissions | Reliance on coal and gas in some regions | Trend toward hydro, wind and stranded energy |
| Local communities | Higher prices and grid stress for residents | Tax revenue and jobs in depressed areas |
Politicians are consequently confronted with difficult choices. An outright mining ban satisfies climate activists but shifts operations abroad, where supervision is less stringent. Endorsing mining, meanwhile, risks angering voters facing higher household energy bills.
Scams surge as retail money flows in and out
Each rise in cryptocurrency prices has drawn a new surge of fraud. From counterfeit trading sites to meme coins with no obvious purpose, opportunists create schemes intended to take newcomers’ savings.
Regulators say complaints linked to crypto are now among the fastest-growing forms of financial crime. Law enforcement has a challenging task: although numerous transactions are traceable on public blockchains, money frequently moves through mixing services, offshore exchanges or privacy layers before it reaches criminals.
Behind the glossy apps and slang-filled chat rooms sit very old-fashioned tricks: promises of guaranteed returns and pressure to “get in before it’s too late”.
Common patterns in crypto frauds
- “Investment managers” promising consistent double-digit monthly returns
- Social media influencers advertising untested tokens they secretly own
- Romance scams that gradually direct victims towards suspect “trading platforms”
- Fake customer support staff who obtain access to wallets and seed phrases
When markets decline, these arrangements unravel quickly. People who joined late, often smaller investors, are left holding illiquid tokens with no means of recovery. This strengthens the argument that the whole system resembles a pyramid, in which early participants cash out using money from later arrivals.
Early adopters cash out while new believers hold firm
Many early bitcoin adopters have quietly been cutting their holdings. On-chain data indicates that coins bought years ago are being transferred to exchanges, a conventional signal that selling may follow.
Some early holders say they are merely diversifying into property, shares or even conventional bonds. Others acknowledge that they no longer expect bitcoin to expand at what once appeared to be an inevitable pace.
Meanwhile, another group remains committed. Long-standing “hodlers” regard every sell-off as a test of conviction. They repeat slogans about holding for ten years, disregarding short-term volatility and believing fiat currencies will deteriorate faster than bitcoin’s price can drop.
The cultural divide runs deep: for one side bitcoin is a rational bet; for the other it has taken on the tone of a quasi-religion.
Wall Street enters quietly while both sides shout
Major financial institutions are playing a double game. In public, some bank leaders call bitcoin a bubble or a “fraud magnet”. Behind the scenes, their trading desks build products designed to collect fees from clients seeking exposure.
Bitcoin-backed exchange-traded funds have ushered in a fresh stream of institutional money. Pension funds, hedge funds and family offices now have indirect holdings, even where formal policy statements remain sceptical.
This produces an unusual alliance: committed crypto supporters and Wall Street quants both rely on prices rising, despite disagreeing about bitcoin’s purpose and ethics.
Is bitcoin money, digital gold, or a clever pyramid?
Critics label bitcoin a pyramid scheme because its value seems to rely mostly on more buyers entering at higher prices. It offers no claim on cash flows or corporate profits, only expectations of future demand.
Supporters argue that the same reasoning applies to many established assets, including gold and fine art, whose worth is based on scarcity and shared belief rather than income streams.
Whether bitcoin is a scam or a revolution may depend less on code and more on how long that shared belief can last.
In everyday use, bitcoin functions awkwardly as money. Prices fluctuate sharply, transaction fees may jump and settlement times differ. Most real-world payments still go through cards and bank transfers, including among crypto supporters who speak of financial freedom.
Many holders instead view bitcoin as a long-term store of value, closer to “digital gold” than a working currency. That storyline has become firmer as central banks increased interest rates and technology shares faltered; investors seek assets they hope cannot be inflated away.
What small investors need to know before joining the fight
Anyone thinking about bitcoin confronts overlapping dangers: regulatory crackdowns that may restrict access, energy disputes that harm public sentiment, and scams aimed at the most inexperienced holders.
Short-term price movements can be severe. Double-digit changes within one day are not unusual. Leverage magnifies the damage, turning a modest fall into a margin call that empties an account.
Practical measures can lower the risk of disaster:
- Invest only money you can afford to lose completely
- Choose reputable exchanges with clear licensing and transparency
- Understand basic wallet security before transferring substantial sums
- Treat anyone offering guaranteed returns or insider tips with suspicion
- Review tax rules in your country; trades can create reporting obligations
Knowing essential terminology matters too. “Hodl” means retaining holdings through volatility. “On-chain” data means transactions recorded directly on the blockchain. “KYC” refers to know-your-customer checks, which connect real identities with accounts.
Consider three possible futures. In one, strict regulation and climate pressure force bitcoin to the margins, where it is used mostly by a determined minority. In another, financial giants turn it into another speculative asset, stripping away its initial anti-establishment character. In a third, a crisis of trust in traditional currencies triggers another wave of adoption despite every warning.
No model can predict reliably which outcome will prevail. At present, the only certainty is conflict: regulators versus libertarians, climate activists versus miners, Wall Street versus crypto purists, and small investors caught between them, asking whether they are early to a new kind of money or late to a vast, slow-moving pyramid.
Comments
No comments yet. Be the first to comment!
Leave a Comment