
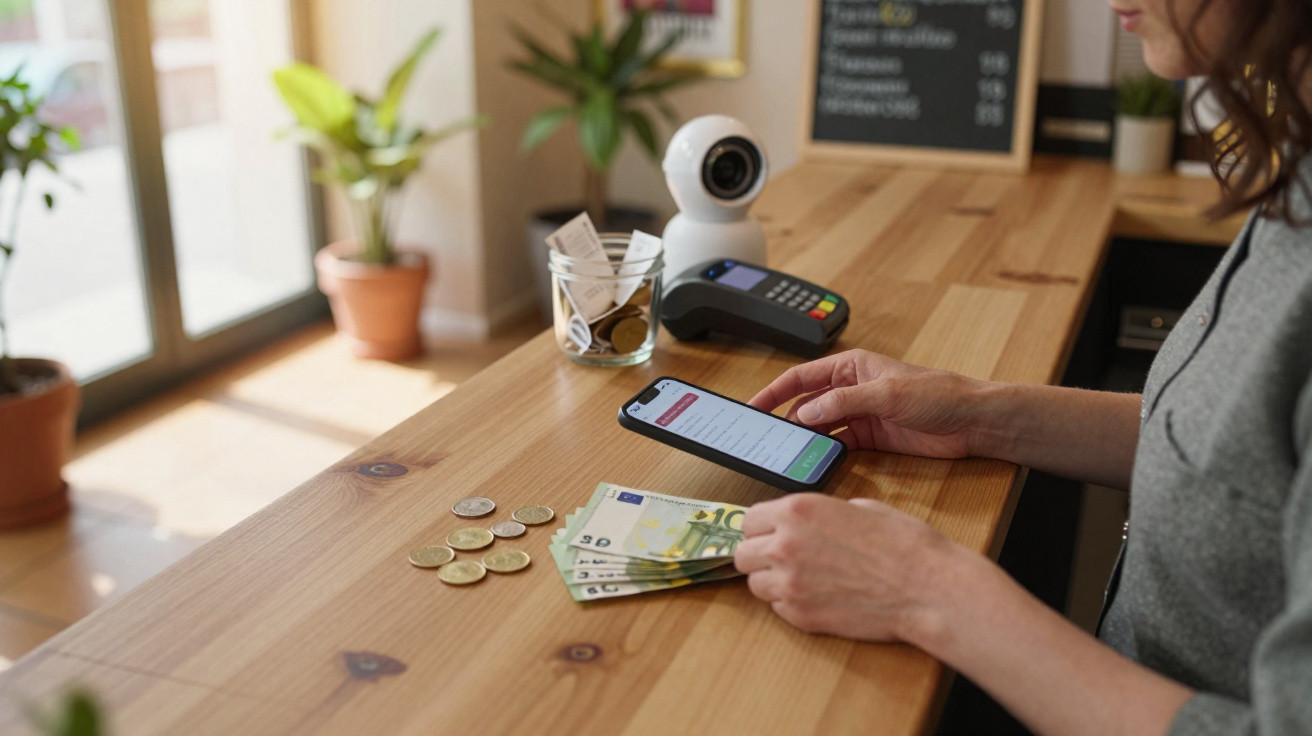
On a wet Thursday night in Milan, the line at a small corner supermarket is moving steadily-until an elderly man brings it to a halt. He produces a crumpled €50 note with unsteady hands, prompting a sigh from the cashier. Although the card machine is working, the “cash till is closed”. Shoppers check the time. One person mutters that this is 2026, not 1996. Red-faced, the man eventually abandons his groceries and walks out.
Outside, he lights a cigarette he can likely ill afford and complains that “they” no longer want him handling his own money.
The neon lights buzz. Inside, contactless payments continue to beep.
Across Europe, versions of this same moment are unfolding in countless ways.
When paying becomes a quiet act of resistance
Walk through almost any European city today and money barely resembles money any more. Coffee shops wear “card only” signs as symbols of modernity. Small bars hand over a QR code rather than a bill. Your phone constantly asks you to tap, swipe, authenticate and approve. Banknotes and coins, once a common language, are increasingly treated like a foreign dialect used only by the fearful and obstinate.
Cash is now political.
A bakery owner in Hamburg tells me that, before the pandemic, just a third of her customers paid by card. Today, almost nine in ten do. Beneath the counter, she keeps a tin of coins “for the old regulars”, she says, sounding almost apologetic-as though she were concealing contraband.
In Sweden, where certain buses no longer accept cash whatsoever, a retired nurse recalls feeling “locked out” when the ticket app failed and her smartphone ran out of charge. She had 200 kronor in her purse. The driver simply shook his head.
This is the subdued edge of a far more intense argument. In public, the case is framed around convenience, hygiene and speed. In private, people ask who is watching their lives, who can block their accounts, and who gets to decide whether the €20 note beneath their mattress looks suspicious.
When money becomes entirely digital, it is much easier to monitor, limit and weaponise. The boundary between a “payment system” and a “control system” begins to fade. People sense this instinctively, long before they find the language to explain it.
The new fault line: control, climate of fear, and family rifts
Spend an evening at a family meal in Madrid or Lyon and the argument will probably emerge. At one end of the table, a 25-year-old happily explains that he has not used cash for months: everything is on his phone and “only boomers worry about this stuff”. At the other, a 63-year-old uncle insists that money cannot truly be yours if a bank can cut you off with a single click. Voices get louder. Wine glasses tremble. Somebody redirects the conversation towards football.
The disagreement does not disappear. It merely drops below the surface, ready to return with the next bill, bank letter or scandal.
Across Europe, newspaper stories deepen that anxiety. A Dutch freelancer wakes to discover that her account has been “temporarily blocked” after an algorithm detected “unusual activity”. For 48 hours, she cannot pay her rent, purchase food or reach the savings she spent a decade accumulating.
In France, an NGO employee is shocked to discover that her bank has classified her entirely lawful donations as “high risk” under stricter anti-terror rules. Nobody has accused her of wrongdoing. Even so, she feels watched. A British student is informed that his online poker activity means his account will be “reviewed”. The wording is courteous. The fear is not.
Regulators say these measures concern crime, tax avoidance, corruption and terrorism. Citizens agree, then begin asking where the boundary lies. Today, the focus is on substantial cash deposits. Tomorrow, it might extend to political donations, subscriptions, “suspicious” journeys or merely residing in the wrong area.
Let’s be honest: no one truly reads the 30-page terms and conditions explaining how their data is shared and assessed. We tap “accept” and trust that the system will remain benevolent. The discomfort comes from one straightforward question: what happens if it does not?
Who really owns your money when it lives inside a screen?
One stark and troubling question keeps surfacing in European conversations: if money exists only as figures in a database, does it still belong to you in any meaningful sense? Legally, the answer is yes. In reality, access relies on a chain of parties beyond your control-your bank, its software supplier, regulators, card networks and, perhaps soon, a central bank digital currency platform.
You do not hold value. You hold permission. And permission can be withdrawn.
During the energy crisis, several EU governments considered targeted assistance delivered solely through digital vouchers, which could be used only at authorised shops and for authorised goods. Some climate proposals extend further, envisioning personal carbon budgets monitored in real time, with spending encouraged-or even prevented-once you have exceeded your “fair share” of flights, fuel or meat. On paper, these are instruments of fairness. In practice, they create a new means of directing financial behaviour.
A low-level dread is growing: if every euro is labelled, assessed and directed, where does individual autonomy stop and algorithmic babysitting start?
The data trail is the real treasure trove. Every tap discloses something about your routines: when you buy alcohol, which chemist you visit and where you spend your evenings. For many people, this exchange feels worthwhile. To others, it resembles walking around naked while being told that clothed people are criminals.
Once you see that your “money life” is also your “data life”, you can’t unsee it. The issue changes from “Is digital bad?” to “Who gets to pull the plug, and on whom?” That is when anger starts to build-not towards technology itself, but towards the imbalance of power behind it.
Small acts, quiet choices: how people push back without slogans
Not everyone concerned about a cashless future takes to the streets with banners. Most make modest, gradual adjustments instead. A teacher in Bologna now divides her wages: 80% enters her main bank account, while 20% is withdrawn as cash on payday and stored in envelopes for groceries, presents and emergencies. It makes her feel “less exposed”, she says.
A Danish couple use digital services for almost everything, but pay their babysitter and local gardener exclusively in cash as a “tiny vote” against complete traceability. Such gestures will not halt the banks, but they do preserve another way of doing things.
Others are quietly spreading their risk. A Spanish engineer purchases a small amount of physical gold, not as investment advice but as a psychological anchor: something that exists beyond the app. A Greek shopkeeper maintains a second account with a small regional bank after watching friends endure capital controls a decade ago. None of this is about concealing wealth. It is about ensuring that every door is not governed by the same key.
We have all experienced the moment when a card is declined or an app fails, and we suddenly understand how vulnerable ordinary life can be. Ten minutes at the till can reshape your sense of “ownership” more effectively than any opinion column.
People unwilling to abandon cash are frequently dismissed as paranoid or behind the times. Beneath that reaction, many are expressing a basic need: resilience. They want backup systems rather than one digital bottleneck. They want to be regarded as adults capable of holding both a smartphone and a banknote without being ridiculed.
“Cash is not nostalgia,” a Dutch lawyer tells me. “It’s a seatbelt. Most of the time you don’t need it. The one time you do, you really do.”
Maintain a modest “offline buffer”
Keeping several days’ worth of spending money in cash, securely hidden at home, can turn a banking fault from a disaster into a minor inconvenience.Distribute your financial footprint
Rely on more than one bank or payment provider, so that one blocked account cannot stop your entire life.Discuss boundaries with your family
Set out your red lines, whether they involve a complete cash ban, compulsory digital IDs or programmable money. It is easier to disagree than to act as though nothing is changing.
A continent between trust and suspicion
Europe has reached an unusual crossroads. Policymakers speak of “financial innovation”, “digital sovereignty” and “fighting crime”. Citizens describe something different: the fear that their everyday existence could be turned off from above while the genuinely powerful continue through loopholes untouched. This difference in perception creates a quiet but corrosive mistrust.
Some people will welcome a completely cashless future with relief. Others will hold on to their final banknotes as if they were a prayer. Most will occupy the uneasy space between those extremes, adapting as they go.
Within that unsettled middle ground, the true political struggle is not simply cash versus card, or app versus banknote. It concerns who sets the rules governing money-and who can alter them overnight. If “your” money can be restricted, directed or frozen according to changing standards and opaque algorithms, ownership ceases to be a legal technicality and becomes a profoundly personal fear.
Families will continue to argue over dinner. Friends will continue rolling their eyes. But beneath these minor disputes is a larger unresolved issue that may shape the coming decade of European life: is money a tool we use, or a leash we quietly learn to accept?
| Key point | Detail | Value for the reader |
|---|---|---|
| The cashless shift is gathering pace | From “card only” cafés to app-based public transport, daily life is increasingly being rebuilt around digital payments | Helps readers see the structural shift they are experiencing, rather than viewing it as a series of isolated irritations |
| Control and fear influence the debate | Monitoring, account blocks and programmable money create mistrust that goes far beyond the official story of “convenience” | Presents personal unease as a rational response rather than irrational paranoia |
| Practical resilience remains possible | Combining payment methods, maintaining small cash reserves and having open family conversations can provide greater autonomy | Offers readers practical responses without panic or denial |
FAQ:
Question 1: Is Europe really heading for a fully cashless future, or is this just media panic?
Several countries have already travelled far along that path, particularly in the Nordic region, while others are moving more slowly. The broad direction is evident: fewer cash machines, more “card only” businesses and policy discussions about restricting large cash transactions. Completely abolishing cash is not official EU policy today, but its de facto marginalisation is already occurring in many everyday settings.Question 2: Why do governments and banks push so hard for digital payments?
They point to reduced costs, simpler tax collection and improved ways to combat crime and terrorism. Digital payments cost less to process and are easier to trace. They also produce valuable data and tie users to particular platforms, which appeals to both financial institutions and technology companies.Question 3: Isn’t digital money safer than carrying cash around?
It may offer greater protection against theft or loss, and consumer protection rules can often help when cards are stolen or misused. But the trade-off changes: it is physical risk versus systemic risk. Cash can be stolen from you in the street; entirely digital money leaves you wholly dependent on infrastructure, institutions and rules outside your control.Question 4: What about central bank digital currencies (CBDCs) in Europe?
The European Central Bank is actively examining a “digital euro”. Officially, it is presented as an addition to cash, rather than a substitute, and is said to include robust privacy protections. Critics fear that once the system exists, future governments may be tempted to introduce conditions, limits or surveillance functions, especially during crises.Question 5: What can ordinary people do if they’re worried about control over their money?
They can spread where and how they keep funds, retain a modest cash reserve, follow policy debates on cash limits and digital IDs, and speak openly with friends and relatives rather than worrying alone. Personal choices will not reverse the global direction of travel, but they can retain some individual breathing room within it.
Comments
No comments yet. Be the first to comment!
Leave a Comment