
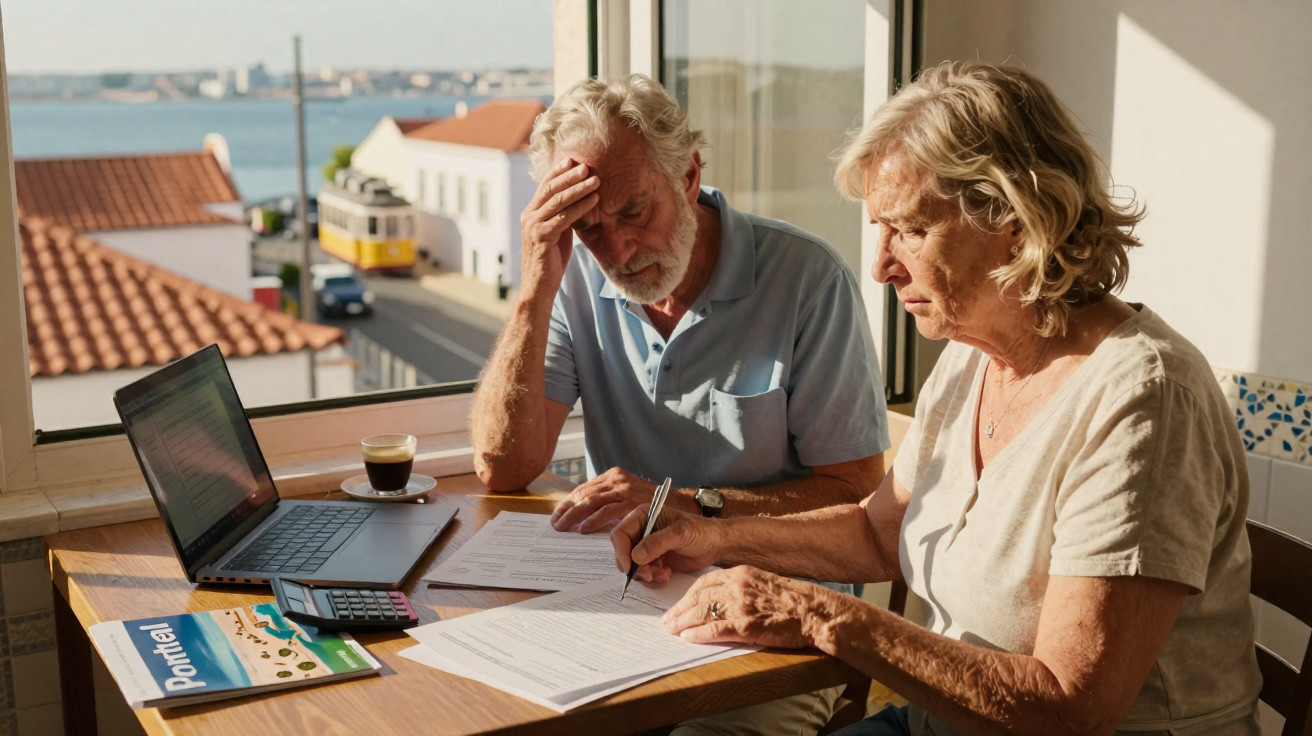
French retirees were especially drawn to Portugal, encouraged by low taxation and an established expat community. A sudden rule change is now making many recalculate their finances and reconsider what comes next.
From golden promise to tax reality
For over a decade, Portugal promoted itself as something of a tax haven for overseas retirees. Its main draw was the “non‑habitual resident” status, widely known as the RNH regime.
Through this arrangement, many overseas private pensions were initially free of Portuguese income tax before becoming subject to a 10% flat rate. For French or British pensioners with modest to middle-range incomes, this could deliver annual savings of several thousand euros.
The RNH regime turned Portugal into a benchmark destination for European retirees looking to stretch their pensions under the sun.
That period is now over. From January 2024, newly arriving foreign retirees in Portugal have been unable to use RNH. They are instead subject to the normal Portuguese income-tax bands, which reach 48% and can rise to 53% where solidarity surcharges apply.
A sharp blow for new arrivals
The consequences are immediate for people who relocated, or intended to relocate, in reliance on the former rules. Many had prepared detailed long-term financial forecasts with advisers, calculating their future take-home income.
For a pension of around €21,000 per year, tax in Portugal can now exceed what would be due in France.
This matters because many middle-class European retirees sit within that income bracket. They are not affluent enough to absorb major unexpected costs, but are too “rich” to receive substantial social support. On forums and at expat gatherings, the quiet sentiment is that the conditions changed in the middle of the game.
A sense of unfairness and broken promises
Many couples had already sold their homes, purchased property near Faro, Lisbon or along the Algarve coast, and transferred their lives abroad. Beach walks and visits from grandchildren formed part of a carefully planned future.
Some now describe uncertainty instead. Going back home can be difficult and costly. Portuguese property values have risen sharply over the past decade, while buying again in France or the UK would frequently cost considerably more than the price achieved when they sold.
Criticism within Portugal of overseas property demand has been increasing for years, from Lisbon to Porto. Portuguese families, particularly younger households, have faced rapidly escalating rents and house prices. This pressure lies behind the political decision: the government says reducing generous tax advantages for foreign retirees may help cool the housing market.
Officials frame the reform as a response to housing pressure in major cities, not an attack on retirees themselves.
Daily life gets more expensive than expected
Income tax is only part of the calculation. Relocating to Portugal can also bring a range of additional expenses that newcomers may not fully anticipate.
- Buying a property involves transfer taxes and stamp duty.
- Registering a car imported from abroad can be expensive and administratively burdensome.
- Annual vehicle circulation tax creates another regular cost.
- Local property taxes become payable once a home is owned.
Many products and services remain less expensive than in France, the UK or Germany. Restaurant meals in smaller towns, everyday food shopping and certain healthcare services can often appear cheaper. However, that difference quickly diminishes once increased income tax and housing expenditure are included.
Some retirees react by reducing spending: eating out less often, taking more modest holidays or postponing renovation projects. Others look beyond sought-after coastal areas towards smaller inland towns, where costs are lower but hospitals and other services may be more distant.
Bureaucracy, language and the hidden cost of admin
There is also a cost in time and effort, beyond the financial outlay. Dealing with another country’s tax and social systems can be exhausting, particularly without fluent Portuguese. Local authority registration, health-insurance arrangements, driving licences, vehicle documentation and yearly tax returns all require persistence.
Many retirees adjust, developing local support networks or using bilingual accountants. But for newcomers anticipating a straightforward “easy life in the sun”, the administrative side can come as a surprise.
Looking elsewhere: Spain, Morocco, Malta and beyond
As Portugal becomes less favourable for retirees, interest is shifting towards destinations that combine sunshine with more clearly defined tax arrangements.
| Destination | Main attractions for retirees | Key points of caution |
|---|---|---|
| Spain | Cultural proximity, strong healthcare, large expat communities | Tax rules complex, wealth tax in some regions |
| Morocco | Low cost of living, French widely spoken, short flight from Europe | Different legal system, political and currency risks |
| Malta | English-speaking, specific expat tax programmes | Small housing market, prices already high in some areas |
| Cyprus | Attractive climate, favourable taxation on some foreign pensions | Geopolitical tensions, limited public transport |
Spain is particularly prominent thanks to familiar cuisine, language similarities for French speakers, solid infrastructure, and well-established British and French retiree communities. However, its tax regime can be demanding, and tax treaties with countries of origin need close examination.
Morocco attracts interest because everyday living costs are much lower. Outside the principal tourist areas, renting or purchasing a property can be highly affordable, while domestic help and eating out can often suit limited budgets. In return, retirees must navigate a different legal and social setting, less generous state healthcare and currency exposure.
For would-be expats, stability of tax rules now matters almost as much as the headline tax rate.
Portugal’s new target: skilled workers, not pensioners
Lisbon is changing direction. As the RNH regime is withdrawn for retirees, the government is developing fresh incentives aimed at highly qualified professionals in areas such as technology, engineering and research.
The signal is unmistakable: Portugal seeks overseas talent that supports innovation and productivity, rather than simply pension income. For retirees, it can feel as though a door is quietly being shut. Many recognise that tax incentives cannot continue indefinitely, but question both the speed and timing of the reform.
Planning scenarios: what a retiree now needs to check
Anyone still considering a move to the Algarve, Cascais or a peaceful Alentejo village must undertake detailed planning. Several practical checks can limit unwelcome surprises.
- Model tax liabilities in both the home country and the destination, using current rules and a “less favourable” scenario.
- Review the double-taxation treaty between the two countries: where is the pension taxed first, and how is relief granted?
- Account for exchange-rate exposure where a pension is paid in sterling but spending is in euros.
- Build health costs into the budget, including top-up cover, private appointments and possible medical evacuation.
A straightforward example shows what is at stake. Consider a retiree receiving a net pension of €2,000 each month. With a 10% flat rate, roughly €200 went on Portuguese income tax. On the standard scale, that charge could approximately double or increase further, depending on personal circumstances and deductions. Across ten years, the gap may amount to tens of thousands of euros.
Beyond tax: what really makes a retirement work
Tax efficiency draws attention, but it cannot by itself secure a settled retirement. Climate, healthcare, social connections and certainty over future rules all matter. A modest tax bill is of little benefit if finding good doctors or dependable transport becomes a continuing concern.
A number of advisers now recommend trying a country for longer periods before making a permanent commitment. Renting for an entire winter, for example, gives prospective residents a chance to experience the health system, pace of life and genuine budget required without being tied to a property purchase.
A successful retirement under the sun rests on a balance: lifestyle, financial security and stable long-term rules.
Potential expats are also considering mixed arrangements: staying abroad for just under six months to avoid tax residency, or dividing their time between two countries while formally retaining residence in their home country. These options can work, but must comply with tax-residence tests, which generally depend on the number of days spent in a country and where an individual’s “centre of interests” is located.
Ultimately, Portugal’s U-turn is a warning for anyone pursuing overseas tax deals. Regulations change, governments contend with housing and budgetary pressures, and what appears to be a lasting opportunity can narrow rapidly. Retirees who recognise that uncertainty and prepare for it are in a stronger position to continue enjoying the sun when the tax weather changes.
Comments
No comments yet. Be the first to comment!
Leave a Comment