
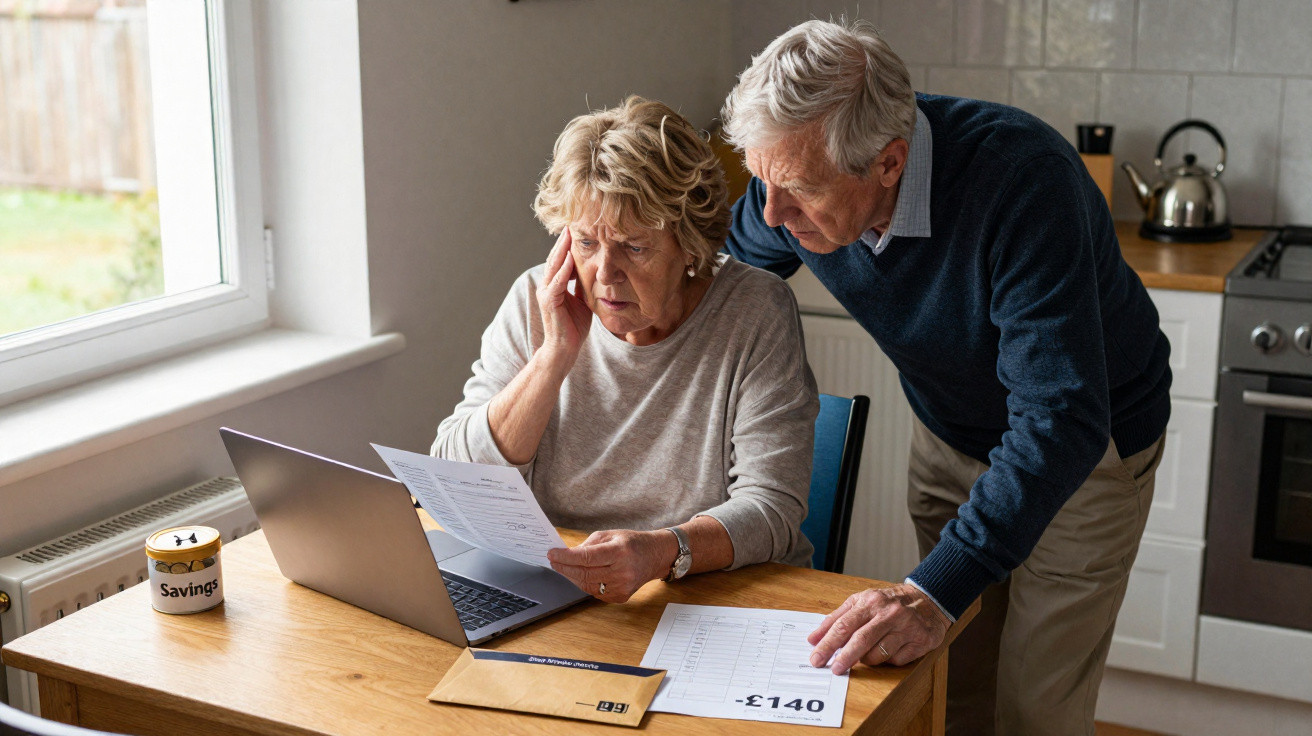
No bold red warning appears on the envelope’s front: only the discreet DWP logo and a printed address. Inside, several stark typed lines tell you that your state pension will fall by £140 a month from December 2025. There is no apology or personal explanation, only a date, a sum and the dreadful sense that income you depended on is silently being taken away.
On the bus later that day, you begin dividing your life into cuts. Friday fish and chips with friends. The little Christmas envelope for the grandchildren. Turning the heating up by one degree on freezing mornings. On television, £140 may seem modest, but on a fixed income it is not merely a figure. It means food, warmth and dignity.
You glance around the bus and ask yourself how many other passengers received that letter this week. How many felt the same shock, with the same unspoken question lingering between them.
What a £140 state pension cut means in everyday life
In official terms, the change can sound almost administrative: a “state pension reduction of £140 per month starting December 2025.” It takes up one bullet point in a ministerial briefing. On a retired person’s kitchen table, it carries far more weight.
Picture an annual loss of £1,680 when every pound is already accounted for. For a careful shopper, that is close to two months’ worth of groceries. In an older home with poor insulation, it could cover the full winter gas bill. Rather than arriving as one dramatic blow, the shortfall becomes a gradual, relentless pressure.
Those who based their retirement plans on the present state pension can suddenly see “just enough” become “not enough”. The figures are not loud, but they murmur in the night when the calculator comes out in an otherwise silent room.
Speak to pensioners sitting on a market bench and the impact soon becomes clearer. One man in his early 70s calls £140 “the difference between feeling poor and feeling desperate”. He is not exaggerating. His rent has already edged upwards, and his council tax rose by more than he anticipated. Now this.
A woman who spent 40 years working for the same supermarket says she has begun writing prices on packets in her cupboards, simply to monitor what is rising quickest. Her state pension is the foundation beneath her. Losing £140 each month has made her consider ending her phone contract and limiting herself to one proper meal a day. She laughs as she says it, but her eyes tell a different story.
Official figures already indicate that an alarming proportion of pensioners live near the poverty threshold. Remove almost £2,000 a year and a budget that was manageable, if tight, can turn into a permanent struggle to get by. This is not about giving up luxuries. It is about having socks without holes and a kettle that still functions.
At policy level, the reasoning is presented as sensible. Governments point to long-term sustainability, demographic pressures and the growing expense of an ageing population. Life expectancy has increased, working-age taxpayers face pressure and the system must change. The logic of the spreadsheet exists, but it does not remove the shock.
The reduction quietly transfers more responsibility from the state to people in their 60s, 70s and 80s. At this point in life, they cannot simply “work more hours”, “retrain” or “invest differently”. The missing money must come from somewhere: limited savings, relatives, charities or doing without.
Policymakers may say the reduction is small in macroeconomic terms. On a national chart, it is a minor adjustment. At one kitchen table, it is a bag of food missing every week. That is the harsh everyday meaning of policy.
How to respond before December 2025
Silence and delay are the worst ways to respond to a cut like this. Panic is the second worst. Between those reactions is a practical space in which you can regain some control, even if the amount itself does not change.
Start by doing the difficult calculations properly. Do not rely on memory or rough estimates. Use paper, or a straightforward spreadsheet if you use a computer. List your current monthly income and then deduct £140. See what genuinely changes. Rent or mortgage payments are fixed, so food, heating, transport and small pleasures usually take the hit. Putting the figures in front of you can hurt, but it is the only way to replace fear with action.
Next, separate your “non-negotiables” from your “flexibles”. Put medication, essential bills and basic food in one column. Place subscriptions, habits, gifts and treats in the other. This gives you an initial view of what might be changed without compromising your health or safety.
After a lifetime of working, many people feel embarrassed about seeking help. That embarrassment can cost money. Before December 2025, one helpful step is to arrange a full benefits check through a charity or advice service, ideally face to face or using a trusted helpline.
Each year, older people leave billions of pounds in support unclaimed because they believe “others need it more” or assume they do not qualify. Housing Benefit, Council Tax Reduction, Pension Credit and disability-related support may each add relatively small sums, but together they could more than compensate for a £140 reduction in some households. Let’s be honest: nobody willingly reads pages of administrative jargon every day.
There may also need to be a conversation with family, even if the prospect is uncomfortable. This does not necessarily mean asking for money; it can mean explaining the situation early. Children and grandchildren may be able to assist with digital administration, finding cheaper deals or sharing resources. Breaking the silence is usually the hardest part.
“I thought talking about money would make me look weak,” says Brian, 76, from Leeds. “Then my daughter looked at my bills for 20 minutes and saved me £60 a month. I felt stupid and relieved at the same time.”
This is where modest, useful actions can make a difference. They may not be glamorous, but they are practical:
- Moving to social tariffs for broadband or mobile phones where these are available.
- Looking into energy support schemes for vulnerable or older households.
- Examining insurance, television packages and subscriptions ruthlessly.
- Considering local food co-operatives, community fridges or inexpensive lunch clubs.
- Keeping a simple money diary for a month to identify unnoticed spending.
In a favourable month, a careful combination of these measures may recover a surprising proportion of the missing £140. In a difficult month, they can at least stop the gap from becoming overwhelming.
What the £140 state pension reduction says about ageing and money
A £140 reduction is not just an accounting entry; it also signals how a country regards its older people. Are they a cost to be controlled, or people to be valued after decades of work and taxation? Part of the answer lies in how easily decisions like this are accepted, or resisted.
For many people, the state pension was presented as a promise: contribute throughout your life and receive a reliable foundation in retirement. Seeing that promise reduced, however slightly, can bring not only worry but a muted feeling of betrayal. It can feel as though the rules changed after the game had finished.
Yet the other side is familiar too. People are living longer, healthcare costs more and younger workers are under strain. The system is straining under demands it was not originally designed to carry. That does not make the reduction seem fair, but it shows the tension will not disappear. On a human level, people are being forced to reconsider what “old age” and “enough” actually mean.
Most of us have experienced a financial worry sitting in the room like an unwanted, very loud third person. This pension cut will create thousands of those silent presences in living rooms across the country. Some people will react angrily, some will accept it with resignation and some will quietly organise.
Perhaps the most truthful response is a combination of all three. Anger can drive campaigns, letters to MPs and discussions in community centres. Resignation may help people remain polite while queuing at the Post Office. Organisation - lists, entitlement checks and awkward conversations - is what can prevent the missing £140 from taking over everything.
It is simple to say “plan ahead” from a comfortable distance. It is far harder when your financial margin was already paper-thin. Still, small acts of clarity now - knowing your precise figures, claiming what you are entitled to and discussing it with real people - can reduce the impact when December 2025 arrives.
The cut is real. At least in part, the response has yet to be written.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Size of the cut | Reduction of £140 per month from December 2025 | Assess the direct effect on your monthly budget |
| Immediate actions | Precise budget review, entitlement check and contract renegotiation | Save tens of pounds each month in response to the reduction |
| Possible support | Unclaimed benefits, social services, and family and local networks | Expand resources beyond the state pension alone |
FAQ
- Will the £140 state pension cut affect everybody? Not everyone will necessarily be affected in the same way. The precise impact depends on the state pension you receive, your National Insurance contribution record and any additions or credits. Some groups could be protected or receive partial compensation through means-tested benefits.
- Can I take action to stop or contest the cut? You cannot prevent the policy on your own, but you can contact your MP, support campaigns and join organisations representing pensioners. Collective pressure can sometimes influence how reforms are introduced or compensated.
- Can the lost £140 be replaced? Replacing the whole amount is difficult, but a combination of unclaimed benefits, lower bills and small sources of income, such as occasional part-time work or letting a spare room, may close some of the gap for certain people.
- Should I revise my retirement plans because of this? If you have not retired yet, it is sensible to review your plans. This could involve working a little longer, increasing private savings where possible or changing your expected retirement spending.
- Where can I find reliable help with my pension position? Seek recognised charities, Citizens Advice, government-backed pension guidance services or regulated financial advisers. Avoid anyone promoting quick fixes or high-return schemes, or demanding large upfront fees.
Comments
No comments yet. Be the first to comment!
Leave a Comment