
The kettle switches itself off, the washing machine murmurs in the background, and your phone buzzes with confirmation of another payment.
It is an ordinary Tuesday evening. The lounge light has been on since the afternoon despite nobody properly using the room. A magnet on the fridge holds a “monthly bills” list that was written months ago and has never been revised. You look at it, let out a sigh, then open a food-delivery app rather than cook the groceries gradually going off at the back of the fridge.
None of this seems lavish. It is simply everyday life: routine habits and little taps on the “OK” button. But by month-end, your bank balance appears to have been leaking away unnoticed. There is no major purchase to blame and no extravagant splurge. Instead, there is a nagging feeling that money is disappearing in ways you cannot see. And it is.
Invisible leaks: how everyday life silently drains your bank account
Most households do not lose money through dramatic financial errors. It tends to disappear through minor, tedious costs that seem far too small to matter: a £9.99 subscription, an insurance policy you forgot about, or heating turned up “just for tonight” and never adjusted afterwards. Separately, each choice seems harmless; combined, they can consume a whole week’s wages.
The clever part is that it all feels completely routine. Nobody gets up and thinks, “Today I will waste £150.” It is more often, “I’ll deal with that contract next month”, “It’s only a coffee”, or “The kids enjoy that channel, so let’s keep it.” These quiet leaks do not set off warning bells. They simply continue, month after month.
Consider Emma and Lucas, a couple in their mid-30s renting a small flat on the edge of London. After their rent increased, they believed they had reduced their spending as far as possible. They stopped buying clothes, avoided big evenings out and cooked at home more frequently. Yet their account went into the red for three consecutive months.
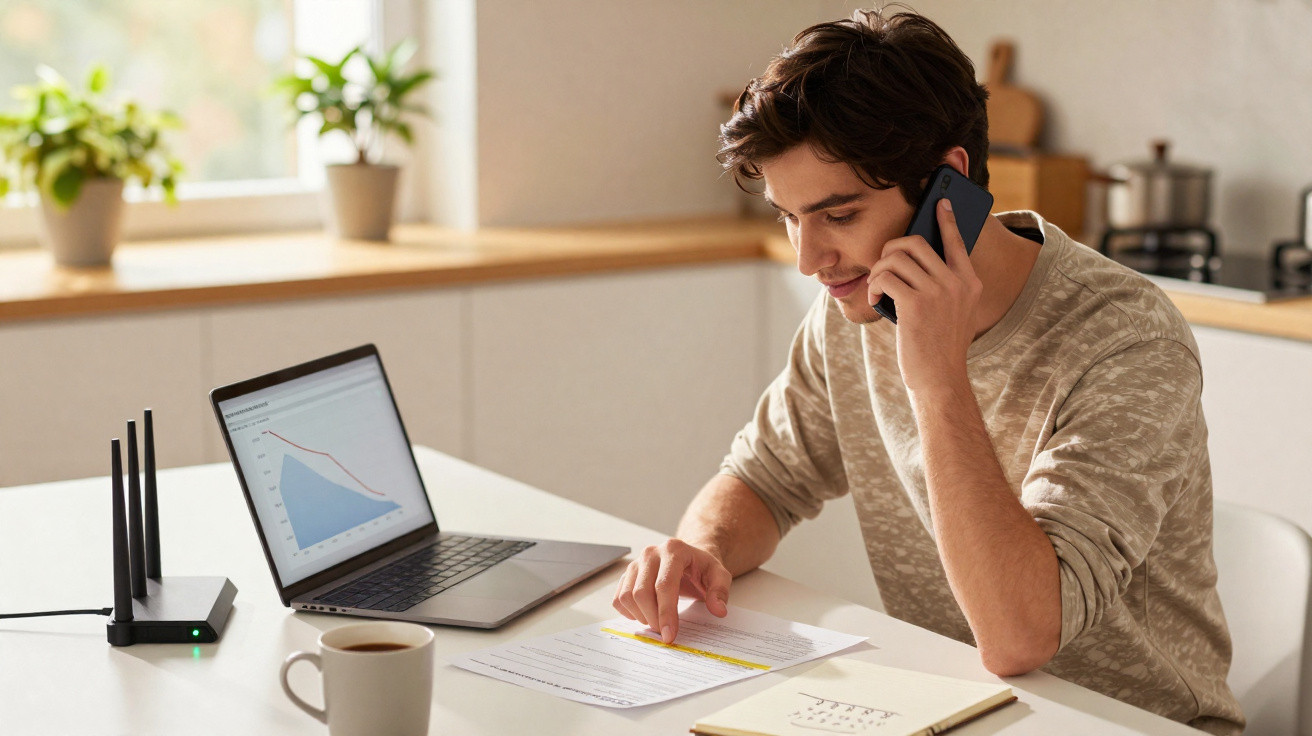
One evening, they printed out three months of bank statements and reviewed them with highlighters. What they found surprised them: £57 on unused app subscriptions, £38 in bank charges for dipping slightly into their overdraft, and about £90 on food deliveries made “because we’re tired”. There was also Lucas’s gym membership, untouched since winter. In total, roughly £260 per month was disappearing on payments they barely recalled making.
Emma and Lucas appeared careful on paper. They compared supermarket prices and did not buy designer labels. However, the leaks were happening quietly in the background, driven by convenience, exhaustion or simple forgetfulness. Their problem wasn’t big spending. It was unobserved spending.
This is how many households lose money without noticing: not through one major choice, but through dozens of small patterns left unexamined. The mind treats recurring payments as “already decided”, meaning they drop out of conscious thought. Standing orders, automatic renewals and “free trials” that quietly become paid plans all take advantage of that blind spot.
Energy tariffs that were competitive two years ago may now be hugely overpriced, yet few people want to spend an evening using comparison websites. Streaming services accumulate. Insurance policies renew automatically at higher prices. Meanwhile, everyday comforts such as takeaway coffees, last-minute food deliveries and branded cleaning products can add up to startling annual totals. The reasoning remains the same: one small exception will not hurt. Until every exception does.
How to plug the leaks: easy steps that free up money without deprivation
The strongest first step is not exciting: spend 30 minutes with your banking app and scroll through the previous 60 days. You do not need a spreadsheet. Just sort expenses mentally into three groups: “essential”, “nice but optional” and “why am I paying this?”. This is not about criticising yourself; it is simply about becoming aware.
Immediately cancel or downgrade one item in the “why am I paying this?” group. Do not wait until tomorrow or until you have “checked something”. Do it now. It could be an abandoned app subscription, an extended warranty for a device you no longer own, or a second streaming service you hardly watch. In under five minutes, that one step can often release £10–£40 each month.
Next, look at energy and telecommunications. Review your broadband, mobile and energy tariffs, and compare at least one alternative for each. Ring your existing supplier and say calmly: “I’m checking cheaper offers and thinking of switching.” Often, they will suddenly “discover” a discount or retention deal. One brief call can lower recurring costs for a full year. It may be dull work, but doing it once can save hundreds.
Food and “little treats” are another major source of unnoticed waste. During a stressful week, a tired mind is not focused on the budget. It wants comfort, which often arrives as delivered food, takeaway coffee or a quick late-night impulse purchase while scrolling.
In a typical month, many families throw away roughly 10–20% of the food they purchase. This is not only an environmental waste problem; it is money going straight into the bin. Add two or three food deliveries each week, and you may effectively pay for your groceries twice. On a card statement, these are merely separate transactions. Emotionally, they can feel like a way to get through the day. Financially, they are a gradual drain.
Let’s be honest: nobody really manages this perfectly every day. Nobody is flawlessly disciplined. The practical solution is not “never order food again”; it is setting a sensible limit beforehand. For instance: “two deliveries per month, maximum, and only on truly chaotic days.” This turns a partly hidden leak into an intentional choice with clear boundaries.
“The goal isn’t to live like a monk. It’s to make sure your money is actually buying you something you value, instead of dissolving into stuff you don’t even remember.”
That observation came from a financial coach who works with ordinary families rather than high earners. It reflects the emotional aspect of the issue. Money leaks can leave people feeling powerless and mildly guilty, even where their income is genuinely limited. Plugging them is less about moral willpower than about clarity and being kind to yourself.
In practical terms, these are some quick wins that households often find during a “leak hunt”:
- Moving to a cheaper energy or mobile tariff after one comparison call.
- Having a straightforward weekly “use-up-the-fridge” evening to reduce food waste.
- Keeping every subscription in a single phone note, including renewal dates.
- Setting aside a modest “fun money” budget so treats no longer feel like failures.
- Using savings from cancelled services to reduce one persistent debt.
In a good month, these adjustments can free up £100–£300 without affecting your rent or income. In a difficult month, they may mean the difference between falling into overdraft charges and staying just afloat. We have all experienced the sinking feeling of a card being declined at the supermarket. These small changes offer a quiet way to prevent that moment.
From invisible leaks to conscious choices
Once you have spotted the leaks, they are difficult to ignore. You may start seeing electronics left on standby all night, duplicate subscriptions to similar services, or the supposedly occasional takeaway that has become a twice-weekly routine. Initially, it may feel awkward, rather like viewing unfiltered photographs of your own life.
That unease has value. It shows that you are beginning to connect your money to your real priorities rather than simply following the easiest option. You can start asking gentler questions: “Does this still make sense for us?” “Are we really using this?” “Would I rather keep this subscription or bring our next holiday a little closer?”
Some families make finding leaks into a game. Others do it privately, late at night, with a cup of tea after the children are in bed. Either approach works because the real shift is from “I don’t know where it all goes” to “I can see where it goes, and I’m changing a few things.” No drama and no perfection-just small, purposeful actions.
What catches many people off guard is that they do not feel deprived. Instead, they often feel lighter: less clutter, fewer pointless payments and more space for what genuinely matters, whether that is a weekend away, an emergency buffer, children’s activities or simply not fearing the bank notification at the end of the month.
Money leaks flourish when they remain hidden. Discuss them with your partner, friends or even colleagues. Share the strangest subscription you uncovered or the biggest saving you made through a 10-minute call. That is how useful knowledge circulates, turning private waste into shared experience and practical advice. Sometimes, the most helpful discussion is not about making more money, but about finally keeping more of what you already earn.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Identify invisible spending | Spend 30 minutes reviewing statements to find subscriptions, bank fees and repeated small purchases | Can quickly recover £50–£200 per month without changing your standard of living |
| Renegotiate contracts | Contact energy, mobile and broadband providers to request a cheaper offer | Reduces fixed costs for 12 months or more after a single call |
| Control “little treats” | Set a clear limit for deliveries, coffees and impulse purchases | Turns guilt into deliberate choices and protects the budget without total deprivation |
FAQ
- How do I know if I’m really wasting money or just living normally? You are “wasting” money when payments no longer give you value, such as unused apps, forgotten contracts or food that ends up in the bin. Living normally means your spending reflects what you genuinely use and enjoy.
- How often should I review my subscriptions and bills? Once or twice yearly is generally sufficient. A quick 30–45-minute review can identify most leaks and stop companies quietly increasing your prices.
- What if my income is already low – is there still room to save? Often there is, even when it seems impossible. Cancelling one unused service, cutting food waste or avoiding overdraft fees can still build into a meaningful difference over time.
- Is tracking every expense really necessary? No. Many people find it exhausting. A simpler approach is to inspect only the past 1–2 months of statements, identify patterns and tackle the largest leaks instead of recording every coffee indefinitely.
- How can I stop myself from falling back into old habits? Make the new decisions easier to follow: unsubscribe from marketing emails, remove food-delivery apps from your home screen and set reminders before renewals. Small barriers make it easier to stick with what you chose.

Comments
No comments yet. Be the first to comment!
Leave a Comment