
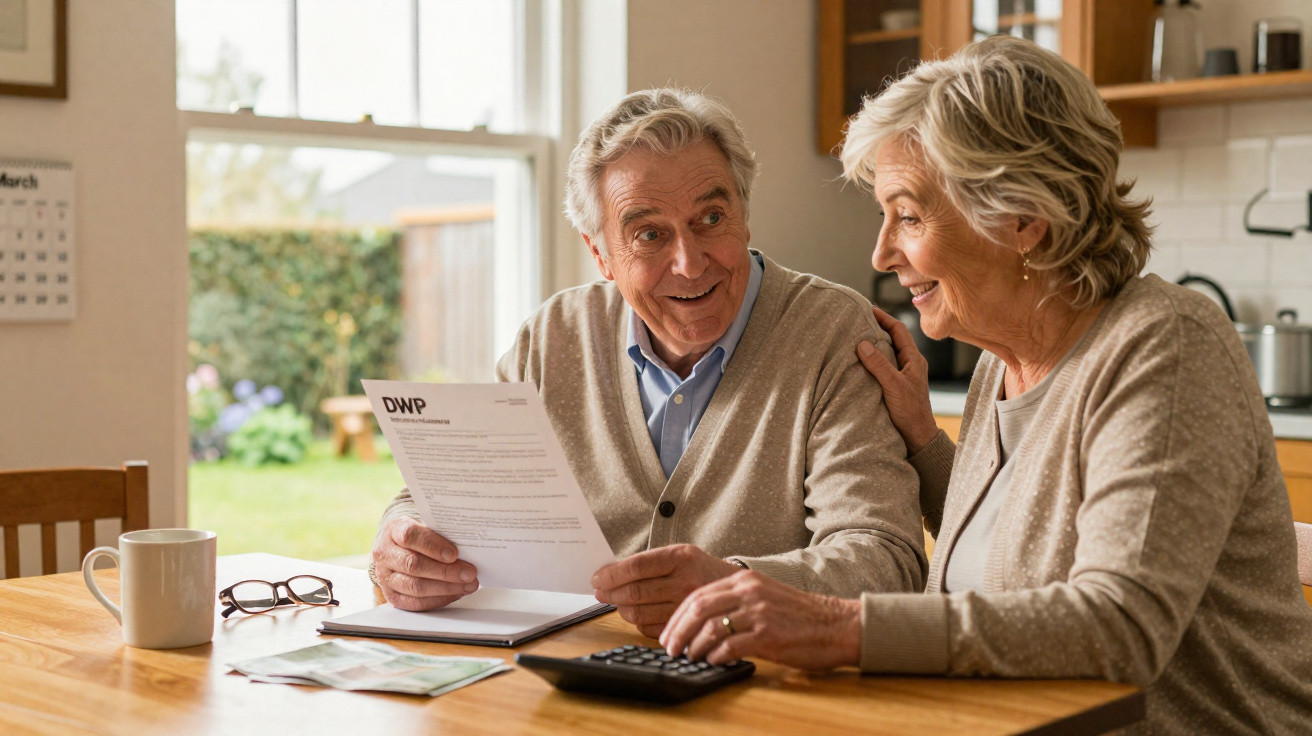
The envelope came through the letterbox shortly after 10am, making its familiar light thump against the mat. Margaret, 67, walked over in her slippers, expecting the usual uninspiring broadband flyer or pizza promotion. But the brown DWP logo caught her eye, and she felt a slight tightening in her chest. At the kitchen table, with her glasses slipping down her nose and a mug of cooling tea beside her, she carefully opened it. The first words she noticed were “your State Pension is changing”. Then she saw the figures. She checked them twice. Then once more.
This time, at least, it was not bad news.
DWP State Pension ‘shock increase’ – what is changing in March?
Throughout the UK, pensioners born before 1959 are hearing a similar story from neighbours, grandchildren and daytime television: the DWP is preparing a larger-than-anticipated increase in State Pension payments this spring. It is not the one-off £10 Christmas bonus, but a genuine uplift. For anyone standing in the supermarket and worrying about the cost of butter, it could ease the anxiety a little.
Many people will first notice the change in their bank accounts on their March payment date. Some will receive only a few extra pounds each week. For others, particularly those receiving the full new State Pension, the increase may appear unexpectedly substantial. On this occasion, the word “shock” is not simply tabloid exaggeration.
Consider people receiving the full new State Pension, generally those who reached State Pension age after April 2016 and now including many people born from 1954 onwards. During the 2023/24 tax year, they received £203.85 a week. Under the triple lock calculation, alongside last year’s persistently high inflation figure, this is due to increase to about £221.20 a week from April 2024.
That represents an uplift of around £18 each week, or nearly £936 over a full year. For someone counting coins to top up the meter, it is far from insignificant. Since many March payments cover weeks that run into the new financial year, it is easier to see why this is being described as a “shock increase”. The higher figures can arrive sooner than people expect.
The reason lies in the triple lock, the Government commitment that the State Pension will rise each year by whichever is highest: wage growth, inflation or 2.5%. Following last year’s 10.1% increase, many people expected ministers to quietly weaken the policy. Instead, strong earnings growth data resulted in another sizeable increase.
For the Treasury, the triple lock is an expensive problem. For a person born in the 1940s or 1950s who has watched their heating direct debit steadily rise, it can feel like overdue recognition of decades spent paying National Insurance. For once, the system has tilted slightly in favour of people who’ve already paid in their share.
Who receives what from the State Pension – and how not to miss out
The most useful starting point is identifying which State Pension you receive. Men born before 6 April 1951 and women born before 6 April 1953 will usually be covered by the old, “basic” State Pension. Those who reached State Pension age later are normally on the newer scheme. Both amounts are increasing, though not by identical sums, which is where much of the uncertainty begins.
For many people born before 1959, particularly women who spent time outside paid employment, their pension is a mixture of basic pension, additional State Pension and potentially credits. When a percentage increase is applied to each part, the detail can be easy to lose among the small print. This is why it is sensible to access your online State Pension forecast, or ring the DWP, and ask one clear question: “What will my weekly amount be from April?”
Most people know the feeling of listening politely while someone explains pensions or benefits, only for the information to become overwhelming. Linda, 70, from Birmingham believed she was already receiving everything due to her. Her grandson later helped her review her pension record online. It showed gaps in her National Insurance history from the 1980s which she could still fill through voluntary contributions.
She spent a few hundred pounds filling those missing years, but the resulting increase in her weekly State Pension, together with the March/April rise, means she will receive nearly £900 more each year for the rest of her life. It is not a lottery win, but it is enough to switch on the heating sooner and occasionally agree to a coffee out. Quiet gains often come from these modest, slightly unexciting checks.
The background figures remain difficult. Food still costs considerably more than it did only a few years ago. Energy bills fell slightly before beginning to edge upwards again. Council tax is set for another rise. The triple lock increase cannot remove the pressure, but it may prevent people moving from “just coping” into a full crisis.
In truth, few people read every line of a DWP letter on the day it arrives. Plenty of pensioners may only spot the difference when their balance is a little healthier on a Monday morning. That makes clear, understandable information important. This is not a bonus that requires an application or a scheme that must be pursued. It is an automatic uprating built into the system. Even so, it remains worthwhile to understand broadly why a payment has changed and what further support may now be available alongside it.
How to make the March ‘hike’ create genuine breathing space
One straightforward way to make the increase work harder is to regard it as separate “mini income” for the first couple of months. Once your March and April State Pension payments arrive, identify the difference from last year and place that additional amount in a separate pot, even if this is only a named space within your online banking.
After several weeks, assess the biggest strain on your budget. It may be heating, rent, essential groceries or debt repayments. Direct the extra money towards that one priority. Giving it a single purpose is more effective than allowing it to vanish into the wider blur of household bills. Many older people currently feel they have little control over their money. Seeing the additional amount and deciding its use can restore a little of that control.
A frequent misunderstanding is that an increased State Pension means every other benefit will automatically rise around it. For people receiving Pension Credit, Housing Benefit or Council Tax Support, the outcome may be complicated. A higher pension can slightly reduce means-tested help. The overall position is usually still better, but the improvement may be less than expected.
There is an emotional element too. Many older people feel uncomfortable even considering a request for further help, as though they would be taking advantage of the system. They are not. They have paid in, and they have every right to ask about every pound. If contacting the DWP feels daunting, local advice centres and charities such as Age UK can help by making the call with you or on your behalf. A little human support can make a significant difference.
“After my husband died, I stopped opening half the letters,” says Joyce, 78, from Hull. “I thought, what’s the point, they’re just telling me what I already know – that everything’s going up. When my neighbour told me about the March increase, I thought she’d got the wrong end of the stick. Then my payment came in. I cried in the bank queue. Not because it was thousands, but because someone, somewhere, had remembered we exist.”
- Check your State Pension forecast online or by telephone before April.
- Ask directly what your new weekly rate will be from the beginning of the new tax year.
- Write down every regular bill, then choose where the additional money will have the greatest impact.
- Speak to your council or a charity about reviewing Council Tax Support and other entitlements.
- Discuss the changes with relatives or friends, as they may identify options you have overlooked.
A quiet turning point for people born before 1959
For the generation that rebuilt Britain after the war and paid National Insurance through three-day weeks, recessions and factory closures, this State Pension increase is not a windfall. It is a modest move towards dignity. Many people born before 1959 did not have workplace pensions as generous as those offered in later years. Many also left employment early to care for children, partners or parents, while their private savings were worn down by years of extremely low interest rates.
When slightly higher payments reach accounts this March, there will be no dramatic moment. There will be no fireworks or Ten O’Clock News headline. Instead, it may mean a little extra room in the shopping basket, a bus journey without guilt, or the chance to heat the home for another hour. Debate around the triple lock will continue, but the human reality is more straightforward: a few additional pounds in the right hands can alter the feel of an entire day.
| Key point | Detail | Value for the reader |
|---|---|---|
| Triple lock rise | State Pension is due to rise by the highest of earnings, inflation or 2.5% | Explains why payments are increasing by more than expected |
| Who is affected | Most pensioners born before 1959 will receive a higher weekly rate from March/April | Helps readers understand whether they or their relatives may benefit |
| Action steps | Check your forecast, review benefits and set aside the extra for essential bills | Converts a technical increase into practical breathing space |
FAQ:
- Will every pensioner born before 1959 get this State Pension increase? Most will. The yearly uprating applies to both the basic and new State Pension, so anyone receiving a State Pension from the DWP should see their rate increase from April, with some payments showing this in March.
- How much extra will I actually see per week? Your own record determines this. People receiving the full new State Pension are expected to gain around £18 a week, while those on the basic State Pension will receive a smaller, though still meaningful, increase.
- Do I need to apply for this March ‘hike’? No application is required. The increase is automatic, will be included in your regular payment and should appear on your award letter and bank statement.
- Could this rise affect my Pension Credit or Housing Benefit? Yes. A higher pension may slightly reduce some means-tested benefits, although many people will still be better off overall. It is sensible to arrange a benefits check once the new rates begin.
- What if I think my new State Pension amount is wrong? Contact the Pension Service immediately and request a breakdown of how your amount was worked out. Free support is also available from organisations such as Citizens Advice or Age UK if you need to challenge an error.

Comments
No comments yet. Be the first to comment!
Leave a Comment