
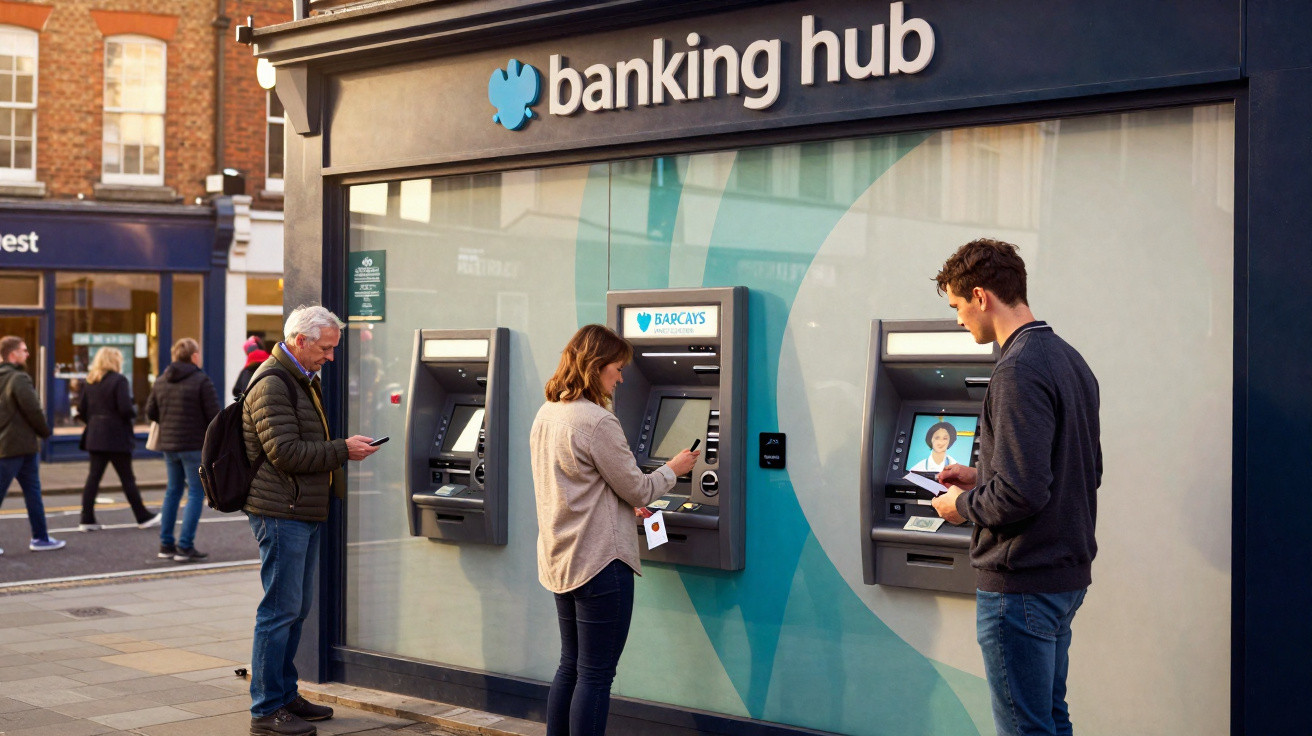
The change will not happen today or tomorrow, but the clock is already ticking. Three major banks have discreetly confirmed plans to remove hundreds of ATMs from high streets, and the biggest surprise is not their disappearance but their replacements. Biometric “cash hubs”, app-only kiosks and shared machines unaffiliated with a single bank are on the way. It is the sort of technology that resembles an airport check-in desk more than a traditional cashpoint.
One wet Tuesday evening in London, I saw an elderly man tap his card against a bank door, pause, then look baffled at the polished screen beyond it. There was no cash slot and no keypad, only a QR code and a menu of “digital services”. He turned towards the unlit ATM where he once withdrew £20 for fish and chips, then shook his head as though he had just missed the final bus home.
He is far from alone in reacting this way. Customers from Birmingham to Brighton are finding that the familiar routine of popping to the cashpoint is gradually being withdrawn. Machines that dispensed tenners and twenties for years are being removed or deactivated, frequently with little warning. In their place is an emerging banking network that still feels unfamiliar.
Banks call it progress. Many customers feel shut out.
The key issue lies in what is scheduled for 2026.
Three banks and a quiet high-street revolution
A walk along almost any UK high street already reveals the first clues. Three ATMs outside a major bank branch may have become one. Screens carry “Out of service” signs that appear to remain indefinitely. From 2026, Barclays, NatWest and Lloyds Banking Group - three of the UK’s largest banks - are expected to speed up the transition by removing hundreds more cash machines.
This is not an arbitrary process. Internal assessments indicate that certain ATMs now handle only a small number of withdrawals each day. To banking executives, those figures represent costly metal units consuming electricity, maintenance funding and security resources. The resulting decision is taken in a meeting room far away: remove the machine, close the branch and send customers elsewhere.
Nationwide and HSBC are reducing their networks as well, but Barclays, NatWest and Lloyds are pursuing the next stage most forcefully. Their message is straightforward: cash use is declining, and the machines built around it are declining too.
Consider one example. A coastal town in the North of England had four ATMs operated by three banks along one short street a decade ago. By late 2024, only one remained: an ageing, independently branded machine in a convenience store, with a flickering display and a charge for withdrawals above a certain sum.
Residents told the council that they now travel to the next town to obtain cash at weekends. Local retailers report displaying more “sorry, card only” notices, not because they object to cash, but because customers can no longer be relied upon to have it. One older resident said she plans shopping trips around the times when the shop ATM is least likely to have run out of money.
Repeat that situation across hundreds of towns and suburbs and the national pattern becomes clear. Access to cash is not an abstract policy debate. It is the customer ahead of you in the corner shop who cannot pay because the final free ATM disappeared months earlier.
From the banks’ perspective, the reasoning is clear. UK ATM withdrawals have fallen by billions of pounds since the pandemic, while higher contactless limits and mobile banking apps have become widespread. As fewer people use each machine, the operating cost of every transaction rises sharply. For boardrooms focused on efficiency, the calculation is unforgiving: every underused ATM resembles a leaking pipe.
The approach is therefore changing. Rather than each bank maintaining an isolated machine on a street corner, they are testing shared services, centralised “hubs” and digital-first contact points. The aim is to replace a broad but sparse ATM network with fewer, more flexible locations offering more than cash withdrawals.
The model looks orderly on paper. On the pavement, it feels like a gamble that everybody will adapt quickly enough.
What will replace ATMs from 2026 - and how it will work in practice
The main development is the expansion of shared “banking hubs”. Rather than Barclays, NatWest and Lloyds each operating separate cash machines in one town, one shared venue will provide withdrawals and deposits for customers of several banks. Think of it as a neutral cash-access site open to all major brands, staffed on a rotating basis or assisted through video booths.
These hubs are already being trialled in certain communities, but they are expected to become considerably more widespread from 2026. You may enter a space that feels like a cross between a Post Office and a compact bank branch. It could contain several advanced machines for depositing and withdrawing cash, some desks, and perhaps a staff member who spends much of the day helping people who “just want to talk to someone, not a screen”.
App-connected deposit machines are also being introduced. Customers sign in to their banking app, create a code, tap it at the machine and pay in notes or coins without using a card. Some banks are also testing QR-code withdrawals, turning a phone into the key for accessing cash.
For anyone dependent on cash, the most practical move is starkly simple: identify future access points now, rather than waiting for the local ATM to vanish. Go to your bank’s app or website and locate the section for “cash machines” or “cash access points”. Many people do not use this feature until they are outside a darkened machine in the rain.
Check the location of your nearest Post Office and the services it provides for your bank. An increasing number of high-street banks allow customers to deposit and withdraw cash at Post Office counters as though they were using their own branch. The arrangement can be messy, mildly confusing and far from glamorous, but it may preserve cash-based routines.
There is also the unexciting yet useful practice of planning cash in the same way as a food shop. If you will need notes for a weekend event, withdraw them during the week, when machines in busy locations are more likely to be working and stocked. People should not need to organise their cash this way, but it is the reality banks are gradually creating.
The problem arises when people assume, “There’ll always be another ATM around the corner.” That was once true, but it no longer is. Many people grew up regarding cashpoints as permanent street furniture: available, free and functioning. That assumption persists, which is why their sudden loss can feel as though a routine has been pulled away without warning.
If you have elderly relatives, neighbours or anyone uneasy with apps, discuss this with them calmly before it becomes an emergency at the chemist or bus stop. Show them their nearest future cash-access locations. Put the details on paper if that is the format they are most likely to remember. Let us be honest: nobody really does this every day, but doing it occasionally is enough to prevent major inconvenience.
Fees also require attention. As bank-branded ATMs disappear, independently operated machines that charge for withdrawals may quietly replace them. A single hurried withdrawal in an unfamiliar place can mean paying to access your own money because the free machine was removed the previous month.
“We’re not getting rid of cash,” one senior executive at a major UK bank told me privately. “We’re getting rid of the old way of handling it.” For him, 2026 is less about scrapping ATMs and more about pushing people into a cleaner, app-led ecosystem where every transaction is tracked and tidy. For the woman who still leaves £20 in a kitchen drawer “just in case”, that sounds less like progress and more like surveillance with a glossy interface.
So, what should you watch for as this transition begins? Several signs repeatedly emerge in discussions with customers, bank employees and local campaigners:
- Branch closure letters referring to “alternative ways to access cash” - usually meaning hubs, Post Offices or partner sites.
- Ongoing “temporary” ATM outages that are never resolved, often a familiar indication that a machine is being withdrawn.
- New in-store machines in supermarkets or pharmacies that require an app or phone rather than simply a bank card.
Taken together with the announcements banks have already made, these signals show that the future of popping to the cashpoint is being reshaped in real time. Quietly, but undeniably.
A future without the familiar sound of the cash machine
By 2026, using a classic ATM - inserting a card, entering a PIN and pressing a worn, shiny plastic keypad - may feel more like a throwback than an ordinary habit. ATMs will not disappear altogether, but their number, location and method of use are all changing.
For some, the replacement systems will be effortless: tap, scan, withdraw and pay through one tidy digital record. For others, particularly rural residents, people in cash-heavy work or those who value the privacy of physical money, the change will hurt. The real divide will not be between the technologically confident and technophobes; it will be between those whose lives fit comfortably into an app and those whose lives do not.
In practical terms, the next few years will bring an unusual overlap. Shared hubs will sit beside closed branches. Bright touchscreen kiosks will occupy places where old ATMs once hummed. People waiting in queues will quietly guide one another through unfamiliar steps: “No, you scan this code here, then press that button.” At a human level, something more subtle is taking place: the gradual loss of a small freedom most people barely realised they possessed.
Everyone knows the situation: you are out late, your phone battery is nearly flat, and an anonymous glowing cashpoint on the corner saves the evening. No app and no Wi-Fi, only a card, a PIN and the reassuring sound of notes being counted. That experience is being redesigned by people who seldom need it themselves.
These three banks are doing more than removing ATMs. They are redefining the line between your money and the machines that protect it. What takes the cashpoint’s place in 2026 will make very clear which side of that line you are expected to occupy.
| Key point | Detail | Why it matters to readers |
|---|---|---|
| Gradual disappearance of ATMs | Barclays, NatWest and Lloyds will remove hundreds of cash machines by around 2026 | Understand why “your” cashpoint may disappear |
| Growth of shared “banking hubs” | Shared access points for several banks, offering withdrawals and deposits | Know where to find cash when the local branch closes |
| New app-linked digital tools | Machines linked to apps, QR codes and the Post Office as an alternative channel | Adjust routines and avoid charges or unpleasant surprises |
FAQ
- Will ATMs completely disappear by 2026? Not entirely. ATMs will remain, but there will be fewer of them, and more of those left will be located in shared hubs, supermarkets or partner sites rather than outside conventional branches.
- Which three banks are cutting the most ATMs? Barclays, NatWest and Lloyds Banking Group are among the banks most actively reducing their ATM networks and directing customers towards hubs, apps and alternative cash-access points.
- What exactly is a banking hub? A banking hub is a shared location where customers of several banks can deposit and withdraw cash, and may be able to speak to staff on particular days. It replaces several single-brand ATMs with one multi-bank access point.
- How can I still get cash if my local branch closes? You can often make withdrawals and deposits through the Post Office, find shared hubs nearby, or use in-store ATMs in supermarkets and shops - preferably free machines connected to major networks.
- What should I do now to prepare for these changes? Review your bank’s map of cash-access points, find your nearest Post Office and possible hubs, discuss the choices with vulnerable relatives, and watch for letters or emails about branch or ATM closures.
Comments
No comments yet. Be the first to comment!
Leave a Comment