
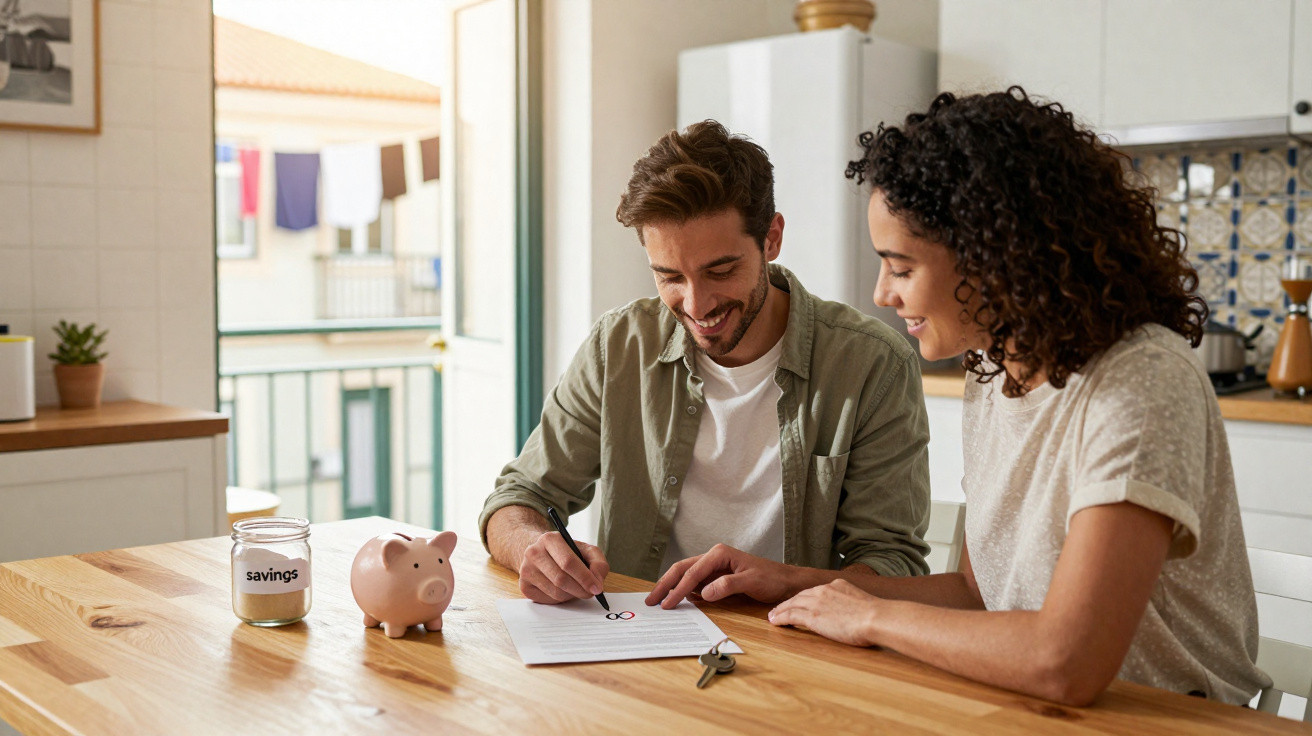
“So… zero down payment?” It is 2026, interest rates rise and fall like a terrible DJ set, but the ambition has not changed: stop handing rent to somebody else and finally see your own name on the letterbox. In the reception area, a young couple browse property listings that are plainly beyond their budget. By the coffee machine, a freelancer in trainers silently practises his pitch. No one here has €40,000 sitting untouched in a savings account.
Instead, they have an odd mix of worry and determined optimism. Rent consumes half their pay, parental help is not always available, and the conventional 10% deposit feels like something from a different era. Yet the same question is still asked in hushed tones, as though it should not be voiced. One line returns repeatedly, almost as a challenge.
“Is there any way to get a mortgage with 0 € down in 2026?”
Why 0 € down is suddenly being considered in 2026
Take a walk through any major European city on a Sunday afternoon and the pattern is obvious: people are fixed to property apps, bookmarking adverts they “just want to look at later”. The distance between what is on the screen and what is achievable can feel enormous. Property prices have risen for years while earnings have not kept pace. For an entire generation, the familiar route - saving for years before buying - appears to have stopped working.
Banks recognise this change. They understand that many creditworthy borrowers cannot simply set aside €30,000 or €50,000 for a deposit. In response, they adjust their products, speak of “affordability” and “financial inclusion”, and discreetly revive tools that had almost vanished: 100% mortgages, government-backed guarantees and tailored first-time buyer schemes. The rules remain, but access is not as restricted as many people assume.
Everyone knows the feeling when a landlord announces a rent rise and the calculation starts: “If only this money went into my own place instead.” That irritation is becoming a market driver in its own right. The resulting paradox is striking: although many people feel excluded, more routes are becoming available to buyers able to demonstrate reliability and financial discipline rather than a large savings pot.
Across Europe and further afield in 2026, several governments are expanding schemes that guarantee part of a mortgage for first-time buyers or households beneath particular income limits. Banks welcome this because it lowers their exposure. Buyers welcome it because they may borrow up to 100% of the purchase price - and occasionally slightly more to meet fees.
In France, for example, wider state-backed guarantees and redesigned PTZ-style schemes are under discussion to broaden eligibility in 2026. In some parts of Spain and Portugal, regional authorities are piloting 95–100% mortgages connected to new-build developments. Certain UK and Irish banks are reintroducing “no-deposit” products, subject to tight limits and affordability stress tests. Specific arrangements differ between countries, but the overall direction is consistent: more entry points, alongside more requirements.
This is not free money. Lenders still carry out demanding affordability checks, looking at fixed and variable earnings, debt-to-income ratios and spending habits. They need evidence that you could manage interest-rate rises and unexpected life events. The compromise is straightforward: putting down less upfront generally means larger monthly repayments, tougher insurance requirements and stricter terms if your circumstances alter. Offers with 0 € down are not really about generosity; they transfer risk from your savings to your future income.
Understanding that principle changes the question entirely. Rather than asking “Can I get 0 € down?”, ask “Under which conditions would a bank feel safe lending me 100%?” That is the point at which planning starts.
Practical routes to a 0 € down mortgage in 2026
There is no single 0 € down solution in 2026. It is more like a set of tools that can be combined. The first is a guarantee. Banks are much more comfortable lending 100% when another party shares the risk, whether that is a public guarantee fund, a financially strong guarantor or a professional guarantee provider. Meeting at least one of these criteria can immediately change the discussion.
The second element is your financial profile on paper. Lenders place huge value on stability. That does not always require a permanent employment contract, but it does require a history: two or three years of consistent income, limited existing borrowing and no disorderly overdraft use. Before raising the prospect of 0 € down, make your bank statements look as clean as possible for several months. Reduce unnecessary spending and get credit-card balances under control. It may sound unexciting, but it is among the most powerful actions you can take.
The final component is the property itself. Banks are more willing to accept zero deposit applications for “safe” properties: sensible locations, conventional flats, warranted new builds and energy-efficient homes. Very cheap derelict properties in remote areas or speculative micro-flats are often rejected outright. View a mortgage application as a joint project: you, your earnings and the property. Each part needs to appear credible alongside the others.
Consider Léa and Karim, both aged 29, who rent a one-bedroom flat for €1,050 per month. At the beginning of 2026, they believe homeownership is out of reach: each has take-home pay of €2,500, they have virtually no savings, and they are expecting a baby. Their bank’s online calculator virtually laughs at them. They choose another approach and arrange an appointment with a mortgage broker recommended by a colleague.
The broker reviews their payslips, secure employment contracts and rental record. “You’ve been paying over 1,000 € a month, on time, for three years,” she says. “That’s proof you can handle a loan installment.” She directs them to a regional scheme that guarantees 20% of the mortgage for first-time buyers under a defined income threshold. With this guarantee, a partner bank agrees to lend 100% of the purchase price for a modest €215,000 flat near public transport.
There is a catch: no deposit, but demanding conditions. They agree to a marginally higher interest rate, promise to occupy the property for at least six years and take out comprehensive borrower’s insurance. Their monthly repayment comes in just above their previous rent, although over a longer term. It is not a fairy tale - there will be months when they feel the strain - but they leave the notary’s office holding the keys, with a sense of possibility they would not have imagined 18 months before.
Stories of this kind are becoming increasingly frequent. Banks and public bodies favour them because they support neighbourhood stability and sustain housebuilding. Borrowers appreciate them because they challenge the idea that you must “save for ten years or forget it”. Yet there is an overlooked reality: these mortgages are designed to be secure for the system, not automatically manageable in day-to-day life.
The essential calculation is harshly simple: what share of your monthly take-home income can go towards housing without overwhelming everything else? Lenders commonly limit the debt-to-income ratio to around 30–35%. If a 0 € down mortgage takes you to that limit, there is little room for shocks. A career change, a child or a health problem can make everything more difficult. The risk is not 0 € down in itself; it is borrowing to the absolute maximum simply because the bank’s system says “Yes”.
This is why personal strategy matters more in 2026 than the name of the mortgage product. You may take a fully financed mortgage and still sleep comfortably if you retain enough headroom. Equally, you can decline, even when the banker is encouraging you. Let us be honest: hardly anyone genuinely does that every day.
How to improve your prospects and avoid familiar traps
If your aim is 0 € down, approach the next six months like a training programme. Begin with a straightforward test: act as though you already have the future mortgage. If your rent is €900 and you expect future repayments of about €1,150 each month, set up an automatic €250 transfer on payday into a savings account that you do not touch.
Keep it up for long enough and you demonstrate two things simultaneously. First, you prove to yourself that this budget is liveable without panic. Second, you show a prospective lender that you can save consistently, creating a record of discipline even where the final mortgage covers 100% of the purchase price. Paradoxically, imitating a mortgage can make obtaining one easier. It also builds a modest reserve for removal costs, furniture or an unforeseen plumbing repair.
Your next step is to compare the market thoroughly. Do not rely solely on your existing bank, as it will often offer the narrowest range of possibilities. Speak to one or two independent mortgage brokers, preferably advisers who know local and national 2026 schemes inside out. You are not only comparing interest rates. You are weighing up flexibility: early repayment conditions, insurance choices, options to vary monthly repayments and penalties should you move earlier than intended.
A major trap on the 0 € down route is embarrassment. People conceal their true financial position because they hope to “look good” to the bank. That approach often backfires. Be completely open with your broker about side work, debts, financial support sent to family and everything else. They can only put together a robust application if they see the full picture. The worst outcome is not receiving a “No” today - it is receiving a “Yes” for a mortgage you cannot genuinely afford to carry.
The same errors occur repeatedly. Some buyers become attached to a property before discovering that the bank will not provide 100% finance for that kind of asset. Others overlook purchase and moving costs, then run up credit cards during the first year. A minority believe marketing lines such as “rent is throwing money away” and push their debt ratio into the danger zone, leaving no room for life changes. At that stage, ownership can feel like a burden rather than an achievement.
Emotionally, expect uncertainty. Friends and relatives may issue strong warnings: “Zero down? That’s crazy, you’ll get burned.” At times they are projecting their own worries, and at other times they may be correct. Hear them out, then return to the figures. Is your budget realistic? Have you stress-tested it for interest-rate rises and several unwelcome surprises? If the numbers still work, their anxiety does not need to become yours.
“The best sign you’re ready for a 0 € down mortgage isn’t the bank’s approval,” says one seasoned broker. “It’s your own answer to this simple question: if my income drops by 15 % tomorrow, can I survive without defaulting?”
- Never take the maximum mortgage simply because the bank is prepared to offer it.
- Retain at least one month’s expenses as an emergency reserve, even with 0 € down.
- Read every line of the insurance policy, particularly where self-employed earnings are concerned.
- Negotiate flexibility as well as interest rates: payment breaks, term extensions and partial repayments.
- Remember: saying “not yet” this year can mean “yes, on better terms” next year.
Owning with 0 € down: a change of mindset, not a miracle
Ultimately, zero deposit is less about cash held in your account than your relationship with time, risk and stability. You are exchanging future earnings for bricks and mortar today. That exchange can feel liberating or suffocating. The decisive factor is whether you enter into it with clear eyes or through rose-tinted glasses.
For some people, 2026 will be the year they make the move from renting to owning without accumulating tens of thousands of euros. They will step into “their” home for the first time, a little frightened, a little exhilarated and fully aware that every monthly payment matters. They will give up the flexibility of renting for the long, steady task of reducing a mortgage. It is not glamorous. It is profoundly ordinary. That is precisely where its strength lies.
Others will examine the same offers and turn them down. Not because they have “failed”, but because the pieces do not yet fit: uncertain work, a fragile relationship or unclear plans for the future. Refusing a 0 € down mortgage can be a highly mature choice. The real change is that, in 2026, there is a range of options where there was once only one rigid route.
Ask people around you the same question and you will see how personal it is: “Would you buy with 0 € down if the bank said yes tomorrow?” Some will reply immediately. Others will pause. Some will begin making discreet calculations on the back of a receipt. Somewhere within those reactions, you will identify your own position - your balance of caution, ambition and long-term perspective.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| 0 € down financing routes | A combination of public guarantees, 100% bank mortgages and first-time buyer schemes | Identify practical options for buying a home sooner |
| Preparing the application | A record of stable income, well-managed accounts and repayment simulations before purchase | Improve the likelihood of approval and negotiate better terms |
| Managing risk | Debt-to-income limits, a safety margin and mortgage contract flexibility | Protect everyday finances and prevent 0 € down from becoming a burden |
FAQ
- Can I really get a 0 € down mortgage with an unstable income in 2026? It is challenging, though not impossible. If you are self-employed or on short-term contracts, lenders will want a longer track record, tax returns and stronger risk protection. In practice, many 100% financing offers are aimed at people with at least two to three years of reasonably predictable earnings.
- Are interest rates higher on 0 € down mortgages? Frequently, yes. Banks account for the additional risk through a small rate premium or tighter conditions elsewhere. The important issue is not only “Is the rate higher?” but “Does the complete monthly cost, including insurance and fees, remain safely within my budget?”
- Do I still need some savings if the loan covers 100% of the price? Yes. Not for the deposit, but for notary fees, removal costs, essential furniture and an emergency reserve. Some schemes fund part of the fees, but starting with literally no money set aside makes the first year extremely precarious.
- Is renting always worse than buying with no down payment? No. Renting provides flexibility to relocate for work, alter family plans or avoid long-term commitments. A stretched 0 € down mortgage can feel more burdensome than rent you can comfortably afford. The right decision depends on your timeframe and how stable your life appears over the next 5–10 years.
- How can I know if a 0 € down offer is “too risky” for me? Carry out your own stress test. Work out your budget with an interest rate 1–2% higher, imagine a 10–15% reduction in income and include one substantial unexpected expense during the first year. If the figures only work under the most optimistic conditions, the offer is likely too tight to be comfortable.
Comments
No comments yet. Be the first to comment!
Leave a Comment