
Your hobby ought to energise you, not steadily empty your bank account. Financial worry has no place alongside paint-marked jeans, muddy trails, guitar picks or the spark of saying, “I made this.”
The payment went through, as it always did. Yet later, sitting at my kitchen table, I watched my banking app shift from an upbeat green to a weary amber. I had no regrets about the outing, only about the uncertainty surrounding the cost. The following week, I noticed a couple in the same shop carrying an envelope labelled “gear” and a small checklist. They were laughing rather than haggling. It seemed like another world. Could the answer really be something wonderfully dull?
Why hobby budgeting changes how your money feels
A hobby budget does not destroy spontaneity; it safeguards it. Putting money aside for pottery clay, trail passes or independent books replaces guilt with certainty. The enjoyment remains uncomplicated because the money has already been allocated.
Picture a friend who knits. She kept adding yarn to attractive baskets until the combined cost resembled that of a modest wedding. The spending crept up unnoticed because every skein appeared inexpensive on its own. Once she set up a “Stitch Fund” with £40 going in each month, her approach changed completely. She began using the yarn she already owned, selecting higher-quality fibres and saving towards a proper class. Structure brought back the pleasure.
Money involves emotional as well as numerical calculations. Hobby expenses often come in waves-festival tickets, seasonal equipment and one-off workshops-making them seem like “surprises” despite being predictable. A small, regular fund turns those sharp peaks into manageable slopes. Your annual spending stays the same, but it gains momentum and causes fewer shocks. The budget becomes a gentle runway rather than a barrier.
How to begin hobby budgeting without losing the fun
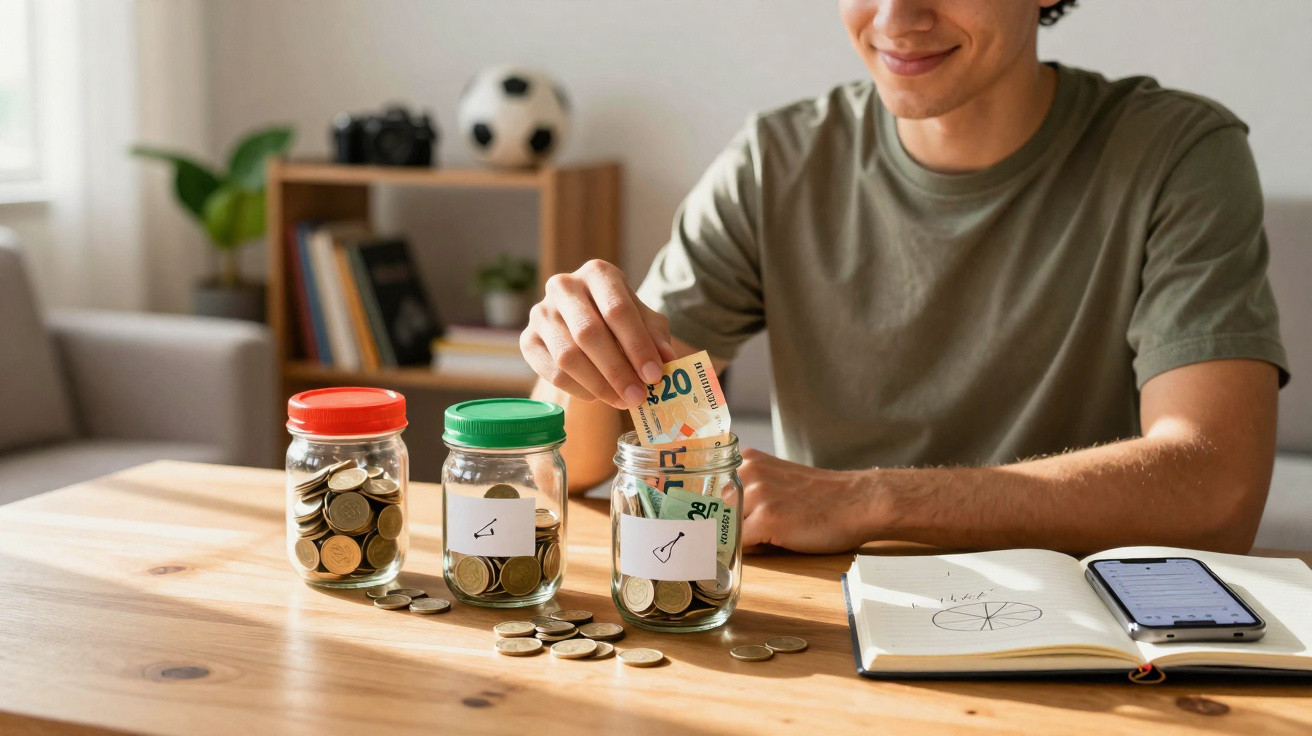
Try the three-jar approach. Jar 1 is for Essentials. Jar 2 is for Future You, including savings, a buffer and debt repayment. Jar 3 is for Joy. Put your hobby in the Joy jar, complete with its own name and figure. Begin modestly-£15 to £50 a month suits most people-then increase it after two or three cycles if the fund is continually empty. Give it the actual name of your hobby. Labels influence behaviour.
Create one straightforward rule that you can maintain: spend only from the hobby fund. If it runs low, pause or find another route-swap, borrow, repair, or sell an old board to pay for wax and fins. Let’s be honest: nobody genuinely manages that every single day. That is perfectly all right. You only need a routine that holds up during a chaotic week. In a difficult month, reduce it to a token £5 so the habit remains intact.
Follow the calendar rather than the algorithm. Prepare for larger costs-such as a festival weekend, race entry fees or a new lens-by spreading them over several months. If a camera body costs £600, save £100 monthly for six months, then buy it. Patience is a purchase as well.
“A budget is permission, not prohibition. It’s a love letter to your future weekends.”
- Set up a named fund: “Climbing Pass + Gear.”
- Arrange an automatic transfer on payday: small, consistent and non-negotiable.
- Monitor just one thing: the fund balance, rather than every receipt.
- Introduce a waiting period of 7 days for anything above £50.
- Allow one “wildcard” purchase each quarter purely for enjoyment.
Make your hobby budget personal and flexible
Most of us have experienced a hobby splurge that felt slightly secretive. Budgeting removes that secrecy. Discuss your plan with a partner or a friend who shares the hobby. Passing on a flash sale is simpler when both of you are already saving for next month’s class.
The usual pitfalls can be subtle. Avoid tracking every detail to a painful degree; simply keep an eye on the fund. Do not take up extra hobbies whenever the fund fills up; it is a budget, not a buffet. When your income is limited in certain months, sustain the habit with a symbolic amount and choose free options instead-library workshops, practice sessions or local groups. Keeping it going matters more than the amount.
Keep the approach human. Hobby money is still real money, but it should feel less heavy. Use one simple statement to look after your future self: “If it’s not in the pot, it waits.” If that feels too strict, turn it around: “If it is in the pot, spend it guilt‑free.” When circumstances change-a new job, a new baby or a new season-adjust the figure without making a fuss. Budgets are living documents.
Once you find your rhythm, a hobby budget pays for more than possessions. It provides uninterrupted afternoons and fewer arguments about money. It gives you focus. You may find yourself choosing better equipment, buying fewer duplicates and taking more lessons. Thoughtful small financial decisions improve your skills faster than impulse purchases ever will.
Use this five-minute monthly check-in. Open your hobby fund and note its balance. Then ask yourself three questions: did I enjoy my most recent purchase, what do I genuinely want next, and which dates are approaching? After that, choose one micro-goal-sell one unused item, book one class or save for one ticket. Show progress in the fund name: “Kayak Fund – £85 and rising.”
In some months you will splurge; in others, you will save cash like a squirrel. Both choices are valid. The aim is to create an agreement with yourself that you can honour. Your hobby does not need to fund itself. It simply needs to stop catching you off guard. The change is not only financial-it also affects how you step into your weekend.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Name the fund | Give your hobby a labelled fund with a set monthly amount | Changes unclear spending into a defined, guilt-free plan |
| Plan for the peaks | Spread larger costs, including events and equipment, across several months | Eases cash flow and prevents “surprise” charges |
| One measure | Track only the fund balance and the next date or item | Keeps the system simple enough that you will use it |
FAQ:
- What amount should I set aside for a hobby? Begin with 1–3% of your take-home pay, or a fixed £15–£50. Adjust it after two or three months according to how you use it and any upcoming dates.
- What happens if I have several hobbies? Make one Joy fund and divide it by season. For instance, use “Boarding” in winter and “Garden” in spring. Rotate them instead of funding every hobby at the same time.
- Should I give up a hobby when money is tight? Reduce it rather than abandoning it. Keep a token amount to maintain the routine, and move to lower-cost options such as practice sessions, community groups and libraries.
- How can I stop impulse purchases? Add a 7-day pause for anything over £50, and ensure it comes from the hobby fund. If you lose interest, the money stays put. If you still want it, you will be prepared.
- Does this create too much admin? Automate it. Schedule an automatic transfer on payday and review the fund once a month. That is all. The excitement should come from the hobby, not the spreadsheet.
Comments
No comments yet. Be the first to comment!
Leave a Comment