
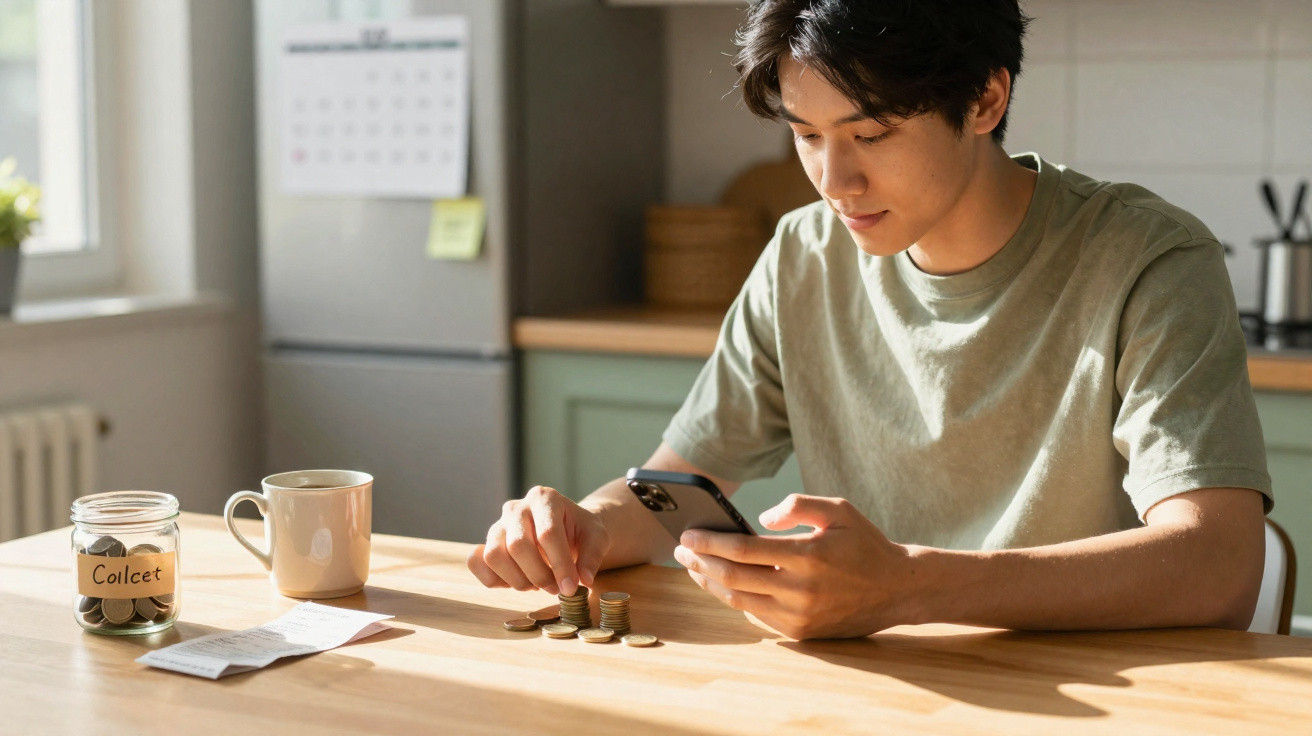
The coffee shop was already buzzing when Maya checked her banking app and grimaced. One more “small” expense. One more “just this once”. Her oat latte was going cold on the table as she reviewed the month: ride-hailing trips, takeaways and a few late-night purchases she could hardly recall. Every entry seemed insignificant on its own. Put together, they felt weighty.
She was not short of money. She was exhausted - exhausted by the feeling that her money was driving the car while she simply sat in the passenger seat.
As she shut the app, one calm question broke through the noise.
What if the real issue was not the major costs at all?
Why tiny daily choices feel bigger than your pay packet
Most people assume financial confidence comes from the major things: their salary, rent or mortgage, and the pension they keep promising themselves they will “sort out later”. But everyday stress rarely comes from the mortgage. It comes from buying a sandwich despite having food at home.
These tiny decisions affect our trust in ourselves. Whenever we spend from habit rather than intention, there is a slight jolt: “Why did I do that again?” One regret may appear harmless, but the moments soon accumulate.
Eventually, it is not only your budget you question. You begin to question yourself.
Review the past three days of spending - not the whole month, only three days. You are likely to spot the same categories appearing repeatedly: coffee, snacks, speedy deliveries and small “treats” after a difficult day. By themselves, none appears to be a problem.
A 2023 survey by a major US bank found that almost 60% of people underestimated their “small” everyday costs by at least 30%. The difference between what we believe we spend and what we truly spend has a subtle effect. It weakens that quiet feeling of “I’ve got this”.
You are left with a constant, low-level hum of budget anxiety.
The principle is straightforward. Money confidence is not solely about the amount you have; it is also about the level of control you feel over how you use it. Everyday spending decisions are like financial repetitions at the gym. Each one is a small vote: “I act with intention” or “I act on autopilot”.
When most of those votes are for autopilot, even a reasonable income can feel unstable. You cannot tell where your money is going, so you cannot rely on your future self to manage larger decisions.
Reverse that pattern and something meaningful happens. Once even 30% of your everyday spending is deliberate, your brain begins collecting proof for a new belief: “I can change this”.
Turning everyday spending into quiet confidence
One of the easiest ways to change the balance is a practice some financial planners call the “24-hour window”. It is not a budgeting app or a spreadsheet; it is simply a short daily routine. Before going to bed, note down every single thing you spent money on that day. Pen, paper, honesty.
No judgement. No colour-coding. Just a list and a total.
Keep it up for seven days and something unexpected happens. Patterns you had not noticed become clear: second coffees you do not even like, delivery charges that cost more than the meal, and subscriptions hiding in the background. That visibility by itself can build quiet confidence.
The most common error people make when they “get serious” about money is taking an all-or-nothing approach. They remove every treat, feel pleased with themselves for four days, then bounce back with a huge online purchase or an expensive evening out. The shame afterwards can hurt more than the spending itself.
A gentler strategy is more effective. Choose only one daily category to test for a week - perhaps takeaway lunches or late-night scrolling purchases. You are not forbidding it forever. You are only asking: “What happens if I reduce this by half?”
If you slip up, do not abandon the whole experiment. Curiosity is better than self-criticism every time.
i spent £140 this month “just making bad days feel a bit better”, and that sentence alone changed how I see my money.
- Record your spending once each day rather than once a month.
- Select one “habit spend” to monitor for seven days - nothing else.
- Make a small rule, such as one takeaway coffee a day, not three.
- Acknowledge every day you stick to your own rule, even when the sum is small.
- Put one share of what you save towards the dull essentials and another towards something that feels truly enjoyable.
From small choices to a different story about yourself
What is truly at stake is not merely a healthier bank balance. It is the private story you tell yourself each time you tap your card. Are you someone who “can’t stick to anything”, or someone who learns, adapts and tries again tomorrow?
Everyday spending is where that story plays out. It is where your values meet your impulses. If those two are always in conflict, money will continue to feel like a problem you have not yet solved.
Change only a few of those daily decisions and the voice in your head starts to sound different. Opening your banking app feels less daunting. You begin to trust that you could deal with an emergency or save for a major goal, without having to turn into somebody else. To be honest, nobody manages this perfectly every day.
What counts is not perfection. It is the gradually strengthening sense that your decisions and your future are finally working together.
| Key point | Detail | Value for the reader |
|---|---|---|
| Track days, not decades | Make daily spending notes rather than relying on vague monthly estimates | Creates a clear view of where money really goes |
| Change one habit at a time | Concentrate on one category, such as coffee, delivery or impulse purchases | Keeps progress realistic and emotionally sustainable |
| Link choices to identity | Treat every small decision as evidence of self-trust | Builds long-term financial confidence without requiring a higher income |
FAQ:
- Question 1 How many “little” purchases a day are too many?
- Question 2 Do I have to cut all non-essential spending to feel in control?
- Question 3 What if my income is low and daily choices feel pointless?
- Question 4 Is using budgeting apps enough to fix my spending habits?
- Question 5 How long before these small changes actually boost my confidence?
Comments
No comments yet. Be the first to comment!
Leave a Comment