
On a wet Tuesday evening, not a single chair is free. The audience is largely women in their forties, fifties and sixties, with a handful of men among them. At the rear of the room, a toddler sleeps in a buggy.
A message in blue pen fills the whiteboard: “Survivor benefits – what happens next?” As a benefits adviser attempts to untangle fresh reviews, longstanding regulations and unexpected letters arriving at people’s homes, the room listens intently.
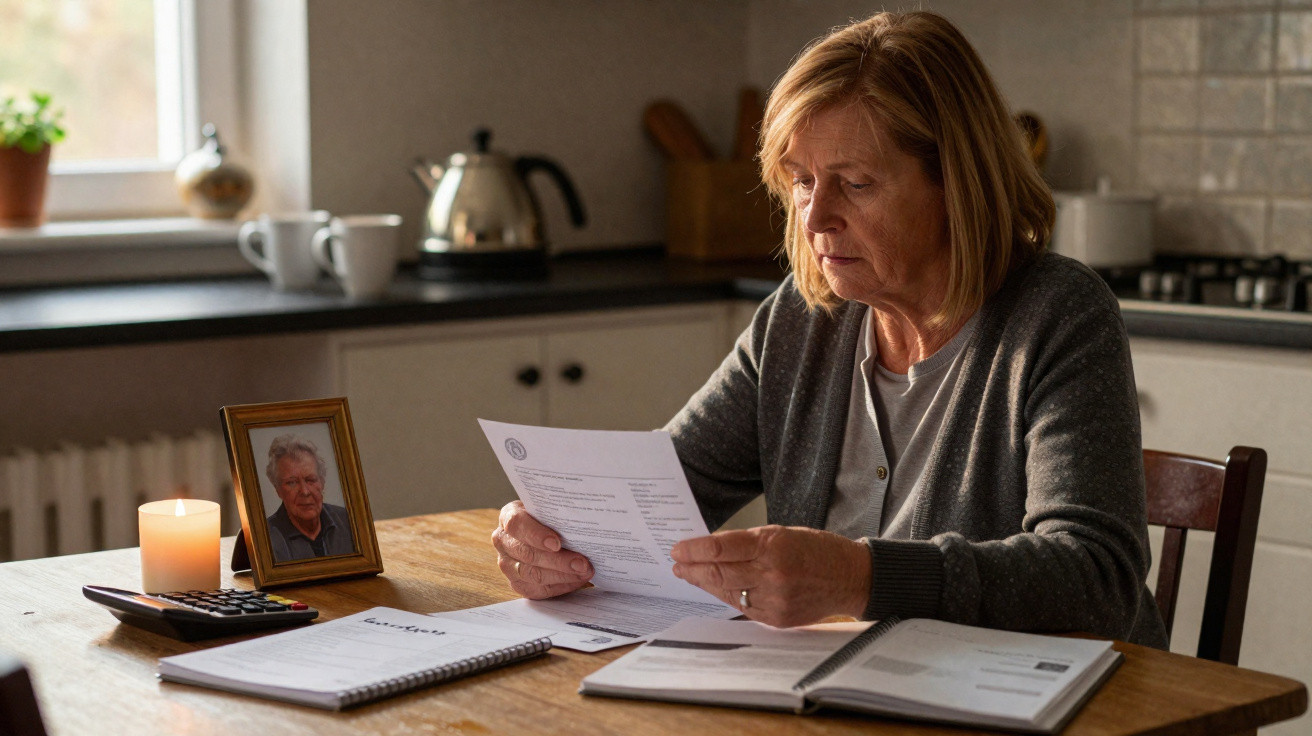
One woman grips a battered folder on her knees, crammed with correspondence from the DWP and a pension provider. “I buried my husband six months ago,” she whispers. “Now I’m scared to open the post.”
Nobody there is entirely certain what support they can still claim. That uncertainty is where the real story begins.
Widows confronting the figures, and figures confronting them
On paper, survivor benefits in the UK appear straightforward: financial help after the death of a partner. In practice, they involve a confusing mix of former schemes, current rules and low-profile policy reviews, which many households encounter only at the hardest point in their lives.
Anxieties are increasing because some benefits are being reviewed, recalculated or gradually moved into replacement systems. Widows and widowers report longer telephone calls, more complicated letters and the appearance of the word “overpayment” where they had expected reassurance.
At a time of online accounts and automated verification, the difference between the support people expect and the money that reaches their bank account is widening. Grief offers no guide to navigating it.
Consider Sarah, 49, from Birmingham. Her husband spent 30 years working on the railways and contributed to an occupational pension that pledged assistance for his “surviving spouse”. When he died suddenly from a heart attack, that wording became her lifeline.
Initially, her widow’s pension arrived as she had anticipated. Later, a letter referred to a “routine review” and a “potential adjustment”. Her monthly payment fell by almost £180 overnight. There was no straightforward explanation, only citations of scheme rules and indexation.
Her mortgage payments were fixed, but her council tax was not, while her energy bills had already become overdue. She began missing meals so that her teenage son could retain his football subscription. “It felt like he died twice,” she says. “Once in hospital, and once again in my bank account.”
Cases such as Sarah’s are not unusual. They generally stay out of the headlines until the amounts involved become impossible to overlook.
Beneath the distress is a complex policy landscape. Survivor benefits can be drawn from several places: the State Pension system; means-tested help including Universal Credit and Bereavement Support Payment; and workplace or private pensions, each with its own detailed conditions.
Every source applies separate eligibility criteria, including age, marital status, the date of death, contribution records, whether the couple were married or in a civil partnership, and sometimes even the precise date on which a pension scheme altered its terms.
Government departments face pressure to resolve “historic anomalies” and curb expenditure. As a result, previous entitlements are being examined, recalculated and, in certain instances, disputed. For people still processing their loss, it can seem as though the rules are changing beneath them.
The reasoning may appear neat on a Whitehall spreadsheet. In households around the UK, it can feel like a wager families never chose to make.
Survivor benefits in the UK: creating stability amid changing rules
For anyone concerned about survivor benefits in the UK, one especially useful measure is to assemble a personal “survivor file” before a crisis occurs. It need not be an immaculate ring binder with colour-coded dividers; it simply needs to hold all the relevant information in one place.
Include National Insurance numbers, pension scheme names and reference numbers, copies of benefit award notices, plus the original death certificate or certified copies. Add login details for online pension dashboards and provider accounts, even if they are seldom used.
Preparing for bereavement while everyday life continues can feel morbid. However, if a review letter arrives, this file prevents a frantic search through drawers at an already distressing time. Rather than making guesses during a phone call, you can reply calmly with the facts to hand.
After a partner’s death, most people function on autopilot. There are funerals to arrange, forms to complete, children needing their evening meal and a dog that still needs walking. Contesting a decision by the DWP or a pension scheme can feel beyond reach.
That human reality explains why many accept the first amount offered, even if it does not seem right. They are exhausted, bereaved and often worried about being viewed as “difficult”. Let’s be honest: nobody truly reads every page of every pension leaflet before a tragedy.
Nevertheless, support exists through a quiet network: welfare rights advisers at local authorities, charities such as Citizens Advice, bereavement helplines, and specialist organisations for police, military or NHS widows. Many will examine letters line by line without charge, identifying errors or entitlements that may have been missed.
“I thought it was just me who didn’t understand,” says Mark, 57, whose wife died after a long illness. “Once the adviser explained the letter in plain English, I realised the system was confused, not me.”
What should someone do when a review letter arrives through the door?
- Check the dates closely: identify the period under review and when payments could change.
- Ring the number provided in the letter, while recording the name of the person spoken to and the time of the call.
- Request a written explanation showing how the revised amount was worked out.
- Speak to a free advice service before accepting a substantial cut or repaying an “overpayment”.
- Retain every letter, including those that appear repetitive or insignificant.
Advisers consistently make one point: staying silent is seldom helpful. Raising questions does not place you on a blacklist. It produces a paper trail, and that record can have genuine financial value in survivor benefits disputes.
Grief, finances and the quiet politics of survivor support
An uneasy reality lies at the centre of this issue: survivor benefits have never been solely about compassion. They also reflect politics, public budgets and changing views on what families should provide for one another compared with what the state should provide.
Current reviews are taking place in a Britain where life expectancy, gender roles and employment patterns differ greatly from those of the period in which many schemes were created. Fewer people remain married for their whole lives. More women hold pensions in their own right. Same-sex couples now have legal recognition that was unavailable a few decades ago.
Governments and pension providers therefore ask who should now qualify as a “survivor”, and how long support should continue. Every technical alteration affects a real person.
For widows and widowers, the emotional context is immediate and painful. In practical terms, the death of a partner can remove a second income, or the principal income, overnight. It may also mean the loss of informal childcare, unpaid caring support or the person who always managed the household finances.
Often, one member of a couple holds the mental picture of their pensions and benefits. When that person dies, their knowledge goes with them. On a difficult day, a DWP letter can resemble an exam for which you never prepared, written in a language you do not fully understand.
At a societal level, an older promise is being renegotiated before our eyes: the belief that if you contributed, your partner would be cared for. For decades, that assumption underpinned millions of wages and pension contributions.
That promise is now being redrafted through acronyms and small-print notes. Some describe the process as modernisation, while others see it as a broken deal. In either case, households are left covering the shortfall through part-time work, overdrafts and silent anxiety at the supermarket till.
More personally, survivor benefits make us consider what security ought to mean when the worst happens. Should it be a single payment, a temporary bridge or lifelong protection? There is no simple response, and no two experiences match.
In many British homes, open conversations about death and money remain uncomfortable. Yet those who manage best when reviews begin are often people who had at least one candid, if awkward, discussion before tragedy occurred.
Grief cannot be reduced to a neat spreadsheet; life does not work that way. In that quiet community hall in Leeds, it is clear that people are not seeking perfection. They want clarity, dignity and a fair opportunity to plan for the years they never expected to live alone.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Survivor benefits under review | State and workplace entitlements are being recalculated and checked | Anticipate possible changes to your income and prepare documents |
| Complex, layered system | State Pension, Bereavement Support, Universal Credit and pension schemes all interact | Understand why letters can look confusing and when to seek advice |
| Practical coping steps | Create a survivor file, record calls, get independent advice before accepting cuts | Concrete actions to protect yourself from avoidable losses |
FAQ
- What exactly are “survivor benefits” in the UK? They are payments or pensions provided to a spouse, civil partner or, in some cases, dependent children after someone dies. They usually come from the State Pension system, Bereavement Support Payment or workplace/private pensions.
- Why are survivor benefits being reviewed right now? Government departments and pension schemes are examining historic entitlements, bringing old rules into line with new ones and seeking to reduce mistakes and long-term costs.
- Can my widow’s or widower’s pension really be reduced after it’s been awarded? Yes. A provider or the DWP can reassess and reduce payments if it considers that there has been an error, a rule change or a misunderstanding of eligibility, although you have the right to challenge the decision.
- What should I do if I get a letter about an “overpayment”? Do not ignore it or rush to make a repayment. Request a complete written calculation, keep copies of all documents and consult a free welfare rights adviser or Citizens Advice before accepting any arrangement.
- Is there any help for people who aren’t legally married but lived together? Some schemes acknowledge long-term cohabitation, but many still require marriage or a civil partnership. Check the regulations for each pension and seek advice from a specialist, as case law continues to develop.
Comments
No comments yet. Be the first to comment!
Leave a Comment