
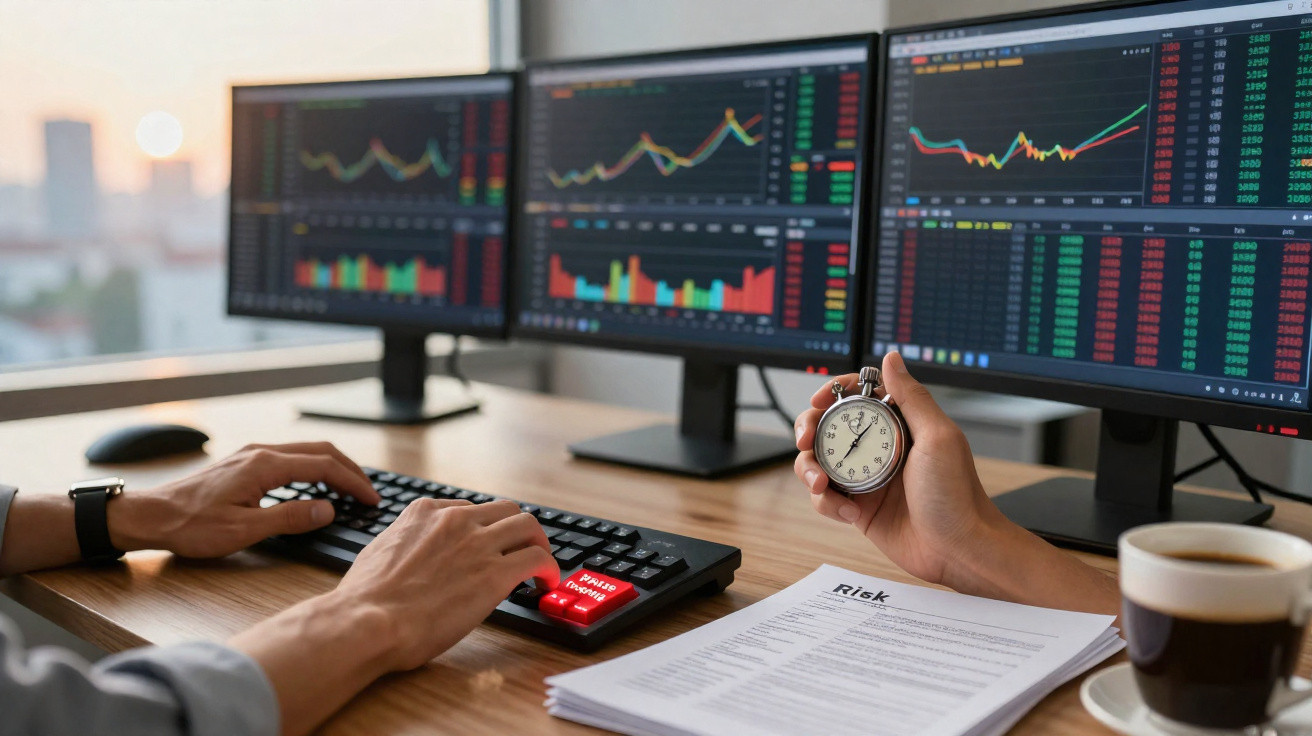
Screens flicker, orders stream through, and charts quiver like a frantic electrocardiogram. On Wall Street, in London and in Singapore, billions change hands without anyone physically working a keyboard. Markets no longer move to the tempo of human decisions; they follow lines of code running continuously, day after day.
At times, events unfold so quickly that even the people who built these machines cannot fully grasp what is happening.
It begins as a wash of colour across trading-floor displays. A junior trader in a hoodie rather than a suit looks up from his coffee, then suddenly goes still. Prices are flashing in patterns that no longer appear “normal”. It resembles a video game somebody has set to fast-forward more than it resembles a market.
No one nearby is yelling into telephones as they do in old films. Instead, most people are watching dashboards, where graphs change dozens of times every second and algorithms fight silent, unseen battles against other algorithms.
A risk-monitor warning turns red. Orders are being filled too rapidly for his eyes to track. He moves towards the mouse, pauses, and opens a log of the trading bots. It records hundreds of tiny decisions each second: buy here, sell there, cancel that order, switch to another venue.
He understands the reasoning behind them. He even helped to test one of these models. Yet, as he watches the disorder spill across the screen, he recognises something that makes his skin crawl.
The market now operates at a pace that human supervision can only follow, never direct.
Somewhere in a server rack, software is making choices faster than anybody can properly review them. The unsettling truth is straightforward.
Once the process begins, nobody truly has their hands on the wheel.
When high-frequency trading moves faster than you can blink
Imagine a share rising 3%, falling 4%, then recovering again in the space of a breath. Before a human trader can decide how to respond, the chance - or the threat - has disappeared. High-frequency trading (HFT) systems function within this narrow window of microseconds, where human thought is simply too slow.
What was once a trading day filled with individual decisions has become millions of machine-made micro-decisions, woven together into a market that acts like a living, twitching organism.
On 6 May 2010, US markets went through what is now known as the “Flash Crash”. Over only 36 minutes, the Dow Jones fell by almost 1,000 points, wiping out roughly a trillion dollars in value, before rebounding nearly as fast.
Investigators later linked some of the turmoil to algorithmic and high-frequency trading, as bots intensified one another’s actions in a feedback loop that nobody completely controlled. This was not a Hollywood-style collapse, but a chain reaction in which code did precisely what it had been instructed to do - at inhuman speed.
Such episodes are more than market curiosities. They reveal a structural change: financial systems no longer pause for people to think. HFT firms install servers in, or beside, exchange data centres to cut microseconds from latency. Some have even built specialist fibre and microwave connections solely to be a fraction of a millisecond ahead of competitors travelling between Chicago and New York.
At that pace, supervision becomes something viewed in the rear-view mirror. People establish the rules and the safeguards, then observe their own systems working in a timescale they cannot inhabit directly. The market remains designed by humans, but it no longer runs at a human pace.
Keeping human control in a machine-run market
One practical method used to slow the process enough for human judgement to matter is the use of “circuit breakers” and speed bumps. Exchanges may stop trading in a share when its price moves too sharply, or introduce tiny processing delays - such as 350 microseconds - before orders are handled.
That may sound absurdly brief, but in HFT terms it is equivalent to hitting the brakes hard. It makes algorithms operate with slightly more friction, reducing the danger posed by dense cascades of orders when they start to behave erratically.
Regulators and risk teams also depend heavily on pre-trade risk checks and kill switches. These mechanisms can restrict the amount an algorithm may buy or sell, or shut it down completely when its behaviour falls outside a set pattern.
Let us be honest: no one genuinely does this every day for every line of deployed code, however rigorous the official message may be. In practice, substantial trust is placed in backtesting, simulations and the hope that tomorrow’s market will resemble yesterday’s closely enough.
Many people take pride in the technology’s capabilities, while quietly worrying about what cannot be seen in real time. As one quant told me over coffee in Canary Wharf:
“We build these systems, we validate them, we stress-test them. Then live markets put them in situations we never imagined - at speeds we’ll never fully ‘see’ with our own eyes.”
To cope with this, some firms are creating “human-in-the-loop” oversight teams, bringing developers, traders and risk managers together in one room. Others are spending heavily on real-time anomaly detection, using dashboards that raise the alarm when patterns appear genuinely alien.
Within this new ecosystem, several rules for survival are beginning to emerge:
- Cap the amount any one algorithm may trade before requiring a manual review.
- Hold “circuit-breaker drills” so that teams understand how to respond under pressure.
- Describe in plain language what every algorithm is intended to do - rather than documenting it only in code.
- Re-run past crises regularly to assess how today’s bots would behave in those situations.
Living with markets that no longer wait for us
There is something strange about watching a market move so fast that it becomes a blur. On a mobile screen, a price chart merely seems a little more jagged and a little more alive. Behind that twitching line, however, an entire ecosystem of machines is placing, cancelling and reshaping orders before you can even scroll down the page.
Most of us have refreshed an investing app and thought, “How did it move that much while I was just making coffee?” Now multiply that sensation until billions are in motion.
For ordinary investors, this does not mean that every aspect of the table is unfairly stacked against them. Long-term strategies still rely chiefly on fundamentals, rather than on who removed three microseconds from a connection. But a deeper change is under way: markets increasingly feel less like a conversation between people.
Instead, it can seem as though we establish the opening conditions, watch algorithms communicate through speed and probability, and then attempt to interpret the echo.
The paradox is clear. HFT can add liquidity, tighten spreads, and lower costs, making trading appear smoother at the surface. Yet those very same systems may create sudden areas of instability, with prices swinging more rapidly than any person can respond.
We are balancing the genuine advantages of speed against the equally real risks of handing too much authority to code that never sleeps, doubts or blinks.
There is no simple switch to turn this on or off. Slowing everything would undermine innovation and efficiency. Allowing the race for speed to continue unchecked brings its own quiet, systemic threats. The central issue, then, is not whether high-frequency trading should be permitted or banned outright.
The real issue is whether we are prepared to improve our ethics, rules and oversight as quickly as we improve our servers.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Algorithm speed | Decisions are made in microseconds, far beyond human capability | Understand why markets can sometimes appear “disconnected” from human common sense |
| Systemic risks | Flash crashes, feedback loops between algorithms and chain reactions | Assess the potential effect on savings, investments and overall stability |
| Emerging safeguards | Circuit breakers, kill switches and real-time oversight teams | See how the sector is trying to retain human control over ultra-fast systems |
FAQ:
- What exactly is high-frequency trading? It is a type of automated trading in which algorithms place, amend and cancel orders in microseconds, seeking to profit from minute price differences at huge scale.
- Are markets still safe for individual investors? For long-term investors, the main risks still relate more to company fundamentals and diversification than to HFT, although short-term price movements may feel more extreme.
- Can regulators really control ultra-fast algorithms? They can establish rules, enforce circuit breakers and require risk controls, but complete real-time “control” is impossible when decisions occur millions of times each second.
- Do banks and funds fully understand their own algorithms? They understand the systems’ design and objectives, but live markets can produce edge cases and bot-to-bot interactions that no backtest can fully predict.
- Will markets eventually run almost entirely without humans? Execution is already extensively automated, but people still set the objectives, rules and strategies - the unresolved question is how long that human layer will remain genuinely in charge.
Comments
No comments yet. Be the first to comment!
Leave a Comment