
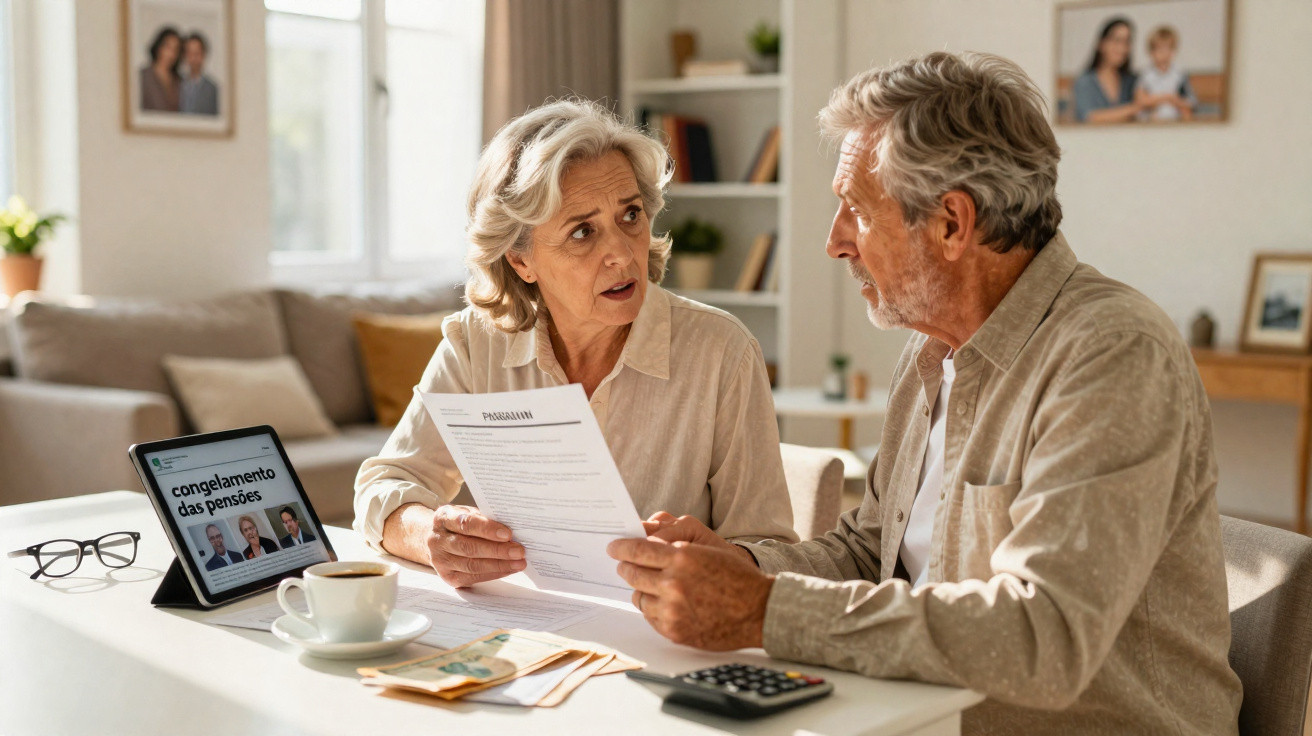
“Hands off our pensions”, “We paid in. You pay out.” A retired engineer in a flat cap attempts to tell a baffled teenager recording on his phone why he has abruptly lost hundreds of pounds each month. His voice breaks as he says: “I worked for this my whole life.”
A couple walking past pauses to read a placard saying “freezing pensions for the wealthy”, then simply shrugs. “They’re well off anyway,” the man says as they move on. That brief remark hurts almost as much as the policy itself. Beneath headlines about “rich retirees” are people asking themselves whether they have suddenly been cast as the villains in somebody else’s crisis narrative.
And nobody appears fully certain where fairness stops and punishment starts.
The shock of being told you’ve had “enough”
For years, saving for retirement was presented as the responsible adult choice. Work diligently, forgo treats, add more to your pension, and you would eventually thank yourself. Many of today’s “wealthy retirees” followed those instructions to the letter. They worked late, made additional workplace pension contributions and turned down costly holidays while their children were young.
Then a blunt letter from the Government arrives, telling them that their state pension will be frozen because their private pension pot is considered “high enough”. What once seemed like sensible planning can, overnight, feel like a punishment. The implied message is painful: you have done too well, so you no longer qualify.
Spend five minutes at a local coffee morning and the same account emerges in a range of accents. Tom, 71, a former electrician, spent four decades scaling frozen ladders and squeezing through roof spaces. “I never earned a banker’s bonus,” he laughs, “I just didn’t blow it all on cars.” He worked overtime, contributed to his company scheme and eventually retired on what he believed was a modest yet secure income.
Since the pension freeze announcement, his annual budget has become hundreds of pounds tighter. His council tax has increased, his energy bill has risen once more, and one of the few reliable income streams in his life has now been locked. “I’m not asking for a yacht,” he says, tapping the table. “I’m asking for what I was told I’d get.” His anger is not performative; it is subdued, lingering in the gaps between his words.
Governments say the sums no longer work. Life expectancy is higher, the proportion of workers to retirees is falling, and public finances are under strain. Focusing on “wealthy pensioners”, they argue, is a rational response. Why should someone with a six-figure private pension pot receive a full, inflation-linked state pension when hospitals and schools face pressure?
That reasoning looks straightforward on paper. In reality, it clashes with a more fundamental promise: that the state pension is earned rather than a favour that can be removed once someone passes an arbitrary threshold. Those thresholds are complicated. There are widows rich in property but short of cash, small business owners who invested everything in their companies, and people who inherited a home without inheriting money in the bank. A spreadsheet cannot interpret those lives.
How retirees are adapting to a pension freeze - and where it can go wrong
For many affected retirees, the first response is to take a notebook and rigorously redraw their monthly budget. They examine everything, from streaming subscriptions and supermarket brands to insurance policies that have renewed automatically for years. One modest but effective approach is to make a straightforward three-column list: must keep, flexible, can cut.
The must-keep column contains essentials such as rent or council tax, utilities and medication. Flexible spending may include meals out, gifts and travel. The can-cut section often reveals unexpected items: unused warranties, gym subscriptions for joints that have not encountered a treadmill in years, or charity direct debits that gradually increased. It will not reverse the freeze, but the exercise can return a degree of control to people who feel blindsided.
Many older savers are also taking more from private pensions or savings earlier than planned to fill the shortfall, without always recognising the longer-term danger. Withdrawing more now may reduce the pot more quickly than inflation, creating a genuine cliff edge in ten or fifteen years. Others make a hurried decision to downsize, selling the family home under emotional strain before discovering that the replacement property carries unforeseen costs and higher service charges.
The more significant blow is often emotional. People who spent their lives working hard rarely welcome the prospect of seeking independent financial advice or asking their adult children to help pay energy bills. Public discussion, meanwhile, too easily falls into simplistic categories: “boomers” against “generation rent”, wealthy pensioners against young families under pressure. Such labels overlook the uncomfortable fact that many grandparents already quietly support their children and grandchildren.
Some retirees are beginning to resist in a more organised way. Local pensioner groups circulate templates for disputing means-testing decisions and checking whether a person has mistakenly been classified as “wealthy”. Online forums exchange plain, direct scripts for speaking to MPs. One retired headteacher compared it to organising staff rooms again - only with greater stakes and no pay for the hours involved.
“They keep calling us ‘wealthy’ on TV,” says Margaret, 74, who spent her career in the NHS. “I don’t feel wealthy when I’m choosing between visiting my sister or fixing the boiler. Wealthy people don’t have to make those choices.”
That energy is becoming small but practical action:
- Sending brief, personal letters to local representatives rather than signing copy-and-paste petitions
- Joining together to obtain group discounts on legal or financial advice
- Making written records of every official telephone call concerning pension changes
None of this is glamorous. It involves administration, persistence and a refusal to let a policy label define the work of an entire lifetime.
The larger question nobody wants to answer directly
Behind the calculations and formulas is a more troubling issue: what do we owe people who did precisely what they were encouraged to do? Save more, remain independent and avoid relying on the state - that was the script given to a whole generation. For many, freezing their pensions because they followed that script feels like a betrayal of trust, not merely a budgetary decision.
This is why the words “I worked for this my whole life” carry such force. They are not only about money, but about identity: decades of rising in the dark, bringing up children, caring for parents and paying tax through recessions and booms. When all those years are reduced to a means-tested label - “wealthy, so frozen” - something profoundly human is lost.
You need not support every angry placard outside Parliament to recognise the tension. Younger workers already struggling with rent and student debt see comfortable retirees and question why they should continue funding benefits for people who own their homes outright. Older people recall double-digit mortgage rates, widespread redundancies and factories closing without warning. Each side brings its own wounds to the debate.
There is also a subdued anxiety: if pensions can be frozen for one group today, what prevents the rules changing again in ten years? The agreement between the state and its citizens begins to resemble a moving target. Once that sense of security unravels, people act differently: they save less, trust less and vote more angrily.
Perhaps that is why pension discussions, normally so dry, now spark around dinner tables. Between mouthfuls of Sunday roast, grandparents explain the triple lock to teenagers. Adult children place letters from the Department for Work and Pensions in front of their parents and ask: “Is this right?” On good days, families combine their knowledge and become better informed together.
On bad days, resentment rises. “You had it easy.” “You have no idea what it’s like now.” Both sides contain elements of truth and exaggeration. Somewhere within that complicated space lies the real question: how can we divide the cost of an ageing society without setting generations against one another? Let us be honest: nobody really does that every day, but these difficult conversations may matter more than we realise.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Rule changes | Freezing or reducing the state pension for retirees considered “wealthy” | Understand why some retirement incomes fall despite years of contributions |
| Real-world impact | A reduced annual budget, difficult spending choices and increased family tension | Recognise these situations and anticipate the practical effects on everyday life |
| Room for action | Reviewing spending, joining forces, requesting written explanations and seeking independent advice | Identify practical steps to regain some control when pensions are frozen |
FAQ
- Why are pensions for “wealthy” retirees being frozen? Governments say they must limit spending as the population ages and budgets come under pressure. Directing the policy at retirees with larger private pensions or assets is presented as a way to preserve support for lower-income people and finance services such as healthcare.
- If my pension is frozen, does “wealthy” mean I am rich? Not necessarily. Thresholds commonly use income, savings and property values, so someone may look comfortable on paper while still facing rising living costs, debt or family obligations.
- Can I dispute a decision to freeze my pension? In many circumstances, yes. You can ask for a review, request a detailed explanation of how your status was assessed and provide updated information about your finances or health. Support from a pension advice charity or financial adviser can make a meaningful difference.
- What can I do to protect myself if the rules continue changing? Spreading income across state pension, workplace or private schemes, and accessible savings can reduce dependence on a single set of rules. Retaining personal contribution records and official letters is also useful if you later need to challenge a decision.
- What should families do if a parent’s pension is frozen? Begin with a calm, fact-based discussion. Work through the revised monthly budget together, check for missed benefits or tax reliefs, and speak honestly about any support the family may be able to provide. On a personal level, listening without judgement matters just as much as the figures.
Comments
No comments yet. Be the first to comment!
Leave a Comment