
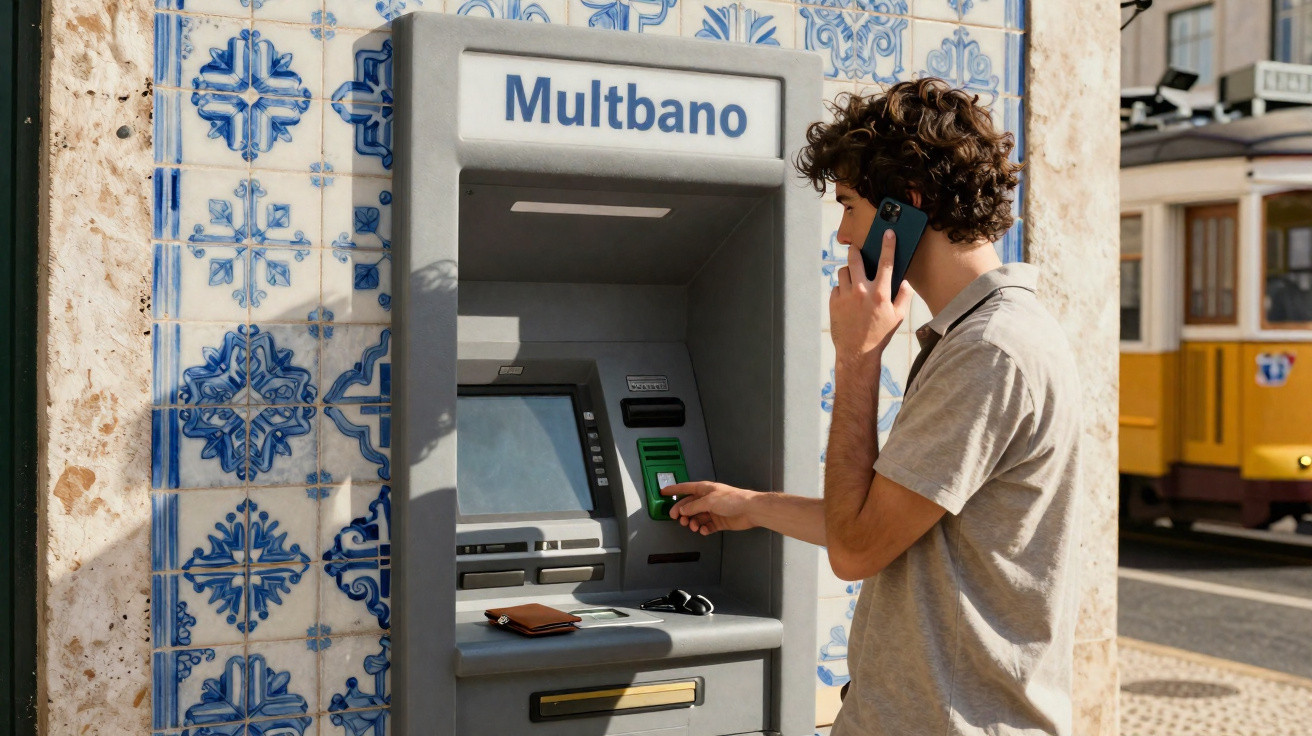
The display flickers. The mechanical hum cuts out. Your card is not returned.
For a moment, you remain with your hand held out, as though the machine might simply be taking its time - or being awkward. Then the people behind you edge forwards, somebody exhales loudly, and the small camera over the keypad feels suddenly watchful. Has the machine taken your cash as well? Could somebody in a nearby parked car be waiting for you to panic and leave?
You press the cancel key. Nothing happens.
The woman behind you tilts her head, attempting to read the screen without appearing intrusive. You mutter, “It’s eaten my card,” as though voicing it might prompt the ATM to spit it out. Your thoughts race towards the worst possibilities: fraud warnings, a locked account, and an uncomfortable late-night call to your bank’s call centre.
The ATM remains silent.
Some cash machines return a card after a minute.
This one does not.
When the ATM freezes, your mind can freeze too
Shock is usually the first response.
Many people look at the screen for longer than they notice, convinced their card may slide out if they just wait one more second. You can feel rooted in place: embarrassed to be holding up the queue, yet nervous about stepping away in case the card suddenly emerges and another person takes it. Street noise seems to disappear until your own heartbeat is all you notice.
That brief hesitation is entirely human.
It is also the point at which poor choices can creep in: leaving without taking action, hitting buttons at random, or loudly blaming the bank while your card remains inside an electronic box beyond your control. During those first 60 seconds, the real challenge is not the ATM. It is clearing your thoughts enough to choose the safest next move.
On a crowded Manchester high street, a 29-year-old nurse saw an ATM keep her card shortly after payday.
She later explained that she had already entered her PIN twice because the keypad “didn’t seem to work”. A man close by advised her to try once more, then offered to “help” by pressing the keys for her. A few minutes later, she left without her card. Within an hour, three cash withdrawals she had not made had emptied her account.
Bank investigators gave her a warning that applies quietly across the UK.
Most ATM fraud involving “captured” or “retained” cards begins in the period of confusion: the short, stressful interval between noticing that a card is stuck and responding properly. It is not the technology, nor an exceptionally advanced hack. It is people delaying, making assumptions, or trusting the wrong stranger at exactly the wrong time.
ATMs follow fairly basic rules.
They may retain a card when a session expires, when their system identifies something unusual, or when a cheap piece of plastic has been inserted into the slot to trap it. The machine does not care who you are or how worried you feel. That is alarming, but also reassuring: you cannot reason with an ATM, yet you still know which controls remain available - your bank, your phone, and your own judgement.
The reality is unforgiving.
When your card is inside that machine, treat it as lost, even if the display looks reassuring and the bank logo is familiar. Your priority must quickly change from “get my card back” to “make this useless to anyone else”. Viewed that way, the right actions become much more obvious and the panic has a practical outlet.
The safest actions in the first 10 minutes after an ATM retains your card
Begin by freezing the card while you are still at the cash machine.
Use your banking app if possible: almost every UK bank now offers a “freeze card” or “lock card” option that takes only seconds. If you do not have the app, phone the number shown on the ATM screen or printed on the back of your card - you may remember your bank’s main number better than you expect. Say: “The ATM has retained my card. I want to block it immediately.” Do not wait to find out whether it reappears. Consider it lost immediately.
Then take a small step away from the ATM while keeping it in view.
This simple movement protects you in two ways. It creates physical distance from the queue and from any apparently helpful strangers, while making it more difficult for people behind you to shoulder-surf your PIN or linger by the keypad. If you can, stand to one side with your back against a wall or shop window and hold your phone. You are not leaving the situation unattended; you are restoring a small amount of control in a setting that may suddenly feel exposed.
This is where many avoidable errors happen.
People allow embarrassment to dictate their response. They apologise to the queue, rush away, and assure themselves they will “sort it when I get home”. Or they hand control to somebody else: an unknown passer-by pressing buttons, a stranger wanting to “check something” on the card reader, or even a friend reading the balance aloud from the screen. Let’s be honest: nobody really does that every day.
That is how sensitive details are exposed: your PIN, account balance, and bank.
Once such information is available, a retained card can become an opening for more elaborate scams. The safest principle may sound harsh, but it works: no one should touch the machine or access your information except you and your bank. Disregard strangers who tell you to “try your PIN again” or “pull harder”. That is not rude; it protects your future self.
One fraud analyst I spoke to put it bluntly:
“The moment the machine holds your card, imagine a big red banner over it that says: ‘This card is now dead. Your job is to make it official before someone else pretends it’s alive.’”
After freezing or cancelling the card, you can consider the situation more clearly.
Did the ATM retain your cash as well as the card? Was an error code displayed? Those facts may be useful later. If no cash was dispensed, record the time, location, and amount on your phone. If the ATM is outside an open branch, go in and report it face to face. Otherwise, remain there long enough to report the incident through the app or by telephone.
- Freeze or cancel the card within minutes rather than hours.
- Step a little away from the ATM, but keep it in sight.
- Decline “help” from strangers, however friendly they appear.
- Note the time, location, and anything shown on the display.
- Check your account later that day for unauthorised withdrawals.
Staying protected after leaving the ATM
After you move away from the ATM’s glowing screen, the matter is not quite finished.
Your card may be blocked, but the information trail connected to that cash machine can still affect your money. The following hours call for calm attentiveness, not panic. Check your banking app again that evening and the following morning. Do not only look for large, unfamiliar withdrawals: also watch for small transactions of a few pounds, which some fraudsters use to test a stolen card before attempting more.
On an overcast Tuesday in Leeds, a 42-year-old electrician had his business debit card retained by a supermarket ATM.
He cancelled it from the car park, went home, and assumed the episode was over. Two days afterwards, several online purchases appeared: gaming credits, gift cards, and a food delivery 200 miles away. His old card information had been skimmed previously, while the “captured” card incident was only one element of the wider fraud. The bank refunded him, but the investigation disrupted his cashflow for a week.
The key lesson sits between “card gone” and “problem solved”.
Use the next few days as a period of monitoring. There is no need to become paranoid and refresh the app every five minutes, but establish a deliberate checking routine. Once in the morning and once in the evening is enough. If anything looks unusual, however minor, report it as card-related fraud and mention the ATM incident. Banks can link those details more quickly when you provide the full timeline.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Block the card immediately | Use the app or call the bank as soon as the ATM retains the card | Reduces the chance that somebody can use the card or its information |
| Keep your distance - and your information private | Move slightly away from the machine and refuse help from strangers | Protects your PIN, balance, and personal information |
| Monitor the following days | Check the account for several days for test transactions | Helps stop discreet fraud quickly before it escalates |
FAQ:
- Can the bank get my card back from the ATM? Sometimes, if it’s a branch-owned machine and you report it quickly, they can retrieve it after checks. In many cases though, the card is destroyed for security reasons and a replacement is issued.
- Should I re-enter my PIN if the machine seems stuck? No. If the transaction looks frozen or strange, cancel if you can and stop. Re-entering your PIN repeatedly makes life easier for anyone trying to skim or shoulder-surf your details.
- What if the ATM took my card and my money? Record the exact time, place, and amount, then contact your bank immediately. They can see whether the cash was actually dispensed and usually refund failed withdrawals after an investigation.
- Is it safer to only use ATMs at my own bank? Not guaranteed, but machines attached to bank branches, in well-lit, CCTV-covered areas, are generally less attractive to criminals than isolated ones on empty streets.
- Do I really need to check my account after the card is blocked? Yes. Card details can be copied before it’s captured. A quick daily scan for a few days helps you spot small “test” payments before they turn into something bigger.
Comments
No comments yet. Be the first to comment!
Leave a Comment