
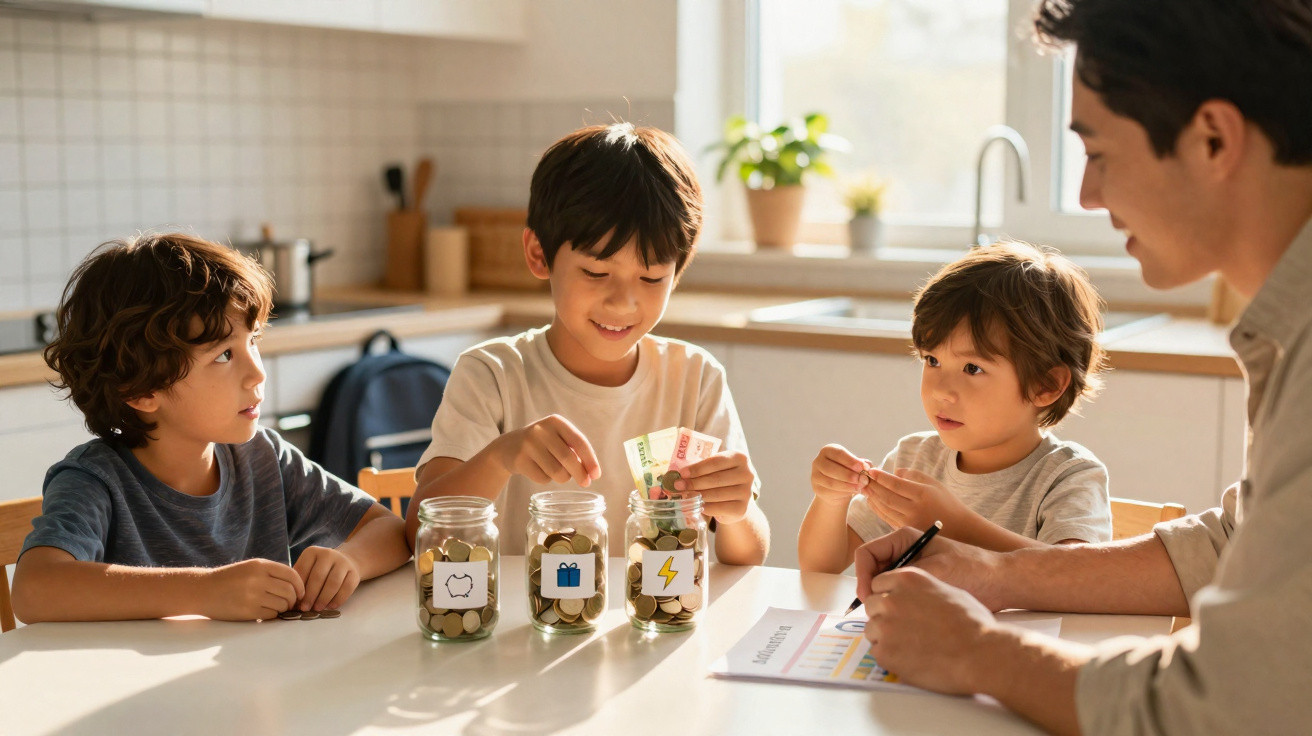
Parents discuss it quietly around the kitchen table. Children ask outright - with a shrug or an unblinking look: “So… how much do I get?” Fresh figures circulating in family group chats are higher than plenty of people expected, prompting the bigger pocket money question for 2025: what is fair, what teaches useful lessons, and what is simply excessive?
A dad works out the sums in his head, his son counts coins in his hand, and the cashier waits with the knowing smile of someone who has witnessed it countless times. Most of us have faced that instant when a child asks for “just a bit more”, while we mentally race through prices, commitments and principles in seconds.
A new study has pinged onto my phone and is ricocheting around parent chats. It reports that weekly pocket money has risen sharply, not just for teenagers but for eight-year-olds as well. The divide between what families consider “normal” and what children genuinely receive is bigger than it was last year. The figures may catch you off guard.
What is the right amount of pocket money at each age?
The study’s central finding is straightforward: pocket money is on the rise. Younger children are receiving more than they did last year, while teenagers are edging towards the sort of sums associated with part-time work. Expect single figures during the first school years, firm double figures for tweens, then another increase at 16 as travel, lunches and social lives become more expensive.
Reports from family-finance apps and bank surveys place the median at roughly the mid-to-high teens each week. The highest quarter of families give more than thirty. Location makes a difference: families in cities generally pay more, frequently pointing to bus fares and snack costs. The increase reflects rising prices, but it also coincides with children taking on paid “micro-jobs”, including pet-sitting, parcel drop-offs and online marketplace listings.
Here is a straightforward guide that many parents will recognise: ages 6–8: £4–£7 per week; ages 9–12: £8–£12; ages 13–15: £13–£20; ages 16–18: £25–£40. The research indicates that median amounts for older teenagers sit nearer the upper limit, particularly when they pay for lunches or data plans. This is not a set of rules, but a useful snapshot. What the money must cover changes what the amount means. Include lunch, and the figure needs to increase; make it purely for fun, and it can remain modest.
What pocket money figures overlook: everyday life
Statistics do not capture the Sunday-night routine. One Leeds family told me they increased their 10-year-old’s pocket money from £6 to £10 over six months. It was not an act of generosity: crisps cost £1.25, and getting the bus to football practice costs money. They agreed a new amount, put it on the fridge and decided it would cover snacks plus one small weekly treat.
Elsewhere, a 15-year-old receives a basic £15, with an extra £2 for emptying the dishwasher, £5 for mowing the lawn and a one-off £20 payment for editing Grandpa’s photo archive. The same study recorded a double-digit year-on-year increase in paid “digital chores”. It is pocket money combined with the gig economy, teenage version. He bought his own headphones, and understands exactly what earning them involved.
The reasons this rise feels substantial are easy to understand. Prices have risen, while app-based payments have replaced much of the cash, making regular transfers simpler. Teenagers spend online, meaning their entire “universe of wants” is a tap away. There has also been a change in attitude. Many parents treat pocket money as a learning tool: a way to practise budgeting before a first job. Small errors cost pennies now, rather than thousands later. Think of it as supervised practice.
How to choose an amount without constantly doubting it
Begin with a plain, consistent base and then adapt it. Use the Age × £1 rule as a weekly minimum. Adjust for local living costs: add 20% in expensive cities, or subtract 20% if you pay for most extras. For teenagers funding lunches or travel, add a separate budget for “needs” so that their spending money remains genuinely theirs. Review the arrangement annually rather than every month.
Be explicit about what the pocket money pays for. Is it snacks, friends’ gifts or subscriptions? Set out three things it covers and three it does not. Children cope better with clear rules than vague feelings. Typical pitfalls include constantly changing the terms, expecting pocket money to fund essentials and making last-minute rescue payments that remove the lesson. Realistically, nobody manages this perfectly every day. If there is a wobble, start again the following week using the same amount and the same rules.
Use a calm explanation and set a review date. Put the agreement in writing and connect it to a modest savings target. The money talk works best when it is brief and predictable.
“We don’t pay for being part of the family, we pay for extra effort. Basics are on us. Extras are on you.” - a mother of two, Brighton
- Pay for chores, not basics: Personal hygiene, homework and kindness should not become transactions.
- Set it and say it: State the amount, what it covers and the next review date.
- No rescue transfers: Natural consequences are quicker teachers than lectures.
Beyond the amount: what children learn when you loosen the reins slightly
The figures are only the entrance, not the whole house. A 7-year-old deciding between a magazine and a sticker pack discovers both limits and pride. A 12-year-old saving for boots learns the steady rhythm of patience. A 17-year-old balancing travel, food and fun encounters a miniature version of the real economy. The study’s larger amounts will fuel debate at the school gates, but the more valuable benefit lies elsewhere. When children budget their own money, they tend to argue less about yours. They also discover that decisions are part arithmetic and part emotion. That is why the best pocket money arrangement is one your child can explain. If they can describe what it covers, where it goes and what they are saving towards, you have found the sweet spot.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Age-based baseline | Begin with Age × £1 each week, then adjust ±20% for local costs | A quick, fair figure you can justify |
| Scope beats size | Decide what pocket money covers before choosing the amount | Fewer arguments and clearer habits |
| Earnable extras | Pay for “above-and-beyond” tasks to build autonomy | Motivation without turning essentials into paid work |
FAQ:
- How much for a 7-year-old? Consider £4–£7 each week when it is only for small treats. If it must cover a weekly snack or magazine, choose an amount nearer the top end.
- Should pocket money be linked to chores? Connect payments to extra effort rather than family membership. Essential chores remain non-negotiable, while paid jobs are additional.
- Cash or card? Cash is hands-on and useful for under-10s. A junior card or app can help tweens and teenagers monitor spending and save towards goals.
- What if siblings are different ages? Apply the same formula to both, then explain the difference in age. Give the younger child smaller opportunities to earn extras so they do not feel left behind.
- How often should we increase it? An annual review is effective. Choose a review month, consider prices and needs, then make changes together. Small rises are better than unpredictable top-ups.
Comments
No comments yet. Be the first to comment!
Leave a Comment