
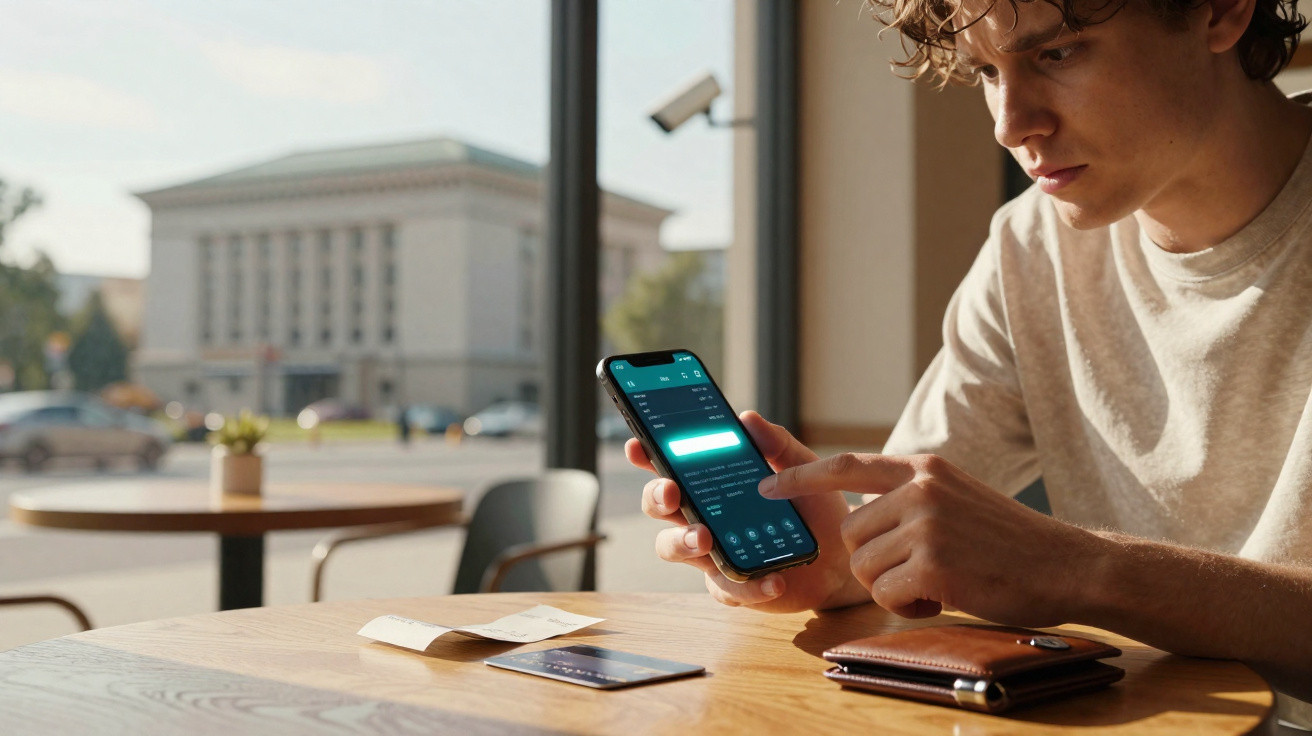
The alert sounded on my phone at 3:12 a.m., on one of those nights when sleep seems almost fictional. Its subject line read: “Security update from your bank.” Still half asleep, I opened it and saw a clean timeline displaying my ten most recent transactions: groceries, a ride-hailing trip, late-night food delivery. Below it sat a new line in small, orderly type: “Transactions are now monitored in real time in cooperation with government security programs.”
My thumb stopped above the screen.
The app was not seeking permission. It was simply telling me. A completed decision presented through a pleasant-looking interface.
Somewhere amid the coffee I bought and the rent I paid, something had quietly changed.
Most of us did not notice it happening.
When every swipe of your card becomes a data point
Look through your banking app this week and it may appear entirely unchanged. The colours, icons and comforting promises about “protecting your money” could all be familiar. Yet underneath that polished surface, a fundamental shift is under way.
Government regulators have discreetly signed off frameworks allowing financial institutions to send transaction data to central systems almost immediately after you tap your card. This is not for quarterly reporting or anonymised statistics. It is live monitoring, defended by the one word no politician wants to oppose: security.
You did not fill in a new consent form at a branch. More likely, you pressed “Accept” on a lengthy update that received barely a glance. That was enough.
Talk with people inside major banks and payment firms, and the same account emerges in hushed tones. One London compliance manager described it as “installing a fire alarm that never turns off.” Each card payment, transfer between friends and online purchase is marked, rated and categorised within milliseconds.
He highlighted the rapid expansion of “real-time transaction monitoring hubs” connected directly to government systems. Initially, they were designed to identify straightforward fraud and money laundering. Terrorist financing followed. Then sanctions. Taken separately, every extension seemed sensible.
The system is now broad enough that your €4.60 coffee enters the same flow as a questionable offshore transfer. Both feed the same insatiable machine.
On paper, the reasoning is starkly straightforward: criminals move money, money creates digital traces, therefore money should be watched in real time. Lawmakers are told this can prevent the next attack, freeze funds before they are moved and detect patterns that a person would overlook.
The problem is that patterns cannot exist without people. Your pay day, overdue rent, hospital invoice or discreet transfer to a partner your family disapproves of all become inputs for models taught to determine what “normal spending” means.
Once that idea of “normal spending” is imposed from above, anyone outside it may begin to appear high-risk. Not because they have done anything improper, but because the system has been trained to distrust difference.
How to live with a wallet that’s no longer private
Your banking app has no switch labelled “government monitoring”. That option disappeared with the legislation and the small print. What remains in your hands is the extent to which your financial life can be read by systems that know only your figures, not your circumstances.
Begin by tracing your digital money trail for a week. Include everything: card spending, subscriptions, peer-to-peer payments, instant purchases and crypto on-ramps, if you use them. You will soon spot habits that have previously gone unnoticed.
For every entry, ask one plain question: does this have to use a real-name, fully traceable rail? Certain payments clearly do, including salary, utility bills and taxes. Others may not, such as sharing cash-heavy expenses with friends or personal discretionary purchases that you would rather not have misunderstood by an algorithm searching for “unusual behaviour”.
Most of us know the feeling of having a card unexpectedly blocked while abroad because a system deemed us suspicious. Now imagine that experience extending across your whole financial life. That is the danger when monitoring shifts from targeted to universal.
A useful step is to vary how you pay. This is not about “hiding” - that idea seldom reflects reality - but about ensuring that every element of your life is not placed on one easily scanned rail. Some people maintain a small cash reserve for routine purchases. Others use separate accounts for recurring bills and personal spending, so one flagged payment cannot lock up their entire month.
In truth, no one wants to read 27 pages of amended terms at 11:37 p.m. The next best approach is to assume that when a tool is seamless and free, you and your data are often the real product.
A privacy solicitor I spoke with expressed it plainly:
“The line used to be ‘we track suspicious transactions.’ The new line is ‘we track all transactions and decide which ones are suspicious later.’ That’s a constitutional change sold as a software upgrade.”
One practical routine is creating a small, lawful and uncomplicated “low-visibility zone” in your financial life that is less exposed to continuous monitoring. This can include:
- Paying for part of your everyday local spending with cash, particularly sensitive items such as health-related purchases.
- Holding a secondary account solely for subscriptions and online trials, separate from your main income and savings activity.
- Checking your banking app’s privacy settings every quarter rather than once every five years.
- Selecting services that set out clear data-retention limits, rather than stating “we keep it as long as needed.”
- Speaking with family members or housemates about how joint accounts may be affected if one person triggers an automated review.
None of this is glamorous, and it will not undo the move towards surveillance, but it can soften its harshest effects.
The quiet cost of calling it “just security”
Official press releases offer a neat, straightforward story: real-time transaction monitoring produces safer societies. It means fewer terrorist plots, fewer victims of fraud and more efficient law enforcement. No reasonable person wants the reverse.
But human lives are seldom neat or straightforward. Money moves through embarrassment, fear, illness, love, errors, side businesses and fresh starts. When these movements become live feeds for state-backed systems, the danger is not only abuse but misunderstanding. A sharp rise in small payments could be treated as money laundering when a family is crowdfunding medical bills. A run of transfers to a new city might be flagged as evasion rather than an escape from domestic violence.
These systems seek a pattern before they seek context, if they seek context at all.
| Key point | Detail | Value for the reader |
|---|---|---|
| Real-time tracking is already here | Authorised through regulatory changes and introduced through banking app updates and back-end integrations | Helps you recognise that this is not a future possibility but a current reality affecting everyday transactions |
| You still control some of your money trail | Selective cash use, separating accounts and checking settings can reduce needless exposure | Offers practical ways to recover a portion of financial privacy without breaking any rules |
| Patterns can be misread | Automated systems often identify “risk” when life is merely complicated or unusual | Encourages you to prepare for mistakes, retain buffers and avoid panic if a payment is unexpectedly questioned |
FAQ:
- Is it legal for governments to monitor my transactions in real time? In most countries introducing these arrangements, monitoring sits within anti-terrorism, anti-fraud or anti-money-laundering legislation already approved by parliament. Its legality relies on broad “security” powers and on the fact that you have technically agreed through banking terms, even where that agreement felt invisible.
- Can I opt out of real-time tracking through my bank? With ordinary accounts, almost never. Once the framework has been approved, banks are generally legally required to operate these systems. You can, however, select institutions with stronger privacy policies and move some everyday spending to methods that are not continuously sent to central databases.
- Does using cash really change anything? Cash will not make you invisible, nor will it conceal large or suspicious activity. It does, however, keep mundane and entirely normal purchases out of a permanent, easily searchable record. That limits the raw data available to profile your habits over time.
- Should I be worried about false positives? Yes, though not to the point of paralysis. False positives already occur: frozen cards, delayed transfers and endless “source of funds” questions. More real-time scanning is likely to make them more common. An emergency buffer, separate accounts and clear evidence for large one-off payments can help you get through such moments with less disruption.
- Is there anything collective I can do beyond my own habits? Personal adjustments are useful, but the greater influence is political. Supporting civil-liberties organisations, responding to public consultations on new financial laws and demanding independent oversight of monitoring systems can all slow the shift from targeted security to blanket surveillance. Quiet roll-outs depend on public silence.
Comments
No comments yet. Be the first to comment!
Leave a Comment