
The moment things changed happened, oddly enough, in a supermarket aisle. My basket was packed with “essentials”: oat milk, scented candles, an unnecessary new notebook, and almond butter that cost more than my first mobile phone bill. My card went through, but my banking app sent a notification to my wrist at the till: “You’ve exceeded your weekly spending limit.” I laughed aloud, yet inwardly I felt a knot tighten.
Walking home, I mentally revisited each purchase and tried to defend it. Health. Comfort. Productivity. “Self-care.” But the more excuses I made, the clearer it became that I had muddled a basic distinction: what I genuinely needed and what I simply wanted.
That brief alert from my bank set off a far larger financial reset.
When “I deserve it” quietly wrecks your budget
Most of us know the point at which the delivery driver recognises us better than the people next door. In my case, it began with stressful workdays and late evenings. Feeling exhausted, I started giving myself rewards: a takeaway here, a “just this once” taxi there, and a quick online scroll that reliably ended at “Add to cart”.
Technically, I was a responsible adult earning a regular income. In practice, my money was disappearing through countless small gaps. Every one of them came wrapped in the same justification: “I need this right now.”
My proper wake-up call came one Sunday morning, when I opened my banking app with a tight feeling in my stomach. Looking back through the month, I found seven food deliveries, three subscription trials I had neglected to cancel, and a “quick browse” that had become a £90 clothes order for items I had worn only once.
Individually, none of those purchases seemed especially extreme. That was exactly the issue. Every minor want had been made to look like a need. I convinced myself I needed Ubers for safety, streaming subscriptions to unwind, and expensive coffee to “start the day right”. When I totalled them, those supposed “needs” quietly added up to another rent payment.
At that point, I saw that my issue was less about spending itself and more about how I defined it. I had been treating the word “need” as a universal permission slip. Food is necessary, but that does not mean sushi three times a week. Rest matters, but it does not automatically require retail therapy.
Once I recognised this, some of the haze disappeared. My bank balance no longer felt inexplicable. It was simply mirroring the stories I kept repeating about the things I “couldn’t live without”.
The small mental shift that changed everything
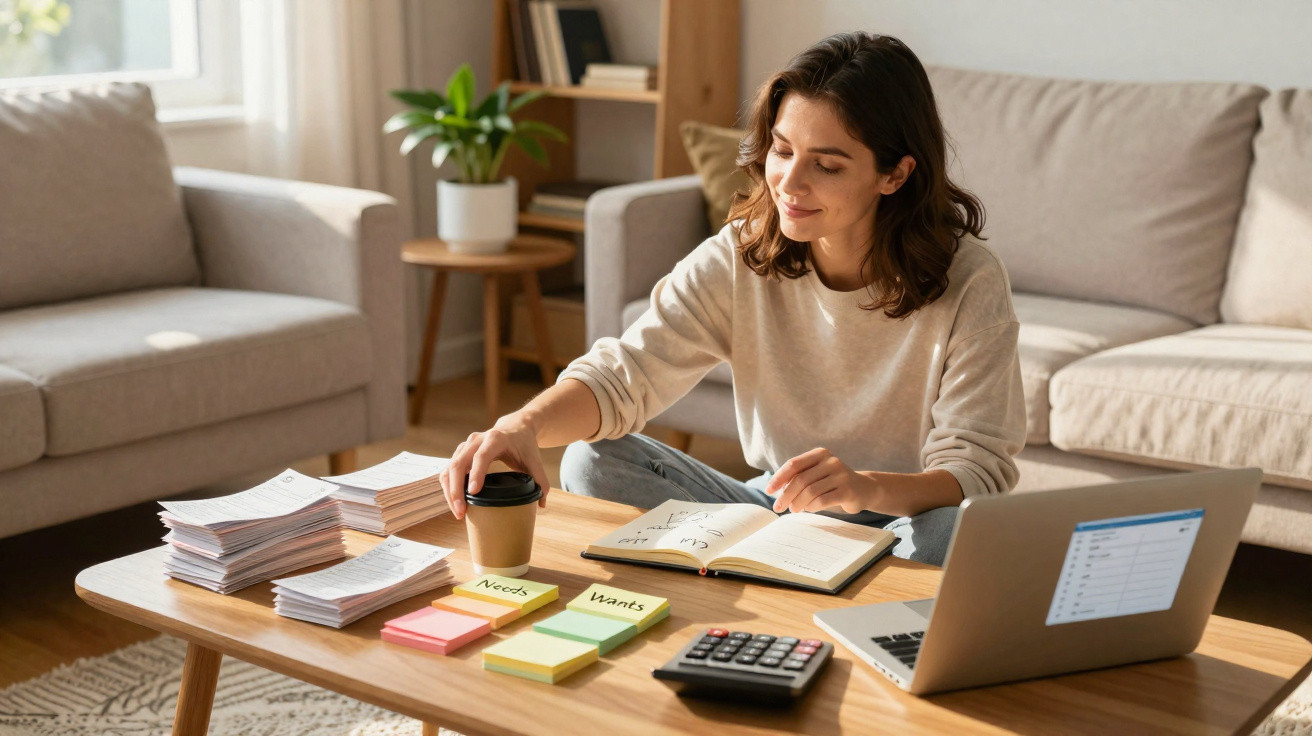
My first practical move was almost comically straightforward: in my phone’s Notes app, I wrote my own definitions of “need” and “want”. Needs included housing, basic food, utilities, transport to work, health, and one inexpensive form of relaxation. Wants covered anything beyond being “functional” and into the realm of “nice to have”.
Next, I introduced one small and rather nerdy habit. Before paying for anything non-essential, I stopped and said, “Need or want?” aloud. It was not meant as a criticism; I was merely identifying it. That two-second pause interrupted my automatic spending and created a little distance from the urge.
What surprised me was not the amount I stopped spending. It was how frequently I still picked the want - deliberately. I continued to order pizza on some Fridays, but I would say, “This is a want, and I’m choosing it.” That small piece of honesty prevented the guilt spiral that used to follow.
Realistically, nobody manages this perfectly every day. I forgot, slipped up and made impulse purchases. Even so, the overall pattern changed. The stretch between payday and panic day gradually became longer. I was not exactly wealthier; I was simply less bewildered.
After that, I tracked one particular measure each week: the number of times I had called a want a need. Those revealed my vulnerable areas. Mine were food and transport. I “needed” a taxi because I was tired, or I “needed” an expensive brunch because I had not seen my friends.
The plain truth is that money clarity doesn’t come from a fancy budget template, it comes from calling things by their real name. Once I was truthful about that, I could make plans accordingly. I began intentionally allowing for some wants in my budget, rather than permitting them to secretly take it over.
Practical ways to redraw your line between needs and wants
One method that immediately made a difference was the “bare-bones budget” exercise. I opened a blank spreadsheet and asked myself: if my income fell by half tomorrow, which costs would I unquestionably continue paying? Rent, basic groceries, electricity, my phone, public transport and minimum debt repayments. That became my real “needs” column.
Everything else went into the “nice-to-have” category, even when it bruised my ego. That included my gym membership, new clothes, takeaways, subscriptions, gifts and digital courses. I did not remove all of them, but I stopped pretending they were something else.
Then, like a school project, I colour-coded my bank statement. Green marked needs. Yellow marked wants that genuinely brought joy. Red highlighted purchases that made me think, “I don’t even remember buying this”. Seeing those red entries irritated me enough to make changes.
If you do this yourself, be kind to yourself. Shame destroys progress more quickly than any unwise purchase. Wanting comfort and convenience does not make you foolish; it makes you human. The aim is not to remove all wants, but to prevent them from disguising themselves as needs and draining your future savings without you noticing.
I also began relying on a straightforward rule whenever I paused over the “Buy now” button:
“Will Future Me be grateful I bought this, or just grateful I survived this month?”
If the honest answer was “neither”, the item went back on the shelf.
At roughly the same time, I wrote a short “pre-check” list and attached it to the back of my debit card:
- Have I already covered my true needs this month?
- Is this purchase a want I’ll still care about in two weeks?
- Am I buying this to solve a feeling, not a problem?
- Can I afford this without touching savings or going into overdraft?
- Could I wait 24 hours and see if I still want it?
That small set of questions came between me and plenty of regret. It did not prevent joy; it simply screened out the noise.
What changed when my needs and wants finally made sense
Redefining needs versus wants did not make me a minimalist saint. I still have a soft spot for quality coffee and second-hand books. What shifted was the constant background noise in my mind. The quiet anxiety that arrived whenever a bill came through gave way to something calmer and more secure.
Rather than wondering, “Where did my money go?”, I could identify it: my needs were paid for, my important wants were intentional, and a small but persistent amount remained for savings. Financial clarity, I discovered, was less about achieving perfection and more about finally being able to read the map.
The most surprising change was emotional as much as financial. Once I quit describing wants as “needs”, I also stopped behaving as though I was a permanent emergency. After every difficult day, I no longer had to “rescue” myself through random spending.
I could tolerate discomfort for longer, decide when to spend, and allow a feeling to pass without acting on it. That gap between feeling and buying is where real control lives. When you redraw that boundary for yourself, money ceases to be a blur and becomes a tool again. That is where real freedom quietly starts.
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify true needs | List only the expenses you’d keep if your income were cut in half | Gives a solid baseline for non-negotiable spending |
| Label each purchase | Ask “Need or want?” before paying, and track the answer | Reduces impulse buys and financial guilt |
| Create a simple pre-check | Use 3–5 questions before clicking “Buy now” | Builds a practical habit that protects your budget long term |
FAQ:
How do I know if something is really a need?
Ask: “If my income dropped tomorrow, would I still pay for this before anything else?” If the answer is no, it’s a want, even if it feels essential right now.Is it bad to spend money on wants?
Not at all. Wants are part of a good life. The problem starts when wants are paid for before needs, or when you pretend they’re essential and end up in debt because of them.What if my “needs” are already more than my income?
That’s a harsh place to be, but it’s real for many people. Start by checking if any “needs” are actually upgrade versions (premium phone plans, luxury groceries) and see where you can scale down without risking your safety or health.How often should I review my needs versus wants?
Once every few months is enough for most people, or whenever your life changes: new job, move, relationship shift, debt paid off. Your definitions evolve as your reality does.Can redefining needs and wants really improve my savings?
Yes, because you’re not just cutting costs, you’re changing decisions. Even a few reclassified purchases a month can free up money for an emergency fund, debt repayment, or something you genuinely care about.
Comments
No comments yet. Be the first to comment!
Leave a Comment