
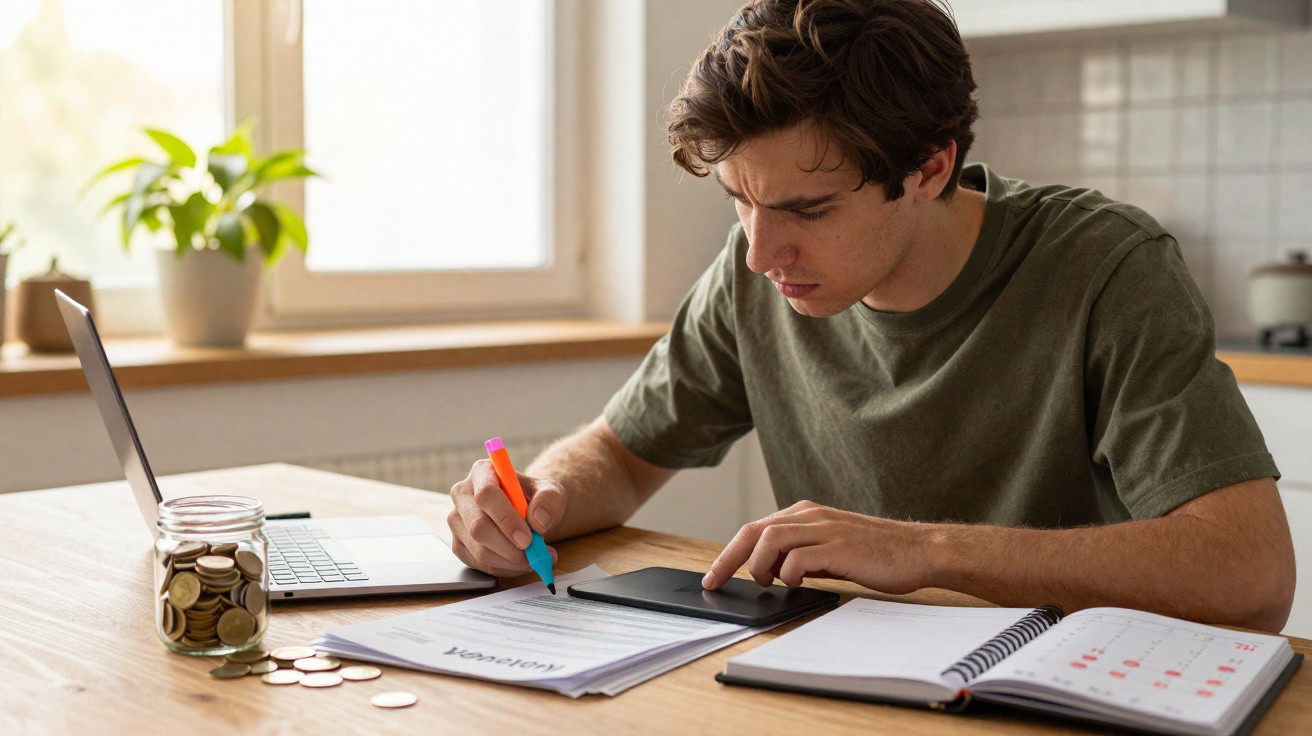
Bank statements, health insurance letters and a message from her pension provider lie unopened. Meanwhile, her phone keeps flashing with Instagram reels, while the envelopes remain on the table, carrying their quiet weight of guilt.
She tells herself she will “deal with money stuff” when life becomes calmer. When work eases up. When she finally “feels ready.”
Then the dishwasher signals, the group chat erupts, Netflix starts another episode automatically, and the envelopes end up in a drawer. Hidden away. Forgotten.
On the face of it, everything remains the same. The rent is paid. Her card continues to work.
Yet beneath that surface, something gradual and costly is taking place - and most people do not realise the bill is building.
The silent price of “I’ll deal with it later”
Financial procrastination is seldom dramatic. There is no spectacular crash or clear moment when things break. It is closer to a small leak behind a wall, steadily damaging the building while life still appears “fine” from the sofa.
We create reassuring stories for ourselves: “I’m just bad with numbers.” “I’ll start saving when I earn more.” “Retirement is so far away anyway.” Every story brings a little emotional relief while taking away a little financial freedom. Since nothing awful happens today, we persuade ourselves that we have escaped the consequences.
What many people fail to see is that delaying money decisions does more than postpone them. It puts you on a default route. Choosing nothing is still a choice - and it will usually favour your bank, lender or simple random chance more than it favours you.
Consider the unseen damage created by “I’ll sort it later.” A US survey from 2023 found that 35% of people had no retirement savings whatsoever. This was not necessarily a deliberate choice; it was often because nothing ever properly began.
Speak to somebody in their late 50s who put off investing from their 30s onwards, and they often recount the same cycle: unclear good intentions, short spells of action, then months or years of avoidance. Before they know it, they are calculating how long they can keep working and what they might sell, rather than considering how soon they could step back and breathe.
There are everyday costs too. Failing to cancel an old subscription. Never changing energy providers. Allowing credit card balances to linger rather than planning how to clear them. Individually, they seem too minor to matter. Collectively, they quietly consume hundreds, and sometimes thousands, every year.
The concealed price is not limited to lost money. It also includes opportunities that never materialise. Starting late means missing out on compounding. Avoiding a plan can leave you stuck in a job you dislike because you cannot afford to take a risk. Refusing to face the figures creates a persistent, low-level anxiety that drains energy from everything else.
There is a reason your future self can seem like somebody you barely know. Our brains tend to discount both future pain and future pleasure. That is why scrolling can feel easier than reading your pension statement. One offers a small dopamine boost; the other holds up a mirror you would rather avoid.
Financial procrastination is often disguised as a packed schedule or the belief that “I don’t understand this stuff.” Beneath that, however, there is usually something more subdued: fear of feeling foolish, fear of finding bad news, or fear of admitting that we have waited too long. We protect our ego in the present and leave the cost to a future version of ourselves with less time and fewer choices.
Turning the ship: small acts that beat delay
The encouraging news is that you do not need a flawless plan or a six-figure income to stop paying the procrastination tax. You need one practical, specific action that you repeat. Not ten actions. Just one.
Begin with a 20-minute weekly “money check-in”. Put your phone on aeroplane mode. Take one sheet of paper. The only aim is to note what is coming in, what is going out and what debt is outstanding. Nothing more. No spreadsheets, apps or colour coding required.
When that becomes routine, introduce one further step: perhaps round up card purchases into savings, overpay your smallest debt by £10, or finally open that workplace pension email. Small actions, repeated over time, are more effective than ambitious plans that never move beyond your thoughts.
This is where many people stall: they wait to feel clear before taking action. They look for the perfect budget, the magical investment or the “right time”. Life does not send calendar invitations for that moment. It simply carries on.
To be honest, nobody truly does all of this every day. People who appear “good with money” generally have one or two unexciting systems running automatically. They use a direct debit to move money into savings on payday. They follow a rule that splits every pay rise between enjoyment and the future. They review bills annually rather than once every decade.
The simple truth is that the longer you avoid your figures, the more costly your comfort becomes. You also spend more emotional energy trying not to think about them.
One of the greatest hidden costs is that your brain starts connecting money with shame and confusion. That is why you can suddenly “feel tired” when it is time to review bank statements. Your brain is attempting to shield you from discomfort by steering your attention elsewhere.
As a result, people make familiar and deeply human errors. They look at their accounts only when something has already gone wrong. They keep debt because “everyone has some.” They remain loyal to banks or providers that barely know they exist. They view financial admin as a personality test rather than a collection of skills that anyone can develop.
We have all known that moment when we promise that Future You will be wiser, wealthier and more disciplined than the person you are now. The emotional framing is reassuring: you are not avoiding things, you are simply “waiting for the right phase of life.” The hidden cost is that this ideal Future You never arrives unless Present You takes one irritatingly small, practical step.
“Money doesn’t solve all problems, but avoiding money problems makes almost everything else easier,” a financial coach told me. “Most of my clients aren’t lazy or irresponsible. They’re overwhelmed, ashamed, and convinced they’re uniquely bad at this. Once they see the numbers and take one action, the spell breaks.”
Across dozens of conversations with advisers and ordinary people, the same easy, high-impact actions appear repeatedly:
- Arrange an automatic transfer into a savings or investment account for the day after payday.
- Write down every subscription and cancel at least one this week.
- Contact one provider - internet, phone or insurance - and request a better deal.
- Choose the smallest debt and make a straightforward plan to clear it.
- Open your pension/retirement account once and check your contribution rate.
Every action is small. The real shift is emotional: instead of merely reacting to money, you begin quietly directing it. Once you experience that first small measure of control, the pull of procrastination begins to weaken.
Choosing your future bill
The unusual thing about financial procrastination is that no outside force makes you stop. There is no traffic light, examination deadline or manager chasing you. You can drift for years while the world continues as though nothing has changed.
That is why it is so quietly harmful. The person who truly feels the consequences is you, later on: the version of you who may want to move to another city, change career, work less or simply sleep at night without calculating bills in the dark. Delayed action sends all those dreams an invoice.
You do not have to overhaul your financial life this week. You only need to cut the hidden cost by 1%. Open the envelope. Look at the balance. Ask the “stupid” question. Tell a friend that you are finally examining your figures, so you do not retreat from it.
Your money story is not permanently defined by what you failed to do at 25, 35 or 50. It is shaped by the next small choice you make when you would normally say “I’ll deal with it later.”
The real question is not “Am I behind?” It is “What is procrastination quietly charging me right now - in cash, in choices, in peace of mind - and what’s the smallest move that starts lowering that bill?”
| Key point | Detail | Value for the reader |
|---|---|---|
| Procrastination creates a default path | Failing to decide about savings, debt or retirement still produces results | Helps readers recognise inaction as an active and costly choice |
| Small systems outperform big intentions | Automatic transfers, annual bill reviews and small debt overpayments | Offers realistic, low-effort actions anyone can begin this week |
| Emotional barriers are normal | Shame, fear and overwhelm lie behind most financial delay | Lessens guilt and makes change feel human rather than heroic |
FAQ:
- Question 1 How do I begin if my finances feel completely overwhelming?
- Answer 1 Set a 20-minute timer and use a sheet of paper. List your accounts, approximate balances and debts. Do not judge or fix anything; simply make it visible. You cannot change what you refuse to see.
- Question 2 Is it too late to repair years of financial procrastination?
- Answer 2 It may be late, but it is not pointless. Concentrate on what you can influence now: the order in which you clear debts, spending leaks, and automatic saving or investing. People have turned things around in their 40s, 50s and even 60s through consistency rather than perfection.
- Question 3 Which single habit makes the greatest difference?
- Answer 3 A weekly money review. Spend 20–30 minutes checking accounts, paying one bill or changing one small thing. This routine interrupts the avoidance cycle and makes money feel routine rather than like a crisis.
- Question 4 How can I stop feeling ashamed about my money mistakes?
- Answer 4 Keep your self-worth separate from your bank balance. Money is a skill, not a personality trait. Discuss it with one trusted person or adviser. Shame grows in silence and becomes smaller when you say, “Here’s where I’m at, and I’m changing it.”
- Question 5 Do I need a financial adviser to get unstuck?
- Answer 5 Not necessarily. Advisers can assist with complicated matters, but many people’s first gains are basic: monitoring spending, automating savings and tackling high-interest debt. If you do seek help, ask how they are paid and what they actually do for you.
Comments
No comments yet. Be the first to comment!
Leave a Comment