
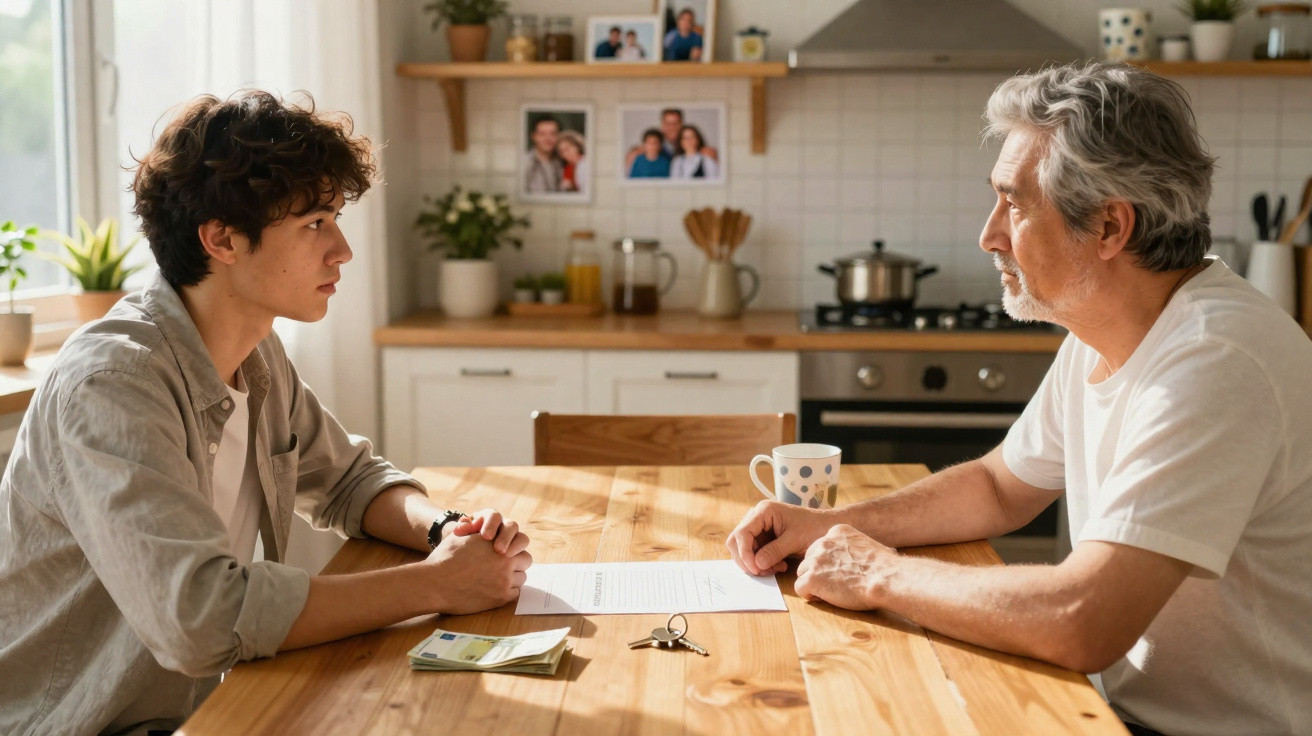
On the surface, the Martins are “comfortable”. They have two incomes, an outright-owned suburban home and a garden whose apple tree droops with fruit. But on the final Sunday of each month, they gather around the kitchen table with strained expressions to discuss rent. Not their own rent, but their daughter’s. At 25, she is back in the bedroom she had as a child, paying €450 each month to stay in the home where she was raised.
Her father describes it as “teaching responsibility”.
Her mother says it “feels like charging rent on memories”.
Their daughter simply says: “I’m paying less than my friends; it’s only fair.”
The fridge is stocked and the bank balance appears healthy. Still, the mood at home has the sharp sound of shattered glass.
No one can agree any longer on the meaning of “fair”.
When the family home becomes a business arrangement
A peculiar quiet often falls over a household when grown-up children return home. Crockery clatters, doors close with a little more force, and the Wi-Fi password becomes ammunition. Initially, everyone calls the arrangement “temporary”: a supportive break while their child gets work, recovers after a split or gets away from a dreadful rental market.
Then somebody says the loaded word: rent.
It is no longer a token payment towards food shopping, but a monthly bank transfer. The sum has three, perhaps even four, digits. The family WhatsApp group becomes an Excel spreadsheet. Before long, the house that hosted birthday parties and witnessed tears over exams begins to resemble a co-living property run by Booking.com.
Speak to enough people and you will hear countless versions of this same situation. In London, Alex, 28, has a respectable job in tech but pays his parents £700 every month for the compact loft room that used to be covered in football posters. His parents, both former teachers, explain that the money contributes towards soaring energy costs and council tax.
In Madrid, 23-year-old Lucia studies while working part-time. Her parents ask her for €200, then discreetly place it in a savings account in her name. She does not know this yet. They want to surprise her with a deposit for her first flat.
There is a harsher side too. On TikTok and Reddit, adult children describe being charged “rent” that consumes nearly their entire wage, while their parents buy new SUVs and upload cruise pictures to Instagram.
The divide between generations is no longer merely about musical tastes. It concerns the definition of money, housing and independence. To parents who came of age when one salary could buy a flat, asking for rent may seem like a natural part of “real life”. To children facing student loans and unattainable housing markets, the calculation can feel merciless.
They are expected to behave as self-sufficient adults in a world that does not provide adult-level security.
For that reason, a conversation about “rent” carries far more than euros or dollars. It brings old sacrifices, unspoken bitterness, childhood hurt and a private fear shared by both sides: what happens if love now has a price tag?
When fairness turns into emotional debt
It is possible to discuss rent at home without it blowing up in everyone’s face. It begins with one straightforward question at the kitchen table: what is this payment actually for? Is it meant to meet genuine household costs? To encourage financial responsibility? To be secretly saved for the child’s future? Or is it filling gaps created by years of low pay and growing expenses?
Bringing that question into the open changes the entire discussion. Rent of €300 spent on groceries is different from €300 placed in a protected savings account. Parents who have the means sometimes adopt a middle ground: a small symbolic payment alongside an automatic transfer into a “future deposit” account. The arrangement is clear to everyone, leaving nobody to make assumptions.
The greatest danger is using rent as punishment in disguise. “You want to act like an adult? Then pay like one.” That line can feel gratifying at the time, particularly after years of sacrifice for a child’s education or lifestyle. Yet it turns money into a moral scorecard.
Let’s be honest: nobody really does this every single day.
Families frequently move between guilt and resentment. One month, they charge rent “out of principle”. The following month, they waive it because their child is struggling, only to harbour quiet resentment afterwards. The emotional cost grows heavier than the financial one. Openness about earnings, real expenses and expectations may be uncomfortable, but it is still far better than vague resentment.
One mother I interviewed, 54-year-old Karen from Birmingham, summed it up bluntly:
“Asking my son for rent wasn’t about money at first. It was about me feeling taken for granted. Then I realised, that’s not a rent problem. That’s a boundaries problem.”
Eventually, she altered the way she handled it. Rather than increasing the sum whenever she felt cross, she set a fixed amount and presented it as a “household contribution”, nothing more and nothing less.
That distinction is important. “Rent” has a chilly, legal, contractual feel. A contribution implies a shared home and shared expenses. Even the language used at the table can reduce the sting and prevent the living room from feeling like a landlord’s office.
Charging rent to adult children without damaging relationships
If you choose to charge your adult child rent, a useful practical starting point is percentages rather than instinct. Many financial planners recommend requesting 10–25% of the child’s net income, according to your circumstances. Use a lower percentage where their work is insecure or they are still studying, and a higher one if they have a stable full-time role.
Put the arrangement in writing together. Literally. Stick a simple sheet of paper on the fridge containing three lines: “Income, Contribution, What this money covers.” It becomes less about who loves whom most and more about a joint budget. It works even better when each party understands the freedom it brings: the parent receives help with household bills, while the child has the dignity of not feeling like a long-term guest.
One frequent error is copying what friends or relatives do. “Your cousin pays €600 at home, so you should too.” Such comparisons can wound when salaries, cities and rental costs are entirely different. Another pitfall is setting a figure above the cost of renting a room elsewhere simply “because you can”. That reverses the emotional logic. Home ceases to feel safe and becomes the town’s priciest hostel.
There is an opposite extreme as well: parents declining any money because of pride or duty, then privately exhausting themselves by paying for everything. Eventually, generosity can turn into concealed bitterness. You supported your child, while nobody supported you. That is a genuine story, but it need not become the only one.
At times, the most restorative thing is to voice what normally remains lodged in the throat.
“My daughter told me, ‘If I pay rent, am I still your child or just a tenant?’ That broke me. We sat down, cried a bit, and agreed: you’re my child first. The money is just logistics.”
To preserve that emotional reality, some families follow a few straightforward safeguards:
- Agree a specific review date, every 6 or 12 months, so the amount does not become a surprise battle.
- Do not change the rent in response to an argument or a lifestyle decision.
- Maintain at least one ritual with “no-money” attached: Sunday lunch, a walk or a television programme watched together.
- Explain openly what the contribution enables: paying the heating, retiring sooner or building emergency savings.
- If you are secretly putting the money aside for them, tell them eventually. Emotional honesty lasts better than any financial plan.
Money is measurable. Respect has to be said aloud.
Rich on paper, poor in trust: what the rent debate exposes
The argument about rent points to a wider divide. Many parents are “asset rich” but “cash poor”: they own a home, perhaps even another property, while their monthly finances are squeezed by energy bills, food prices and taxes. Their children are often the reverse: more adaptable and better educated, but burdened by insecure employment and impossible housing costs.
So when a parent says, “It’s only fair that you contribute,” they may be speaking about survival as much as principles. When a child responds, “I’m living on crumbs while you’re sitting on a house worth half a million,” they are not necessarily being ungrateful. They are highlighting an economic system that has made family homes investment products rather than safe harbours.
Some households are creating fresh arrangements in the gaps left by that system. They charge a modest rent and use some of it to fund therapy when tension builds. They agree that rent stops automatically if the child loses their job. They bring siblings into the discussion so that nobody feels either favoured or used.
Other families decide that their home will never operate through invoices. There is no rent and no contribution, only the expectation that the support might one day flow the other way, with children caring for ageing parents. That approach can work too, provided it is a choice rather than an imposed silence or a sacrifice steeped in guilt. In each case, the central question remains the same: how can people share what they have without losing who they are to each other?
There is no single rule that works for every postcode, income or childhood history. Charging rent at home is neither inherently cruel nor inherently wise. It is a tool. In some homes, it is a ladder that helps a young adult move towards independence. In others, it becomes a cage, signalling that love now arrives with a monthly invoice.
Perhaps the real task, then, is being willing to speak early and honestly, before resentment becomes fixed. Saying, “Here’s what I can give. Here’s what I need. Here’s what scares me.” Parents can acknowledge their money worries. Children can admit that paying rent feels diminishing in the bedroom where they once slept with soft toys. Between “living on crumbs” and being “rich on paper”, families are quietly redefining what home means.
| Key point | Detail | Value for the reader |
|---|---|---|
| Make the purpose of rent clear | Establish whether it pays expenses, teaches responsibility or creates savings | Limits conflict by connecting money to shared aims |
| Set transparent, fair amounts | Base contributions on a percentage of income rather than comparison or anger | Allows both sides to feel respected and less exploited |
| Put the relationship first | Agree rules, review dates and no-money moments together | Protects trust and emotional safety within the family home |
FAQ:
- Do parents always need to charge adult children rent? No. The answer depends on income, housing expenses, culture and emotional history. Some families benefit from an explicit contribution, while others work better with non-financial help or support returned later in life.
- What level of rent is reasonable at home? A typical range is 10–25% of the child’s net income, with adjustments for local housing costs and whether they are studying, seeking work or in full-time employment.
- Can paying rent at home postpone independence? Not always. For many people, making a moderate payment while saving the remainder brings independence sooner than spending their whole wage on a market-rate studio flat.
- What happens if siblings face different rent arrangements? Different treatment can be fair when it is clearly explained, such as for different incomes, studies or disabilities, but secrecy creates jealousy. A calm family discussion generally matters more than absolute equality.
- How can you raise the subject without causing an argument? Choose a neutral time rather than the middle of a row. Begin with numbers and needs, then discuss feelings. Presenting it as “How can we organise things so everyone feels okay?” helps to lower the temperature.


Comments
No comments yet. Be the first to comment!
Leave a Comment