
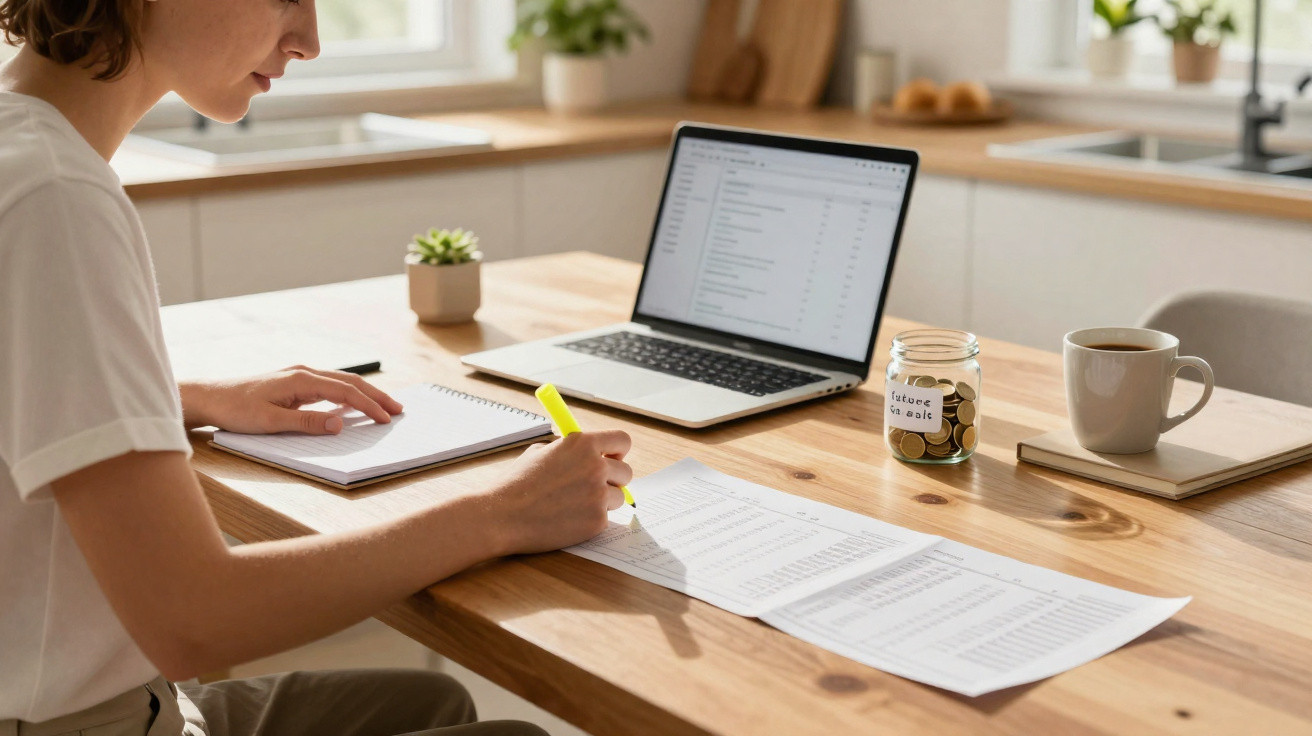
The first time I printed out five years’ worth of bank statements, the stack seemed innocuous. It was simply a neat pile of paper on my kitchen table, beside a partly finished coffee and a phone vibrating with alerts. I assumed I would scan a handful of entries, mark a few figures, then carry on with my day. Straightforward, wasn’t it?
Yet, as I moved through the PDF and turned the sheets, subtle trends started to surface. Identical retailer names. Repeated dates. The same “tiny” sums, which stopped seeming tiny when arranged in one lengthy, accusatory list.
Between 2019 and 2024, my money had been slipping away without much fuss.
What surprised me was not the destination of it.
It was what those transactions revealed about the life I believed I was leading.
The invisible spending that shapes your life
The first discovery was the regularity of my supposedly “one-off” purchases. That spontaneous takeaway delivery on a Tuesday evening? It appeared on nearly every Tuesday. The “emergency” Uber journeys I claimed hardly ever happened? They were almost a recurring subscription. Without recognising it, I had made boredom, stress and convenience into fixed budget items.
Reading those statements felt oddly personal, rather like opening an old diary I had no memory of writing. Each transaction represented a small choice I had since forgotten, although my bank had retained every one. The figures were ruthlessly impartial, and that impartiality hurt.
One particular entry felt like a personal rebuke: coffee. Not the enjoyable “let’s catch up” coffee with a friend, but the fast, solitary card tap between meetings. £3.20 here, £4.10 there. Sometimes twice in one day. During one otherwise ordinary month in 2021, I found 42 individual coffee purchases. Forty-two.
Once I totalled them, the amount exceeded my monthly electricity bill. Over a year, I had spent enough on takeaway coffee to fund a short break: flights, three nights in a respectable hotel and perhaps even a hire car. Instead, it had vanished into disposable cups and frothy milk I barely recalled consuming.
The further I added things up, the clearer the trend became: I was not hopeless with money; I was disengaged from it. The issue was not a single huge, reckless purchase, but hundreds of small decisions made on autopilot. Every card tap seemed insignificant alone, yet collectively they were changing my financial narrative.
Here is the simple reality: money does not vanish; it gradually escapes through areas you no longer notice.
Once that became clear, the message landed. My spending involved more than numbers; it reflected habits, emotions and the narratives I repeated to myself. My bank statements knew more about those stories than I did.
The simple habit that changed how I spend
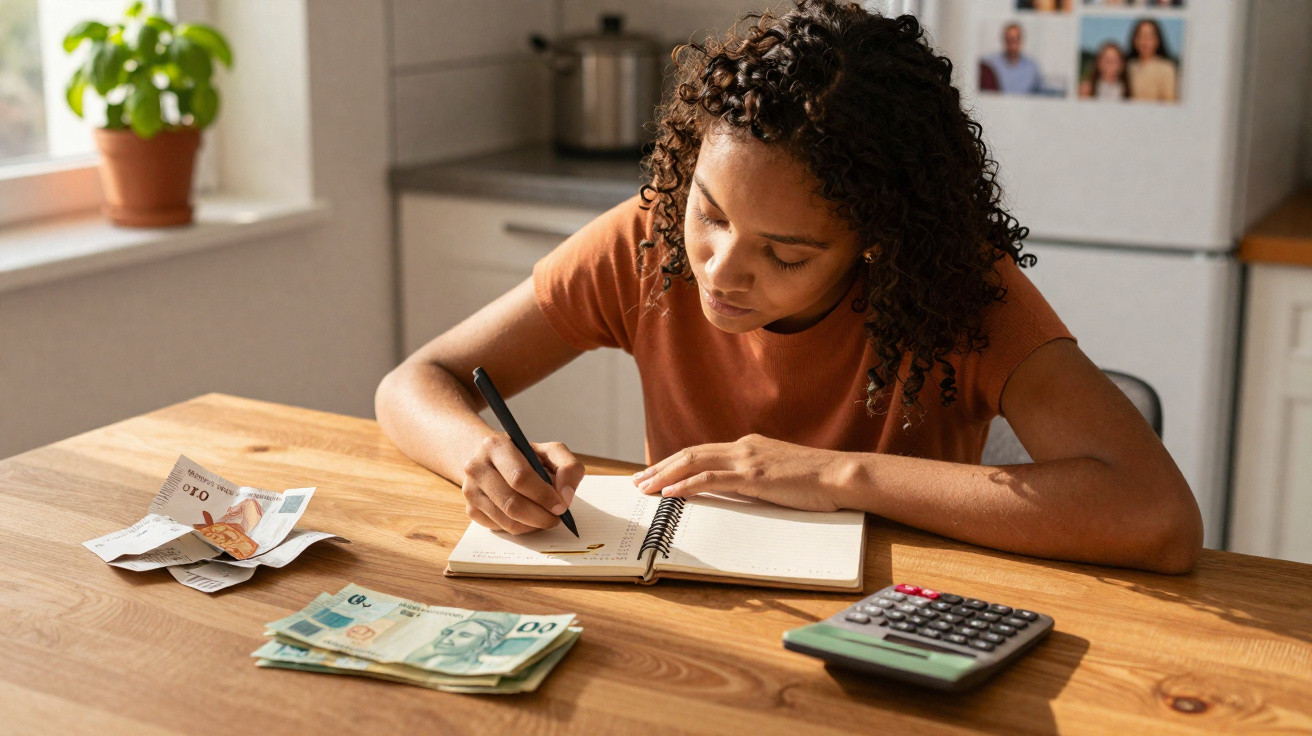
After seeing five years of my former self recorded on paper, I introduced one modest, almost dull routine: every month, I would have a “transaction date” with my money. There was nothing elaborate about it: just 30 minutes, a notebook, my banking app and some uninterrupted time.
I chose one fixed day each month, treating it as a regular appointment. I would review every outlay and assign one of three labels: “Need”, “Enjoyed”, or “Didn’t care”. There was no judgement and no spreadsheet, only truthful categorisation. I was not trying to feel ashamed; I was trying to remember.
The first time I did it, something unexpected happened. Simply knowing that Future Me would read each entry later altered how Present Me spent. That £18 impulse buy I would normally excuse by saying “I’ve had a long day” felt less appealing when I pictured labelling it “Didn’t care” afterwards.
We all know that point at the checkout: exhausted, looking at your phone, pressing “Apple Pay” because it seems easier than dealing with how you feel.
This small monthly practice did not transform me into a saintly minimalist. It merely created enough pause for me to stop deceiving myself.
There were slip-ups. Some months, I missed the review and told myself I would “catch up later”, which, naturally, never happened. Honestly, no one manages this every single day.
Letting go of perfectionism made the difference. My aim was not to account for every penny indefinitely. I just wanted to spot the most obvious drains: overlooked subscriptions, routine coffees and “temporary” services I had never cancelled.
Suddenly, the question wasn’t “How can I spend less?”
It became “What am I actually willing to keep paying for, month after month, with my one real life?”
- Cancel one unused thing rather than ten.
- Retain one luxury you genuinely love, and enjoy it properly.
- Mark every expense that still made you truly happier a week afterwards.
- Circle the purchases you cannot even recall, and begin with those.
- Do it again next month, even when it is untidy and imperfect.
The money story your statements are trying to tell you
When I revisit those five years now, I see more than pounds wasted. I see several versions of myself: the stressed person travelling home late, the lonely one scrolling at midnight, and the optimistic one enrolling on a course and genuinely completing it.
My most important lesson was not “spend less”. It was “spend like the person you want to become, not the person you’re trying to comfort in the moment”. At times, that still means ordering a takeaway, taking an Uber or buying a coffee. The change is that I notice it now. I take responsibility for it.
Your bank statements are not a judgement. They are a mirror.
They reveal where your focus goes once you stop consciously focusing. They show who matters to you, what comforts you, what exhausts you and what excites you enough to buy repeatedly. Some entries will make you feel proud, while others will make you wince. Both reactions have value.
If you ever feel brave enough to print five years of statements, do not only search for the “bad” purchases. Look instead for proof of what you value: the train fare to visit a friend, the donation you had forgotten about, or the class you booked that shifted your career slightly.
You do not need to become a budgeting machine. You do not have to eliminate every “silly” purchase. Nor do you require 12 apps and a colour-coded system.
What matters is one candid, regular meeting with your own figures. One small practice that says: “I’m here now. I’m paying attention.”
The financial lesson I took from five years of statements is remarkably straightforward.
Your future is hiding in those lines.
You just have to be willing to read it.
| Key point | Detail | Value for the reader |
|---|---|---|
| Track invisible habits | Frequent smaller purchases can accumulate beyond occasional major expenses | Helps uncover leaks that quietly prevent saving and reaching goals |
| Monthly “transaction date” | A 30-minute review for tagging expenses as Need / Enjoyed / Didn’t care | Brings awareness to spending without complicated budgeting tools |
| Spend with intention | Keep purchases that genuinely bring value and remove those you do not remember | Connects money to personal values while preserving space for enjoyment |
FAQ:
How far back should I review my bank statements?
Begin with three months, and expand to a year if possible. Five years is revealing, but even 90 days will expose patterns.What if I feel ashamed when I look at my spending?
That response is normal. Approach it as you would an old journal: you are not criticising your past self; you are learning from them.Do I need a budgeting app to do this?
No. A notebook, highlighter or straightforward notes app will do the job of labelling purchases and spotting patterns.How often should I review my transactions?
For most people, monthly is suitable. Pick a repeating date and safeguard it like any other appointment.What’s the first thing I should cut if money is tight?
Search for recurring payments you neither remember nor care about. Cancel one item this month instead of attempting to remove everything at once.
Comments
No comments yet. Be the first to comment!
Leave a Comment