
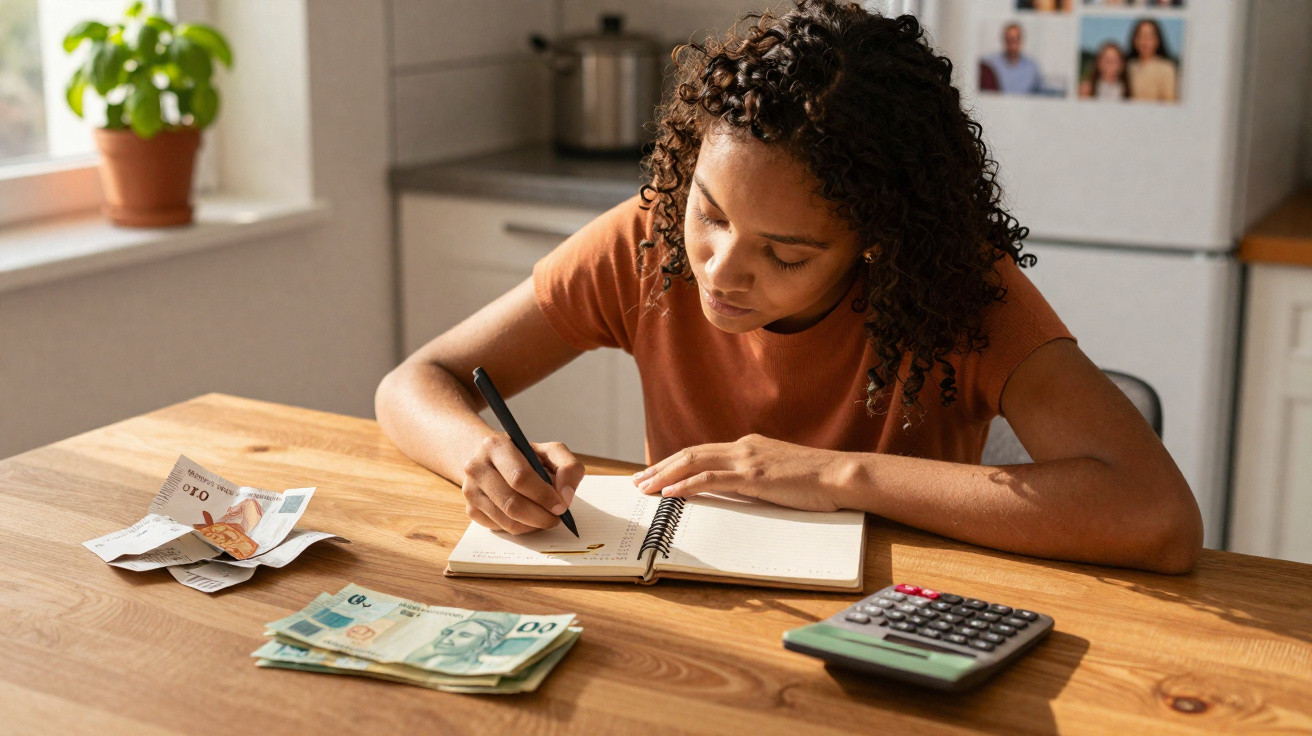
”. Then you meet that colleague or friend who somehow puts aside £300 or £400 every month despite earning little more than you do. There is no miracle and no hidden inheritance. Just a slightly battered notebook on the kitchen table, filled with columns, colours and neatly ordered figures. It is nothing like a cutting-edge app. Instead, it feels almost school-like and a little old-fashioned. Yet it works. On those pages, money begins to tell an entirely different story.
Why a simple notebook quietly outperforms most budgeting apps
You see the difference the first time you watch somebody use one properly. They are not scrolling, tapping or being pulled away by notifications. They sit down, open the notebook, rule the same handful of lines across a page and record the date, amount, category and a brief note. Using a pen slows the process just enough for the mind to catch up with the money. That small physical interruption - opening the notebook and locating the right page - creates a brief checkpoint between “I want this” and “Should I spend this?”. That is where monthly savings begin to build.
A 2023 YouGov survey on UK money habits found that people who manually tracked their spending, on paper or in a spreadsheet, reported saving an average of 18–22% more each month than those who depended solely on banking apps with automatic categories. Laura, 32, from Manchester, showed me her “ugly money notebook” over coffee. It had no stickers or elaborate styling, only three columns and a highlighter. After receiving a worrying overdraft letter, she began recording every payment over £2. Six months afterwards, she had £1,150 in an emergency fund and insisted that the notebook was the only genuine change she had made.
There is a straightforward reason this low-tech approach is so effective. Handwriting demands what psychologists call “deep processing”. Rather than merely entering an expense, you briefly revisit the moment when you made it. As a result, wasteful habits become easier to identify. A notebook also comes with a natural restriction: every page has finite space. If a category such as food delivery starts visually dominating the sheet, your mind registers “too much” long before your bank issues an alert. People who regularly save more each month are not necessarily more disciplined. They have simply created a physical feedback loop that their brains cannot easily overlook.
The notebook layout that turns expense tracking into saving
People who maintain this habit successfully do more than simply “write stuff down”. They follow an uncomplicated layout they can repeat on every page. On the left is a slim date column, followed by a slightly wider column for the amount. Next comes a larger space for the category and a very brief comment, such as “coffee before meeting” or “panic takeaway, late train”. On the far right, they reserve a narrow margin for one symbol: a tick when they would gladly make the purchase again, or a small dot when it felt unnecessary. This modest visual system quietly influences later decisions.
James, a 28-year-old nurse in Leeds whose saving routine I followed for a month, had made this format into a personal ritual. After every shift, he spent five minutes at the kitchen table with his notebook open and his phone face-down. He used only two highlighters: green for “needs” and orange for “wants”. Within three weeks, one area of his pages had become a block of orange: snacks from the hospital vending machine. None of the purchases seemed dramatic - £2 here and £3 there. But when he saw how much of the page they filled, he replaced half of them with homemade snacks. By month-end, his savings had risen from £80 to £210, without a side hustle or overtime.
The reasoning behind this structure is almost deliberately dull, and that is exactly its strength. Keeping the date, amount and category separate stops your mind from merging everything into a hazy sense that “I just spent a lot”. The short comment supplies context, allowing you to understand why you spend rather than only how much. The symbol column on the right is the page’s quiet standout feature: it changes the notebook from a guilt diary into a guide for later choices. After a few weeks, you will notice which kinds of spending repeatedly receive a “regret” mark. That is precisely where painless savings can be found. People who save more are not magically stronger; they have simply made their money habits more visible than their excuses.
How to start a savings-friendly notebook without feeling overwhelmed
The simplest way to imitate what “natural savers” do is to make the process small enough to sustain. You need one compact notebook, one pen and two highlighters. On the month’s first double-page spread, create four main columns: Date, Amount, Category and Note. Include a thin additional column at the far right for a tick or small cross. Next, choose a clear rule: record only spending above a set limit, such as £2 or £5. This prevents the notebook becoming another job while still capturing the meaningful movement of your money.
Begin with only seven days of tracking. Do not commit to a month or to doing it forever; commit to one week of truthful figures. Let us be honest: nobody genuinely does this every day, all year round, without ever missing one. Successful people miss days as well; they simply resume without making a fuss. If you return after a break, circle the unrecorded dates, write “no tracking”, and continue. Perfection is not the point. The aim is to create a visible account of your money that says more than “I’m terrible with cash”. Be gentle with yourself as spending patterns you dislike start becoming clear.
One woman I interviewed had written a sentence inside the front cover of her notebook:
“This is not a book of shame. It’s a map.”
That sentence transformed how she responded to her figures. Rather than criticising herself, she began making adjustments. You could also support your future self by adding a small “toolbox” section at the end of each month:
- Circle one category you want to reduce next month.
- Write one specific replacement action, for example “1 fewer takeaway, 1 more batch cooking night”.
- Record one thing you are pleased you spent money on.
This balance between restraint and permission keeps the notebook human. Saving more each month is not about becoming a machine; it is about becoming slightly more curious about what your money is actually doing when you are not paying attention.
A notebook will not save money for you - but it changes the narrative
When you speak to people who consistently save more every month, what stands out is not their willpower. It is their view of spending as something they can revise. The notebook is simply their editing instrument. It shows them that £20 vanishes into online orders every Friday night, or that supposedly casual coffee stops cost more than a gym membership. Gradually, the narrative changes from “I’m bad with money” to “Here’s the scene I can rewrite next month”. This is the point at which saving stops seeming like a punishment and begins to feel like a choice.
Sharing this sort of notebook can be unexpectedly connecting, too. Some couples discreetly compare their pages at month-end, not to monitor one another but to agree on a shared change. Friends saving for a trip may exchange photographs of their highlighted pages, laughing and cringing together at similar spending habits. Physical pages encourage conversations in a way that an impersonal bank statement rarely can. Once people begin discussing money frankly, the invisible beliefs they grew up with - “I deserve this”, “I’m not good with numbers” - can start to loosen.
The real secret of smooth, consistent savers is rarely a larger income or brilliant investment. More often, it is a slightly dog-eared notebook in which every entry represents a small act of honesty. Some months will be untidy, some pages nearly blank and others packed with unforeseen bills. Still, tracking in a clear and specific format keeps you involved in the story. It provides something tangible to hold onto when the figures feel unmanageable. The question is not whether you are “a saving type of person”. It is whether you are prepared to spend enough time with your money, pen in hand, for a different pattern to gradually emerge.
| Key point | Detail | Benefit for the reader |
|---|---|---|
| Notebook layout | Clear columns for Date, Amount, Category and Note, plus a symbol column | A simple format to replicate that quickly exposes spending habits |
| Handwriting effect | Writing by hand slows decisions and increases awareness | Can reduce impulse purchases and emotional spending |
| Weekly ritual | Brief, regular reviews rather than flawless daily recording | Keeps the habit realistic, sustainable and less stressful |
FAQ:
- Do I really need a physical notebook, or can I use my phone? You can use your phone, but many people find that a physical notebook brings greater focus and fewer distractions, leading to better saving results.
- How many expenses should I track each day? Record any expense above a threshold you choose, such as £2 or £5, so the practice remains quick while capturing most of your spending.
- What if I miss several days or even a week? Mark the missed days, write “no tracking”, then restart from today; the habit lasts as long as you return to it without guilt.
- How fast will I see extra savings using this method? Most people spot clearer patterns within two to three weeks and see genuine savings growth in one to three months.
- Do I need to keep this notebook forever? No. Treat it as a tool to use intensively at first, then occasionally whenever you feel your spending starting to drift again.
Comments
No comments yet. Be the first to comment!
Leave a Comment